



PW Consulting: Balancing Valves Market Poised for 5.8% CAGR Through 2032

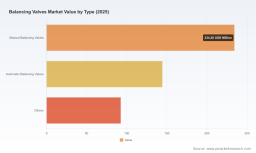
Balancing Valves Market — Strategic Outlook for 2026 Decision‑Makers
Executive teaser
As organizations recalibrate capital allocation and product roadmaps for 2026, the Balancing Valves market is emerging as a pragmatic lever to capture durable efficiency gains across HVAC and hydronic systems. PW Consulting’s forthcoming market brief synthesizes seven years of historical data (2020–2025) and a seven‑year forecast window (2026–2032) to translate market momentum into decision‑grade insights. The market expanded from USD 355.5 Million in 2020 to USD 471.27 Million in our base year (2025) and, under a 5.8% CAGR through the forecast horizon, is projected to approach USD 699.3 Million by 2032. This introduction outlines why that trajectory matters for strategic moves in 2026 — and what our full report provides to guide them.
Balancing Valves Market
Market snapshot: momentum and structural drivers
-
Growth trajectory: Between 2020 and 2025 the market grew significantly (USD 355.5M → USD 471.27M). Our forecast starts at USD 489.64 Million in 2026 and, at a compound annual growth rate of 5.8% for 2026–2032, reaches USD 699.31 Million by 2032. These figures reflect both retrofit demand and new construction adoption driven by energy code tightening and operational cost optimization.
Balancing Valves Market -
Regulatory tailwinds and standards: The field is being reshaped by formal standardization — most notably ISO 16484‑4:2025, which for the first time defines dynamic balancing systems and performance classes for hydronic networks. Parallel policy signals (including documented increases in the share of retrofits and code‑driven uptake in new office designs) are accelerating baseline demand for balancing solutions that can demonstrably reduce energy use and improve occupant comfort.
Balancing Valves Market -
Input cost and supply risk: Raw material volatility remains a live risk. For example, steel market metrics show upward pressure (notably mid‑2026 pricing spikes), reinforcing the need for procurement playbooks that buffer margin erosion through hedging, supplier diversification, or design material substitutions where feasible.
Why this matters for 2026 corporate strategy
-
Prioritize product‑market fit under new standards: With ISO 16484‑4 now in the market lexicon, product portfolios must be audited against performance classes (A/B/C). Packages that combine dynamic balancing hardware with commissioning and measurement protocols will command premium positioning in commercial retrofits and code‑compliant new builds.
-
Capture retrofit economics: A notable share of efficiency upgrades now include balancing valves as a cost‑effective measure to realize measured savings. For equipment manufacturers and distributors, this shifts sales tactics from component selling to system outcomes — e.g., guaranteed delta kWh or normalized energy performance contracts linked to valve deployment.
-
M&A and consolidation scouting: The market concentration metrics (CR3 ~41%, CR5 ~48%) indicate a moderately consolidated field with space for bolt‑on acquisitions to build geographic or capability scale. Strategic buyers in 2026 should prioritize targets that provide certified dynamic balancing technology, digital commissioning capabilities, or channel access to large HVAC service providers.
-
Service and lifecycle monetization: The migration from manual to dynamic balancing approaches creates recurring revenue pathways — commissioning, digital monitoring subscriptions, warranty extensions, and performance remediation services. Recent commercial signalling — extended warranties and showrooming at major trade events — suggests warranty and service packaging will become a competitive battleground.
What PW Consulting’s full report delivers (select actionable modules)
-
Market sizing and validated forecasts: Annualized market figures from 2020–2025, with bottom‑up scenario modeling for 2026–2032 under multiple adoption and policy scenarios.
-
Commercial segmentation playbook: A pragmatic segmentation framework that maps product types, applications, and sales channels to profitable go‑to‑market motions — including bundle strategies for retrofits versus OEM new builds. (Note: granular regional and application splits are included in the full report and intentionally withheld from this preview.)
-
Procurement and cost management toolkit: Supplier scorecards, raw material sensitivity analyses, and hedging case studies tailored to valve manufacturers and distributors.
-
Standards and compliance matrix: Interpretation of ISO 16484‑4 performance classes and a practical implementation checklist for R&D, testing labs, and product managers.
-
M&A screening model: Deal‑sizing heuristics, integration risk templates, and five candidate archetypes (technology, channel, geographic, service, and vertical OEM) to evaluate return on investment for 2026 transactions.
-
Commercial war‑game and pricing simulations: Scenario playbooks for warranty offers, bundled service contracts, and tiered product launches that protect margin while accelerating share.
Competitive landscape: who’s shaping the field and how
The market blends legacy valve specialists with pump and control integrators. Legacy and specialist manufacturers retain technical leadership in hydronic balancing, while broader systems players leverage channel reach and integrated system offerings. Key industry participants include established U.S. manufacturers known for HVAC and commercial building solutions, European firms with deep hydronics and dynamic balancing portfolios, and pump OEMs offering combined pump‑valve solutions. Recent market signals include a notable acquisition and standardization moves that will reframe competitive dynamics.
-
Specialist valve firms (examples): Several North American firms are highly focused on HVAC balancing valves for commercial and industrial use, prioritizing robustness and retrofit fit. Their go‑to strengths are installer familiarity, broad distributor networks, and competitive service offerings.
-
European hydronics leaders: Manufacturers from Europe lead in dynamic balancing technology and standards compliance. Their portfolios tend to emphasize measurement accuracy, integration with building automation systems, and product families mapped to ISO performance classes.
-
System integrators and pump OEMs: Entities that supply pumps alongside valves can sell whole‑system efficiency narratives to engineering‑procurement construction (EPC) firms, which is a growing advantage in large commercial and district heating projects.
Strategic developments to watch (recent highlights):
-
Standards momentum: The formalization of ISO 16484‑4:2025 elevates dynamic balancing performance as a procurement criterion — favoring vendors that can certify performance and offer standardized commissioning regimes.
-
Corporate moves: Consolidation activity (including the acquisition of a dynamic‑valve specialist by a larger valve group) signals buyers’ appetite for capability consolidation and geographic scale.
-
Commercial innovation: Warranty extensions and expanded trade show engagement point to more aggressive commercial plays around assurance and installer education. These tactics can shift procurement toward bundled offerings that lock in service revenues.
Strategic playbook: recommended 90‑ to 360‑day actions for 2026
-
90 days — Portfolio triage: Audit existing valve and control SKUs for compliance with ISO 16484‑4 classes; fast‑track lab testing or third‑party certification for top sellers; adjust pricing to reflect new compliance value.
-
180 days — Channel and service pilots: Launch two geographically targeted retrofit pilots that bundle dynamic balancing hardware with digital commissioning and a warranty uplift. Use measured outcomes to build a repeatable sales case for EPCs and property managers.
-
360 days — Strategic growth moves: Evaluate bolt‑on acquisitions that (a) supply certified dynamic balancing tech, (b) provide local commissioning capabilities, or (c) open a priority channel. Parallelly, implement a procurement strategy to mitigate raw material exposure — including multi‑sourcing and indexed supply contracts tied to steel price movements.
Data, methodology and where to go next
Our analysis is anchored on base year 2025, historical tracking for 2020–2025, and a forecast period of 2026–2032. It combines primary interviews with OEMs, distributors and commissioning firms, structural modeling of construction and retrofit cycles, and sensitivity testing against commodity and regulatory scenarios. The full PW Consulting report contains the granular regional, type, and application splits, supplier scorecards, detailed M&A target archetypes, and downloadable modeling templates — data intentionally withheld in this preview to preserve the report’s transactional value.
Final note — the strategic value proposition
For 2026 decision‑makers the Balancing Valves market is not merely a hardware segment; it is a measurable lever to improve system efficiency, reduce operating expenses, and generate recurring service revenues. The convergence of new standards, retrofit spending, and commercial warranty innovation creates a narrow window for companies to reposition: those that certify performance, reinforce channel execution, and de‑risk supply will translate market growth (from USD 471.27M in 2025 toward USD 699.31M by 2032 at a 5.8% CAGR) into sustained competitive advantage. PW Consulting’s full report equips leaders with the playbooks, models, and due‑diligence tools to act decisively in 2026.
To access the complete dataset, granular segmentation, and executable annexes, please visit the PW Consulting report page or contact our Balancing Valves market desk for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Balancing Valves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


