



PW Consulting: Urokinase Market to Reach USD 263.5M by 2032 at 5.9% CAGR

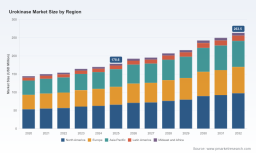
Urokinase Market 2026: Strategic Preview for Executives — A PW Consulting Brief
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise yet incisive preview of our Urokinase Market research — designed to orient executive decision-making in 2026. This briefing synthesizes the market’s recent trajectory, near-term regulatory inflection points, competitive dynamics, and the commercial levers that will determine winners and laggards over the next investment cycle. We show the analytic depth behind our conclusions while intentionally reserving detailed segmentation tables and unit-level forecasts for the full report.
Urokinase Market
Market snapshot: what the numbers tell us
Measured on a global basis, the urokinase market matured from roughly USD 144 million in 2020 to about USD 178.6 million in 2025. Momentum persists into the forecast window: our base-case model projects continued expansion at a mid-single-digit compound annual growth rate (CAGR) of about 5.9% through the 2026–2032 horizon, with the market reaching roughly USD 263.5 million by 2032 under the central scenario.
Urokinase Market
Two takeaways are immediate for 2026 planning. First, this is a market large enough to sustain differentiated, margin-accretive plays (novel formulations, branded reintroductions, and specialty clinical pathways), yet small and fragmented enough that focused tactical moves can materially shift competitive positions. Second, steady headline growth masks critical chokepoints — regulatory timing, manufacturing readiness, and distribution friction — which will determine whether the growth is captured by incumbents, newcomers, or both.
Urokinase Market
Why 2026 is a strategic pivot
- Regulatory inflection: Legacy assets and reformulated biologics are entering regulatory cycles that will change commercial access. In particular, planned sBLA pathways and manufacturing modernization programs for established urokinase products create a narrow window in which regulatory progress will translate directly to revenue re-entry.
- Manufacturing and supply-chain reconfiguration: Recent CDMO partnerships and production modernization efforts point to an industry re-alignment where capacity ownership and contract-manufacturing relationships will confer first-mover advantage in the most commercially attractive indications.
- Commercial pressure from generic supply: A global set of manufacturers, particularly firms focused on sterile injectables and export markets, is sustaining price competition and broad availability across clinical settings. Organizations that rely solely on price competitiveness risk margin erosion without a clear scale plan.
What our report delivers — practical, transaction-ready intelligence
The full PW Consulting study goes beyond headline forecasts to provide a toolkit you can use in 2026 to make decisions today. Key modules include:
- Comprehensive market-sizing methodology and a dynamic financial model with scenario and sensitivity levers (policy, adoption, pricing, and supply shocks).
- Regulatory blueprints and timelines for re-authorization and supplemental filings, including stepwise decision trees for sBLA-style pathways.
- Supply-chain and CDMO evaluation frameworks: supplier risk scoring, on-time-to-scale modeling, and capital vs. contract capacity tradeoffs.
- Competitive benchmarking that combines capability maps, route-to-market analysis, and M&A archetypes to identify attractive consolidation targets and partnership fits.
- Commercial playbooks for segmentation by clinical pathway (acute thrombolysis, catheter clearance, hospital pharmacy), tendering matrices, and reimbursement negotiation tactics.
- Investment and M&A diligence checklists: valuation sensitivities tied to regulatory milestones, clinical uptake, and margin assumptions.
Competitive landscape — who matters and why
The market is notably fragmented; top-tier concentration is modest, reflecting a landscape where regional manufacturers and specialist players coexist with legacy branded assets. That fragmentation creates strategic space for consolidation, differentiated product strategies, and targeted clinical positioning.
Microbix Biosystems stands out as a strategic focal point. As the steward of a globally approved low-molecular-weight urokinase, the company has pursued re-commercialization through CDMO partnerships and regulatory relaunch strategies focused on catheter clearance and other acute-use scenarios. Their recent manufacturing partnerships and production modernization initiatives are material: they reduce technical risk ahead of planned regulatory filings and de-risk supply for potential U.S. re-entry. For potential partners, acquirers, and distributors, the Microbix trajectory illustrates the commercial upside of combining regulatory stewardship with scalable contract manufacturing.
At the same time, a cohort of established injectables manufacturers — including several India-based producers and global sterile-injectable suppliers — maintain broad supply footprints and price-competitive offerings. Their strength is operational: scalable sterile facilities, export-oriented distribution, and product portfolios that serve hospital and emerging-market channels. These firms reinforce pricing discipline in the market, particularly in non-premium segments.
Strategic implications by stakeholder
- Pharma/biotech holders of urokinase assets: Prioritize regulatory timelines and CDMO secures. A clearly articulated sBLA pathway (or equivalent) combined with validated contract manufacturing will enable timely market re-entry and value capture. Consider phased launches that pair catheter clearance rollouts with targeted evidence generation to accelerate hospital adoption.
- CDMOs and contract manufacturers: Invest selectively in sterile-fill capabilities and regulatory support services. Offer integrated packages (process modernization + regulatory dossier support) to be the preferred partner for re-launches; build commercial SLAs that align incentives with successful approvals and on-time delivery.
- Distributors and hospital systems: Differentiate procurement by total cost of care rather than unit price. Suppliers who can substantiate reduced administration costs, simplified logistics (e.g., powder formats that cut cold-chain dependency), or superior clinical support will win formulary share.
- Private equity and strategic buyers: Look for bolt-on targets where regulatory clarity or CDMO relationships unlock disproportionate value. Fragmentation means synergies are achievable through consolidation of distribution, regulatory dossiers, and manufacturing capacity.
High-conviction plays for 2026
- Secure or strengthen CDMO partnerships early. Manufacturing readiness is the gating factor for any regulatory relaunch and the principal lever for time-to-revenue.
- Differentiate with formulation strategy. Powdered formats that reduce cold-chain costs and extend shelf life have discrete commercial advantages in certain markets and care settings.
- Target niche clinical pathways where payers and clinicians accept premium positioning (for example, catheter-related indications) while simultaneously defending broad-volume channels through competitive pricing and service.
- Prepare for multi-speed regional strategies. The same product will require different commercial and regulatory playbooks across major regions; aligning these in 2026 will accelerate scale after approval milestones.
- Build an evidence-generation roadmap that pairs early post-market surveillance with value-based contracting pilots, especially for higher-acuity indications where economic arguments matter.
Decision tools included with the full study
To move from insight to action, PW Consulting’s full report includes:
- Interactive financial models (base, upside, downside) tied to regulatory milestones and adoption curves.
- CDMO selection scorecards and negotiation playbooks.
- Go-to-market roadmaps with resource and timing overlays for phased launches.
- M&A screening matrices calibrated to regulatory, manufacturing, and distribution vectors.
- Risk heatmaps and mitigation plans for supply disruptions, pricing shocks, and rapid generics entry.
Closing perspective — what to prioritize this quarter
If you are evaluating exposure to the urokinase market in 2026, your near-term checklist should be short and executable: validate your manufacturing pathway (internal or CDMO), map regulatory milestones against your go-to-market timeline, and stress-test pricing and tender scenarios against a fragmented supplier base. The macro backdrop — mid-single-digit CAGR and a market size that has materially expanded since 2020 — means there is growth to capture; but timing and execution will determine who captures the premium versus who competes primarily on price.
PW Consulting’s full Urokinase Market report contains the granular segmentation, model inputs, and tactical annexes required to underwrite investment cases and commercial launches this year. For decision-makers seeking to convert insight into action, the detailed breakdowns and scenario-ready tools in the report are the operational next step.
For detailed analysis of this topic, please visit the official page: Urokinase Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


