



PW Consulting: Fire Truck Market to Reach USD 253.9M by 2032, 6.9% CAGR (2026–2032)PW Consulting: Laundry Detergent Market to Reach USD 106.43 Billion by 2032 at 4.48% CAGR

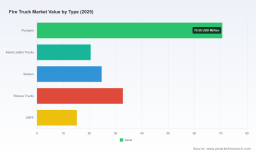
Fire Truck Market: Strategic Imperatives for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise, decision‑focused introduction to our full Fire Truck Market study. This briefing is written for procurement leaders, fleet strategists, OEM executives, and infrastructure investors who must make near‑term capital and operational choices in 2026 with implications across the 2026–2032 planning horizon. It synthesizes macro growth trajectories, competitive dynamics, regulatory inflection points, and the practical levers that can materially alter total cost of ownership (TCO) and mission readiness — while reserving detailed segment tables and granular forecasts for the full report.
Fire Truck Market
Why 2026 is a Pivot Year
Two converging forces make 2026 a strategic inflection point for fire apparatus buyers and suppliers. First, the market continues to expand at a mid‑single‑digit compounded annual growth rate (6.9% CAGR) through the forecast window, reflecting replacement cycles, rising unit prices, and incremental electrification and capability upgrades. Second, regulatory and standards updates are compressing timelines for hardware and powertrain choices: heavy‑duty engine emissions standards take effect for model year 2027, and industry bodies are actively debating specifications designed to standardize and lower base apparatus costs.
Fire Truck Market
Taken together, these forces change the calculus for procurement and fleet renewal. Organizations that defer strategic decisions in 2026 risk higher acquisition prices, longer lead times, and missed opportunities to pilot low‑emission platforms under real operational loads.
Fire Truck Market
Market Size and Outlook (Macro View)
Our base‑year assessment is anchored in 2025 market sizing and a forward outlook that extends to 2032. The market expanded steadily through the early 2020s and, under our base case, continues to grow on a trajectory that supports increased investment in both legacy and emergent apparatus types. For budget planning, fleet managers should assume a materially larger capital envelope will be required relative to five years prior — driven by higher base prices, more sophisticated technical fitments, and electrification premiums during early adoption.
What the Full Study Contains (Practical, Operational Deliverables)
- Consolidated market model (2020–2025 history; 2026–2032 forecast) with three scenarios (base, conservative, accelerated) and sensitivity levers for price inflation, electrification uptake, and lead times.
- Procurement playbook: specification templates, competitive RFP constructs, TCO templates tuned to apparatus lifecycles, and financing/lease calculators.
- Supplier benchmarking and capability heatmaps across manufacturing scale, modularity, e‑powertrain readiness, aftermarket coverage, and delivery performance.
- Operational readiness frameworks: retrofit vs. replacement decision trees, depot infrastructure needs for electric apparatus, and crew training roadmaps.
- Regulatory and standards impact analysis mapping EPA heavy‑duty engine rules, NFPA activity, and likely compliance timelines to procurement decisions.
- Supply‑chain stress test and mitigation playbook: critical raw materials, chassis sourcing strategies, alternate supply lanes, and inventory buffering recommendations.
- Investment and partnership blueprints for OEMs and Tier‑1 suppliers — including go‑to‑market sequencing, pilot program designs, and aftermarket service monetization strategies.
The full dataset, including the segmented tables by geography, apparatus type, and end‑use application, and the supplier scorecards referenced above, are intentionally withheld in this summary to preserve the commercial utility of the full report and to drive stakeholders to download the comprehensive package from our web repository.
Competitive Landscape: What Buyers and Investors Should Watch
The market structure is midly concentrated: a small group of established builders capture a meaningful share of traditional apparatus demand, but a healthy long tail of specialty shops and regional players remains. This structure creates differentiated pathways to scale for OEMs that can combine manufacturing discipline with innovation in powertrain and electronics.
- Pierce Manufacturing, E‑ONE, Ferrara, KME, and Rosenbauer represent legacy capabilities in custom apparatus and broad product lineups; their scale and dealer networks remain decisive for large municipal programs and mutual aid regions.
- Sutphen, Fouts Fire, Fenton, Acela, and 10‑75 Emergency Vehicles occupy niches where customization, weight optimization, or rapid build cycles are prioritized. These builders often win work on the strength of specialized chassis configurations and regional relationships.
- New product launches and cross‑industry partnerships (notably the emergence of electric aerial platforms and e‑chassis collaborations) are changing competitive dynamics: OEMs that can validate electric platforms in frontline service earliest will gain a meaningful commercial advantage as municipalities and airports integrate sustainability criteria into procurement.
For OEMs and suppliers, our recommendation is clear: prioritize demonstrable reliability for new propulsion systems, standardize modular subsystems to reduce build complexity, and strengthen aftermarket service networks to protect margins as EV premiums compress over time.
Regulatory and Standards Shockwaves
Regulatory updates are already shaping product roadmaps and inventory choices. Implementation of multi‑pollutant emissions standards for heavy‑duty engines beginning with the model‑year 2027 regime compresses the window for ordering pre‑compliant vehicles and affects residual values for pre‑2027 builds. Concurrently, industry standards bodies are promoting reduced‑cost standardized base specifications for apparatus, a development likely to reframe procurement in rural and suburban markets where budgets are most constrained.
Practical implication: procurement teams should synchronize specification updates with compliance timelines, consider staggered replacement strategies, and evaluate early adoption pilots for alternative drivetrains only where depot charging and technical support are secured.
Technology and Cost Dynamics
Two structural cost dynamics are central to 2026 strategy:
- Unit price inflation: Apparatus base prices have risen substantially over recent years. Buyers should model future capital needs on elevated base prices and incorporate scenario buffers for high‑spec units.
- Electrification and modularization premiums: Early electric apparatus command a price premium and require upfront infrastructure investment; however, they can deliver lifecycle operating savings in specific duty cycles. Modular designs and standardized specs will attenuate build costs over the medium term.
Our TCO models, included in the full study, quantify these trade‑offs for municipal, industrial, airport, and specialized military use cases — and include payback curves under multiple fuel and energy price regimes.
Recent Developments that Matter Now
- NFPA position papers supporting a National Fire Apparatus Specification aim to reduce apparatus costs by encouraging standardized base models — a structural change that could expand procurement options for budget‑constrained agencies.
- OEM activity in electrification (notably the publicized debut and deliveries of electric aerial and rescue platforms) demonstrates that credible, fielded electric solutions are transitioning from concept to operational reality. Early adopter deployments provide valuable operational data for wider rollouts.
- Industry association updates on purchasing conditions, lead times, and evolving emission standards are actively shaping order calendars and risk assessments for 2026–2027 procurement cycles.
Strategic Playbook for 2026
Every organization’s optimal move set will differ by mission profile and budget, but the following high‑level plays are universally relevant in 2026:
- Align procurement timelines with the 2027 emissions milestone. Where possible, secure flexible contracts that allow specification adjustments without punitive penalties.
- Deploy limited pilots for electric apparatus in controlled duty cycles (e.g., station‑based rescue units or short‑range pumpers) to capture operational data and refine depot charging strategies before committing to fleetwide conversions.
- Insist on modular specifications and interoperable subsystems in RFIs/RFPs to lower long‑term maintenance complexity and reduce vendor lock‑in.
- Stress‑test supplier networks against critical material disruptions and extend warranty and service agreements to cover transitional risks associated with new powertrains.
- Quantify lifecycle costs under multiple energy and maintenance cost scenarios; use this as the basis for public communications and funding requests to justify capex shifts.
Call to Action
This overview is designed to frame the key strategic choices for 2026. The full PW Consulting Fire Truck Market study delivers the underlying data, detailed segment breakdowns, supplier scorecards, executable procurement templates, and the TCO microsimulations that turn insight into actionable decisions. For procurement directors shaping 2026 capital programs, and for OEM executives plotting product and service roadmaps, the full report is the operational playbook — and the single source for the granular segment‑level and regional intelligence we intentionally withhold here to preserve commercial value.
To receive the complete study, including the segmented tables, supplier benchmarking, and downloadable procurement tools, please visit the PW Consulting research portal or contact our advisory team for a tailored executive briefing.
For detailed analysis of this topic, please visit the official page: Fire Truck Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


