



PW Consulting: Flow Chemistry Market Poised for 10.6% CAGR Through 2032

Flow Chemistry Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest Flow Chemistry Market briefing is written for executives, R&D leaders, investors, and strategy teams who must translate technological momentum into executable 12–36 month plans. Grounded on a 2025 base year and projecting through 2032, the study synthesizes market sizing, technology trajectories, regulatory inflection points, and supplier competitive dynamics to inform capital allocation, partnership selection, and go-to-market sequencing in 2026.
Flow Chemistry Market
Macro snapshot you can act on
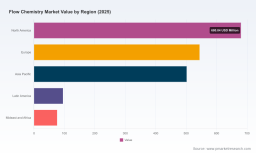
Between 2020 and 2025 the global flow chemistry market transitioned from an emerging synthesis enabler to a scaled industrial discipline: total market value rose from roughly USD 1.18 billion in 2020 to approximately USD 1.90 billion in 2025. Our base-case forecasts, underpinned by adoption rates in pharmaceuticals, specialty chemicals, and contract development and manufacturing (CDMO) services, project a continuation of robust growth through 2032 — with a compound annual growth rate of about 10.6% and a market approaching USD 3.84 billion by 2032. Such momentum creates windows for both fast followers and first movers, but timing and capability matters.
Flow Chemistry Market
Why this study matters for 2026 decisions
-
Investment timing: The 10.6% CAGR signals sustained demand for capital equipment, integrated services, and modular manufacturing capacity. Companies that build demonstrable pilot-to-commercial workflows in 2026 will capture disproportionate share as early adopters move to scale.
Flow Chemistry Market -
Regulatory tailwinds: Regulatory endorsements for continuous manufacturing — notably the industry shift following guidance such as ICH Q13 — reduce approval friction for drug-substance and drug-product implementations. Early regulatory engagement remains essential for de-risking scale-up roadmaps.
-
Operational leverage: Flow processes deliver measurable advantages on safety, solvent usage, and heat/mass transfer efficiency. When deployed with appropriate catalytic systems and automation, these advantages translate into lower per-unit operating cost and faster time-to-clinical or commercial supply.
-
Competitive spacing: Market concentration metrics indicate a market that is not dominated by a single incumbent: the top three vendors collectively account for roughly 30% of the market, while the top five account for about 42%. This degree of fragmentation favors specialized suppliers, nimble integrators, and vertically integrated CDMOs.
What the report contains — practical, decision-focused deliverables
-
Time-series market model (2020–2032) with scenario analysis. You receive the audited historical series and three forecast scenarios (base, accelerated adoption, and conservative) to stress-test investment cases.
-
Technology maturity matrix. Benchmarks for reactor classes, process analytical technologies (PAT), and automation stacks to guide capex phasing from lab through pilot to commercial lines.
-
Go-to-market playbooks. Actionable templates for OEMs, CDMOs, and biotech firms: channel strategies, pricing levers, and customer proof-point sequencing to shorten sales cycles.
-
Financial and operational models. CAPEX/OPEX modeling templates and unit economics calculators for evaluating reactor purchases, contract manufacturing partnerships, and greenfield continuous lines.
-
Risk and regulatory playbook. Checklists for ICH Q13 alignment, CE certification readiness for European operations, and best-practices for safety and environmental reporting.
-
Supplier diligence pack. Scorecards and interview-based risk assessments for key vendors and service providers to accelerate vendor selection with minimal on-site due diligence.
-
Case studies and adoption roadmaps. Anonymized, end-to-end examples of pharmaceutical and fine-chemical conversions to continuous processes, showing timelines, break-even points, and failure modes.
Competitive landscape — reading the positions without giving away the playbook
The competitive map combines specialist OEMs, modular systems providers, and vertically integrated CDMOs. A short synthesis of representative players illustrates the strategic contours you must weigh when choosing suppliers or partners:
-
ThalesNano: Known for bench-top continuous hydrogenation and photochemistry platforms — attractive for medicinal chemistry workflows and early-stage process intensification.
-
Chemtrix: Offers scalable glass and ceramic reactor platforms able to bridge mg-scale discovery to multi-tonne production, and has been integrated into broader industrial groups to accelerate scale-up capability.
-
Vapourtec: Focused on modular systems spanning entry-level to production-scale photochemistry and peptide synthesis — recent installations underscore momentum in peptide manufacturing and academic partnerships.
-
H.E.L Group: Emphasizes automated parallel synthesis, catalytic reactors, and crystallization systems that address process safety and high-throughput optimization for pharma and specialty chemicals.
-
Corning: Develops advanced-flow reactor architectures that target lab-to-industrial continuous flows with service-oriented lab support — suited for large-scale agri and specialty chemical players.
-
Syrris, AM Technology, Ehrfeld, CEM: Each brings differentiated strengths — modular lab systems, lab-to-pilot scale-up services, microstructured reactor technology, and microwave-assisted flow solutions respectively — enabling tailored supplier stacks for specific chemistry families.
-
Asymchem and other CDMOs: Increasingly offering CE-certified continuous equipment and end-to-end services that reduce customer time-to-market for APIs and specialty products.
Recent commercial activity through mid-2026 reinforces these strategic alignments: modular system installations for peptide production, expanded CDMO capabilities with CE-certified equipment, formal research partnerships to advance process safety, and corporate integrations aimed at strengthening scale-up competencies. These events are symptomatic of a market shifting from experimentation to industrialization.
Key strategic moves for each stakeholder in 2026
-
OEMs and instrument makers: Prioritize modular, serviceable architectures; bundle software and PAT; offer pilot-as-a-service to lower buyer switching costs.
-
Pharmaceutical companies: Move from pilot projects to select commercial lines for high-volume APIs; prioritize regulatory dossiers that demonstrate continuous processing benefits; lock in catalyst and specialty consumables supply agreements.
-
CDMOs: Invest in CE certification, scale-up platforms, and client-facing process labs; use success stories to win multi-year supply contracts.
-
Private equity and investors: Focus on asset-light integrators and vertically-aligned CDMOs with proven scale-up track records; value the optionality in service-led recurring revenue models.
-
Academic and national labs: Position as rapid prototyping hubs and talent pipelines for industrial partners; prioritize platforms that can translate directly to GMP environments.
How to use the research — practical engagement options
-
Scenario testing: Use our three forecast scenarios to stress-test capital budgets and vendor selection under different adoption curves and raw-material volatility assumptions.
-
Vendor shortlisting: Leverage the supplier scorecards and on-site assessment templates to reduce vendor selection timelines by months while preserving technical rigor.
-
Deal preparation: Apply the M&A playbook and valuation multiples within the report when evaluating acquisitions of niche flow technology providers or CDMO facilities.
-
Regulatory planning: Adopt the regulatory readiness checklist and sample submission timelines to align internal QA/RA teams with manufacturing pilots.
Closing perspective
Flow chemistry is at the inflection point between experimental technique and mainstream manufacturing. For 2026, the strategic questions are not whether to engage, but how deeply and in what sequence. This study delivers the market context, tactical playbooks, and vendor intelligence necessary to translate the macro trend — a market expanding at roughly a double-digit CAGR — into defensible, revenue-generating capabilities.
PW Consulting’s full Flow Chemistry Market report contains the detailed segmentation tables, supplier scorecards, and downloadable financial models that underpin these conclusions. For teams preparing 2026 budgets, partnership negotiations, or M&A diligence, the full dataset and appendices provide the granular inputs required to move from strategy to execution.
For detailed analysis of this topic, please visit the official page: Flow Chemistry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


