



PW Consulting: Zinc Pyrithione Market to Reach USD 179.25 Million by 2032 at 3.75% CAGR

Zinc Pyrithione Market: Strategic Signals for 2026 Decision-Making
Executive preview
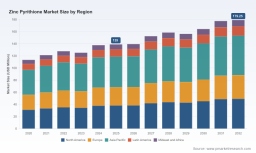
As companies plan product strategies, sourcing, and M&A activity for 2026, zinc pyrithione (ZPT) presents a mixed but actionable picture. Our PW Consulting Zinc Pyrithione Market study—anchored to a 2025 base year and a 2026–2032 forecast window—shows a market that has recovered from mid-cycle volatility and is set to grow at a steady mid-single-digit pace (CAGR 3.75%). The market size stood near USD 139 million in 2025 and our scenario workpoints to a balanced expansion through 2032 under current regulatory and raw-material cost trajectories.
Zinc Pyrithione Market
Why this matters in 2026
- Procurement and supply-chain managers must reconcile rising input and logistics costs with stable but not explosive demand growth.
- Product teams and formulators will navigate a regulatory environment that is increasingly active, with substitution and classification debates influencing permissible uses and labeling.
- M&A and growth investors should note a moderately concentrated supplier base that amplifies the strategic value of scale and regulatory-compliance credentials.
Market trajectory at a glance
The zinc pyrithione market demonstrated resilience across the 2020–2025 historical window, absorbing episodic demand shocks and cost pressures before reaching its 2025 level. Looking forward, our baseline projection assumes compound annual growth of 3.75% through 2032, culminating in a materially higher market size at the end of the forecast period under the central scenario. The pace and shape of that growth are sensitive to three levers: regulatory outcomes in key jurisdictions, input-cost cycles (notably energy and logistics), and adoption shifts in end-market formulations.
Zinc Pyrithione Market
Regulatory and compliance dynamics
2024–2026 has been a defining period for ZPT regulation in Europe and elsewhere. Notably, the European Chemicals Agency (ECHA) moved regulatory needles through a public consultation and classification actions addressing pyrithione zinc under biocidal regulation and REACH processes. These developments have elevated uncertainty around permitted biocidal product types and substitution/derogation conditions—an uncertainty that embeds risk premiums into supplier evaluations and product development timelines.
Zinc Pyrithione Market
At the same time, targeted regulatory recognitions continue to create niche advantages: for example, one supplier maintains an active notification for food-contact use in the United States, an asset that can open specific industrial and specialty channels. Such asymmetries—where compliance status is both a barrier and a differentiator—are central to our supplier scorecards and acquisition prioritization frameworks.
Cost, pricing and input-risk signals
Raw-material and producer-price monitoring in early 2026 signaled upward pressure: producer-price indices and quarterly price indices showed increases driven by elevated logistics and energy costs. These cost impulses are uneven across the value chain and geographies, creating windows of margin squeeze for low-differentiation suppliers while advantaging integrated producers or those with long-term feedstock contracts. Our practical playbooks translate these signals into six procurement levers—from hedging and blended sourcing to contract redesign and collaborative inventory management—that purchasing teams should execute in 2026 to protect margins and ensure supply continuity.
Competitive landscape — what to watch
The ZPT vendor landscape is moderately concentrated (CR3 ~68.5%, CR5 ~76.2%), creating oligopolistic dynamics in some channels and meaningful bargaining power for top-tier suppliers. Our analysis focuses on capability clusters and strategic postures among the leading and second-tier providers:
- Lonza Group Ltd. (Basel, Switzerland) — A specialty-chemicals supplier that leverages technical-services capability and brand-level partnerships. Recent collaboration with a major personal-care brand to develop a sustainable hair-care range underscores Lonza’s emphasis on co-development and margin-accretive, application-led growth.
- Sanitized AG (Altenrhein, Switzerland) — Focused on antimicrobial technologies across textiles, plastics, and preservation. Sanitized’s strengths are application engineering and cross-material integration—valuable where formulators demand multi-substrate efficacy.
- Thor GmbH (Cologne, Germany) — A biocide specialist with regulatory credentials, including an active FDA food-contact substance notification for ZPT. That notification is an explicit commercial differentiator for food-processing and certain industrial end-users.
- Jubilant Lifesciences Ltd. (Noida, India) — A global supplier for both rinse-off and leave-on personal-care formulations; scale and solution-formulation capabilities make it a logical partner for CPG companies seeking cost-efficient supply chains.
- China-based producers (multiple) — A cluster of manufacturers supplying cosmetic-grade ZPT suspensions and solutions for the personal-care market. These firms compete primarily on cost and export compliance; several have expanded capacity to serve regional demand surges.
Recent industry moves further illustrate tactical dynamics: a major BASF product launch in 2025 highlighted formulation performance innovation; capacity expansion announcements from Asian producers in 2025 responded to regional demand growth; and a global reagents supplier updated safety documentation in late 2025—each of these events reshapes supplier selection criteria and compliance checklists in near real-time.
Strategic implications by function
- R&D and Formulation: Prioritize validated substitutions and robust preservative strategies to reduce regulatory single-point exposure. Pre-competitive collaboration with suppliers that offer co-development and testing infrastructure accelerates time-to-market.
- Procurement: Move from spot buying to blended-source contracts; incorporate clauses for regulatory-event pass-through, and structure inventory buffers tied to supplier compliance status.
- Commercial and Brand: Use product claims backed by supplier documentation to preserve trust. Where claims touch on antimicrobial efficacy or environmental positioning, ensure upstream compliance certificates are contractually mandated.
- M&A and Corporate Development: Target assets that combine regulatory approvals with application engineering capabilities. Given the CR3/CR5 concentration, bolt-on acquisitions can deliver immediate channel access and price-setting power.
Report contents — what the full study delivers
Our PW Consulting report is designed as an operational decision-support tool. It includes:
- Demand forecasting and scenario trees for 2026–2032, with upside/downside pathways tied to regulatory outcomes and price shocks.
- Price-index tracking and cost-to-serve models that translate input-price moves into P&L sensitivities for different commercial models.
- Supplier scorecards and a compliance matrix that combine regulatory standing, capacity, technology capability, and commercial terms.
- A go-to-market playbook for both incumbent suppliers and new entrants: channel segmentation, value-prop templates, and pricing playbooks.
- Procurement playbook with contract language examples, hedging options, and supplier governance models to manage disruption risk into 2027.
- M&A screening: a prioritized list of target archetypes, valuation multiples observed in adjacent specialty-chemicals transactions, and integration checklists focused on regulatory harmonization.
- A regulatory-impact register and timeline that maps potential ECHA/REACH/BPR outcomes against commercialization windows for different product types.
How to use this intelligence in 90 days
- Re-run product pipelines to identify formulations exposed to ZPT regulatory constraints and prioritize reformulation projects with the highest commercial upside.
- Engage top-quartile suppliers to negotiate capacity rights or tolling arrangements tied to regulatory milestones; our report includes a negotiation playbook and benchmark terms.
- Integrate price-index triggers into procurement contracts to avoid margin erosion from sudden energy or logistics cost spikes; see our model clause recommendations.
- For investors: screen targets against the supplier scorecard and CR3/CR5 concentration metrics to identify consolidation opportunities that deliver rapid market share accretion.
Risk matrix — what keeps us awake
The principal risks that can materially alter the outlook are:
- Adverse regulatory classifications or restrictive use conditions in major markets that could reduce permitted applications or add compliance costs.
- Persistent input-cost inflation—especially energy and logistics—that compresses margins for non-integrated suppliers.
- Rapid innovation in alternates or substitutes—technical improvements in other actives or preservation systems that could reroute demand.
We translate each risk into tactical mitigations in the full report, assigning probability-adjusted financial impacts and operational action plans.
Closing — the strategic value of the report
For 2026 planning cycles, zinc pyrithione is not a binary play of boom or bust; it is a managed portfolio of regulatory, cost, and application risks that can be actively hedged. The market’s modest CAGR masks important tactical inflection points: regulatory decisions that shift permitted use, supplier capacity moves that reprice tolerances, and product innovation that reshapes demand elasticity.
Our PW Consulting Zinc Pyrithione Market study equips executives with the analytical scaffolding and operational tools to convert these inflection points into competitive advantage—without exposing the proprietary segmentation that buyers and acquirers will rely on when they access the full dataset. For firms making sourcing, product, or M&A choices in 2026, the report is a pragmatic bridge between high-level market direction and executable operational plans.
Next step
Access the full report to review detailed scenario models, supplier scorecards, and the procurement playbook. The public synopsis above demonstrates our approach and conclusions while reserving the granular segmentation and actionable targets for the report itself—precisely the intelligence you will need to set strategy for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Zinc Pyrithione Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


