



PW Consulting: X-ray Tube Market to Reach USD 4,614M by 2032 at 4.76% CAGR

X-ray Tube Market 2026: Strategic Imperatives from PW Consulting’s Market Intelligence
As organizations plan capital allocation, supply-chain hedging, and product strategy for 2026, the X-ray tube market—an essential but often underappreciated node in diagnostic imaging, industrial inspection, and analytical instrumentation—demands a different level of attention. Our new PW Consulting X-ray Tube Market study (base year 2025) synthesizes six years of historical performance (2020–2025) with a forward-looking forecast covering 2026–2032. The headline: the market expands from roughly USD 3.35 billion in 2025, tracking to an approximately USD 4.61 billion opportunity by 2032 at a forecast CAGR of about 4.76% (USD Million basis). This brief is designed as a strategic “preview”—to demonstrate the analytic depth we deliver while guiding decision-makers to the full intelligence set for granular transaction-level insights.
X-ray Tube Market
Why this market matters for 2026 decision cycles
-
Multiplier effect on capital planning: X-ray tubes are a high-value, recurring component within a bigger capital equipment purchase cycle. Changes in tube pricing, lead times, and reliability materially impact total cost of ownership for imaging fleets—altering fleet refresh cadence, spare-parts inventories, and service contracts.
X-ray Tube Market -
Aftermarket and remanufacturing as margin levers: The aftermarket—replacement tubes, remanufactured units, and repair services—creates differentiated revenue streams with faster payback and lower R&D intensity than new OEM platforms. Firms that capture aftermarket services increase lifetime customer value and buffer OEM cyclicality.
X-ray Tube Market -
Concentration and competitive positioning: The market displays meaningful concentration at the top—our CR3 and CR5 metrics indicate that the leading manufacturers capture a dominant share of industry revenue. This structure creates scale advantages in production, certification, and distribution, but also leaves tactical openings for agile specialists in niche segments (e.g., microfocus tubes, dental-specific solutions, or high-duty industrial tubes).
-
Regulatory and supply volatility: Regulatory obligations and materials constraints (notably tungsten supply and semiconductor component pressures) change both cost and time-to-market. Firms that integrate regulatory readiness and materials risk into 2026 project plans will avoid costly program delays and margin erosion.
Market trajectory: practical takeaways for 2026 planning
Our topline sizing shows a steady recovery and expansion post the 2020–2021 period, with the market expanding into the mid-2020s and continuing to grow at a mid-single-digit compound annual rate through 2032. For CFOs and corporate strategists, that trajectory implies three practical actions:
-
Reassess inventory and service parts policy. With growth steady but supply-side intermittency likely, moving from a pure Just-In-Time model to a hybrid inventory strategy for critical tube types reduces downtime risk for high-utilization systems.
-
Prioritize partnerships over point-sourcing. Given concentration among top vendors, strategic supplier relationships—longer JIT contracts, co-development agreements for high-reliability tubes, or exclusive aftermarket distributions—deliver outsized risk mitigation and access to priority manufacturing slots.
-
Re-evaluate pricing and cost models. Material and semiconductor cost unpredictability requires dynamic pricing levers and contractual clauses (e.g., material escalation, lead-time penalties, and shared-savings clauses for remanufacturing) to protect margins.
Segmentation and niches: where to focus without giving away the farm
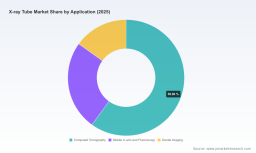
The full PW study presents detailed segmentation by region, product type (e.g., rotating vs. stationary anode), and application (computed tomography, fluoroscopy/C-arm, dental, industrial, and analytical uses). Rather than disclosing granular split percentages here, the strategic implications are:
-
Product-type strategy must be matched to service model. Rotating-anode technologies enable high-duty clinical CT and angiography platforms, demanding investment in thermal management, QC protocols, and OEM certification pathways. Stationary anode solutions remain attractive for lower-throughput modalities and cost-sensitive replacement markets.
-
Application-led roadmaps unlock differentiated road-to-market routes. CT replacement cycles and industrial inspection programs follow different procurement rhythms—sales, warranty structuring, and regulatory documentation should be tailored accordingly.
-
Regional GTM nuance is critical. While demand is global, market-entry and scale playbooks differ by regulatory regime, reimbursement linkage, and distribution structures. Our granular regional analysis in the report supports tailored M&A and partnership scouting in high-opportunity corridors.
Competitive landscape—what the leading firms are doing
Our competitive analysis profiles global incumbents and specialized suppliers, mapping product portfolios, OEM relationships, aftermarket presence, and recent strategic moves. A selection of firms we scrutinize (profiles included in the report) illustrates the range of strategic postures in the market:
-
IAE (X-Ray America) — Cormano, Italy / https://www.x-rayamerica.com/ — A leading independent manufacturer of rotating-anode tubes, with a breadth of replacement models and deep OEM supplier relationships. Recent developments include expanded replacement catalog availability and regulatory certifications that strengthen its factory-to-field supply proposition.
-
Micro X-Ray — United States / https://microxray.com/ — Specializes in microfocus and mini-focus sealed tubes and packaged solutions for CT and specialized imaging. Their product design orientation makes them a natural partner for niche OEMs and R&D-driven applications.
-
Ray-Pac — United States / https://ray-pac.com/ — Focused on domestic manufacture and remanufacturing, Ray-Pac serves the replacement and repair market with speed-to-service advantages in the U.S. market.
-
Malvern Panalytical — Eindhoven, Netherlands / https://www.malvernpanalytical.com/ — With a century-long tube manufacturing lineage, this firm concentrates on high-power analytical tubes for XRF, XRD, and nondestructive testing—segments where reliability and measurement precision drive premium pricing.
-
Comet Group — Germany / https://xray.comet.tech/ — A leader in industrial and microfocus tubes for NDT and security; their engineering focus on high-performance focal spots and dual-filament designs reduces downtime in demanding production inspection contexts.
Key recent moves we've tracked (May 2026) demonstrate active portfolio and capability enhancements across the value chain: expanded replacement inventories with same-day U.S. shipping, case-study releases highlighting durability and dual-focal-spot performance, and timely regulatory certification updates that unlock new procurement pathways in core markets. These tactics—catalog depth, demonstrable field reliability, and regulatory hygiene—are recurring success factors in our competitive benchmarking.
Regulatory, reimbursement, and supply-chain dynamics to monitor in 2026
-
Regulation: X-ray tubes and assemblies are regulated as medical devices in many markets (Class II in the U.S.), requiring 510(k) pathways, IEC 60601 and related ISO compliance, and ongoing reporting obligations under radiological health regulations. Firms that front-load compliance into product roadmaps reduce time-to-market risk and transaction friction in procurement.
-
Reimbursement: There are no new diagnostic procedure codes specifically for tubes; reimbursement drivers remain linked to the imaging procedure. Manufacturers and service providers should therefore price and market against the economics of the entire diagnostic episode, not merely the tube unit cost.
-
Material and component risk: Tungsten market variability and semiconductor shortages continue to influence lead times and unit cost. Our supply-chain scenario analysis provides mitigation playbooks—dual sourcing, strategic inventory, and material-indexed contracts—that are pragmatic for 2026 execution.
What the full PW report delivers (high-level)
-
Market sizing and 2026–2032 forecasts built on transparent assumptions and sensitivity scenarios.
-
Fine-grained segmentation by region, product type, and application—plus dynamic demand drivers that explain growth pockets and substitution risks.
-
Comprehensive competitive benchmarking (CR3/CR5 analysis, product maps, channel footprints, and capability heatmaps).
-
Regulatory and reimbursement matrices that operationalize compliance tasks across major markets.
-
Supply-chain and materials risk assessments with tactical mitigation steps for procurement and manufacturing leaders.
-
Commercial playbooks: pricing frameworks, service-contract design, aftermarket capture strategies, and field-service optimization.
-
M&A and partnership scouting lists with transaction rationale—target profiles and indicative valuation drivers based on our proprietary multiples model.
-
Actionable dashboards and Excel workbooks that allow scenario modeling for capex, service investments, and product-line rationalization.
How to use this intelligence in your 2026 planning cycle
Executives should treat the PW X-ray Tube Market study as both a strategic compass and an operations manual. Use the study to:
-
Prioritize investment: deploy R&D and capital selectively into the tube technologies and application segments where projected growth and margin expansion align with your organizational capabilities.
-
De-risk supply: implement the short list of supply-chain moves we prescribe—dual sourcing, safety stock levels for critical tube categories, and passive hedging for tungsten exposure.
-
Reconfigure commercial models: test aftermarket-first go-to-market pilots for replacement and remanufactured tubes to accelerate cash recovery and shorten sales cycles.
-
Inform M&A: apply our target filters to identify tuck-in candidates that expand aftermarket reach, add complementary tube technologies, or accelerate entry into industrial inspection niches.
Next steps
This preview is intended to show the narrative arc and practical utility of the full PW Consulting study. For transaction-ready data—detailed segment splits, regional revenue buckets, product-type demand curves, supplier scorecards, and downloadable modeling files—access to the full report is required. PW Consulting clients gain the supporting spreadsheets and scenario models that translate the 4.76% forecast CAGR and multi-year sizing into board-level decisions and procurement execution plans for 2026.
Contact PW Consulting for the full report and a tailored briefing that maps these insights to your strategic priorities, whether that is product portfolio realignment, aftermarket monetization, or M&A screening.
For detailed analysis of this topic, please visit the official page: X-ray Tube Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


