



PW Consulting: Polyamide Hot Melt Adhesives Market to Hit USD 919.3M by 2032 (6.2% CAGR)

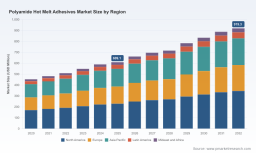
Polyamide Hot Melt Adhesives Market — Strategic Outlook for 2026 Decision-Makers
As companies prepare capital allocation and product strategies for the next planning cycle, our Polyamide Hot Melt Adhesives market study provides a concise, decision-ready synthesis of where the industry stands and how it will evolve. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the report anchors its baseline projection on a 6.2% compound annual growth rate (CAGR). Using 2025 as the base year (figures expressed in USD Million), the market is positioned to expand meaningfully through 2032 under the baseline scenario — a dynamic that transforms how procurement, R&D and commercial organizations should prioritize initiatives in 2026.
Polyamide Hot Melt Adhesives Market
Why this study matters for 2026
-
Timing: 2026 is a pivot year for polyamide hot melt adhesives (PA-HMAs). Material cost dislocations, accelerated regulatory requirements for packaging recyclability, and rising demand from resilient manufacturing pockets (high-temperature bonding, automotive electrification, specialized packaging) create both risk and opportunity windows that require immediate strategic responses.
Polyamide Hot Melt Adhesives Market -
Actionability: The study is designed to convert macro trends into executable moves — from supplier hedging and formulation pivots to targeted capacity investments and M&A screening.
Polyamide Hot Melt Adhesives Market -
Clarity: With a clearly defined baseline (6.2% CAGR) and scenario variants, the report transforms competing narratives about “growth” into quantified planning assumptions that finance and operations teams can integrate into 2026 budgets.
What the report delivers (practical contents)
-
Comprehensive market sizing and a transparent forecasting model covering 2020–2032 (base year 2025; unit: USD Million), calibrated to primary interviews and supply-side shipment data.
-
Segment dynamics and demand drivers with supplier and end-user perspectives (type, application and region-level lenses), presented as strategic implications rather than raw tables—so leadership teams can quickly align on priorities.
-
Supply-chain mapping and raw-material sensitivity analysis, including a supplier matrix for dimer acid and other upstream inputs, plus price-shock scenarios and pass-through timelines.
-
Regulatory and sustainability heatmaps (e.g., packaging recyclability requirements and bio-based formulation standards), showing likely compliance trajectories and where early movers will capture premium positions.
-
Competitive benchmarking and capability profiling for the major players, alongside an M&A target shortlist and valuation frameworks tuned to adhesive industry multiples.
-
Operational playbooks: manufacturing footprint optimization, automation adoption prioritized by ROI, and a practical checklist for scaling new polymerization lines.
-
Investment-grade appendices: supplier scorecards, commercial contract templates, sensitivity tables, and downloadable forecast models for in-house stress-testing.
Macro drivers and near-term dynamics
-
Demand fundamentals remain robust. The baseline forecast reflects steady expansion from post-pandemic recovery dynamics, industrial re-shoring, and ongoing shifts in packaging and automotive assembly practices. The market trajectory through 2032 is consistent with mid-single-digit compound growth under current macro assumptions.
-
Raw-material flows are decisive. The global dimer acid complex — the primary upstream feedstock for many polyamide formulations — is sizable and subject to commodity cycles. Notably, downstream margins have been influenced by a measurable decline in dimer acid production costs after a significant drop in tall oil fatty acid import prices mid-2025. Our modelling quantifies how such feedstock moves propagate to finished-adhesive pricing over 6–12 month windows.
-
Regulatory and sustainability drivers. Packaging recyclability regulations are increasing demand for adhesives that do not compromise recycling streams. Simultaneously, Europe’s tightened sustainability standards are accelerating R&D into bio-based polyamides. These regulatory vectors are not simply compliance headaches — they are shifting value propositions and creating differentiation opportunities in specification-driven segments.
-
Operational cost structure shifts. Greater automation in assembly and adhesive application is changing labor-cost elasticities for adhesive suppliers and converters. This drives a two-track strategy for manufacturers: optimize capital intensity where scale benefits exist, and pursue product sophistication where margin is driven by formulation rather than bulk supply.
Competitive landscape — how to read it
The competitive map is characterized by a mix of global specialty players and regional manufacturers. Leading manufacturers provide branded polyamide solutions optimized for high-temperature bonding, plasticizer resistance, and demanding industrial applications. Strategic moves in 2024–2025—including a notable joint venture between a China-based specialty chemical manufacturer and a European technology partner, plus capacity and polymerization investments by established mid-sized producers—underscore a pattern: strategic partnerships and targeted capacity expansions are the tools firms are using to secure technology and proximity to demand.
-
Market structure: The industry remains relatively fragmented (top concentration levels indicate that the leading firms do not dominate more than a quarter of the market collectively), which creates opportunities for consolidation, specialization, and regional leadership plays.
-
Player archetypes:
-
Global technology leaders — firms offering broad product portfolios and deep application engineering capabilities, focused on industrial bonding and harsh-environment adhesives.
-
Regional specialists — companies concentrating on high-volume local markets and cost-competitive pellet/film production for packaging and conversion industries.
-
Innovation challengers — smaller producers and joint ventures investing in polymerization lines and bio-based formulations aimed at regulatory-driven premium niches.
-
-
Recent strategic signals: Joint ventures to localize technology, production-line additions for focused polymer chemistry, and active trade-show engagement by bio-based product providers all point to an industry placing simultaneous bets on scale, compliance, and sustainability.
Strategic implications for 2026 (what firms should do now)
-
Lock in raw-material flexibility. Establish multi-sourcing arrangements for dimer acid and negotiate index-linked contracts to dampen margin volatility. Scenario modelling in the report shows the breakpoints where feedstock swings materially alter competitive advantage.
-
Prioritize product and application segmentation. Shift portfolio decisions from volume-only thinking to value-focused product placement — emphasize formulations that meet recyclability and bio-based claims where specification premiums are emerging.
-
Invest in selective capacity and polymerization capability. For firms with capital capacity, targeted investments in polymerization lines for polyamide grades generate outsized returns if paired with long-term offtake agreements or secured blue-chip OEM contracts.
-
Operationalize sustainability as a market-entry lever. Certification roadmaps, verified Life Cycle Assessments (LCAs), and traceable bio-content supply chains will accelerate buyer acceptance in regulated markets.
-
Explore M&A and JV pathways. Given fragmentation, M&A is an efficient way to acquire application-engineering expertise or regional footprint; joint ventures remain the preferred mechanism to access local feedstock or manufacturing incentives.
-
Embed regulatory foresight. Use the report’s regulatory heatmaps to prioritize R&D and customer outreach, especially in packaging where compliance timelines are tightening.
Decision toolkit included in the full study
-
Baseline and alternative forecast scenarios (sensitivity to GDP, automotive electrification rates, packaging regulatory adoption, and raw-material price shocks).
-
Raw-material pass-through matrices and supplier risk scores — designed to feed directly into procurement dashboards.
-
Investment case templates for greenfield expansions, polymerization retrofits, and strategic partnerships, complete with payback period ranges under conservative and aggressive demand assumptions.
-
Commercial playbooks for winning specification approvals with global OEMs and packaging converters.
-
M&A scorecards and a prioritized list of acquisition/JV targets supported by high-level valuation ranges and integration risk factors.
How to use this insight in 2026 planning
Translate the report’s baseline and sensitivity outputs into three immediate actions for your 2026 plan:
-
Financial planning: Adopt the report’s 6.2% CAGR baseline across product P&Ls, and test downside scenarios against a two-quarter raw-material shock to confirm covenant and liquidity resilience.
-
Commercial focus: Re-align selling and application engineering to emphasize formulations that address recyclability and temperature resilience; deploy targeted pilots with strategic OEM accounts.
-
Operational moves: Prioritize automation investments in high-labor-intensity lines while planning modular polymerization capacity expansions where the ROI case is validated by secured demand.
Final note — what you’ll find behind the paywall
This article intentionally showcases the study’s strategic depth while withholding the granular segment-by-segment tables, region/application-specific revenue splits, and company-level share figures that underpin our recommendations. The full report contains detailed numeric schedules, interactive forecasting models, regional market maps, and complete company profiles that decision-makers require to finalize capital and commercial commitments in 2026. For teams building 2026 roadmaps, the report is the practical bridge from market narrative to executable plan.
To access the complete dataset, scenario spreadsheets, and M&A shortlist, visit the PW Consulting research release for the Polyamide Hot Melt Adhesives Market. The supporting appendices and modelling files are structured for direct integration into financial planning and procurement systems.
For detailed analysis of this topic, please visit the official page: Polyamide Hot Melt Adhesives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


