



PW Consulting: Wood Interior Doors Market to Reach USD 85,756M by 2032 at 5% CAGR

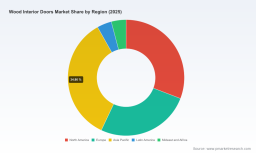
Wood Interior Doors Market 2026: Strategic Preview for Decision-Makers
Executive snapshot
As organizations prepare strategic plans for 2026, the global wood interior doors market presents a blend of predictable growth and operational complexity. Our PW Consulting analysis finds the market reached approximately USD 61,000 Million (base year 2025) after a recovery phase in the early-2020s, and is expected to expand at a 5.0% CAGR over the 2026–2032 forecast period. By the end of the forecast horizon the market is projected to approach roughly USD 85,756 Million. Market concentration remains moderate — the top three suppliers control roughly 35% of value, and the top five roughly 42% — leaving room for both scale-driven incumbents and well-focused challengers.
Wood Interior Doors Market
Why this research matters for 2026 planning
-
Capital allocation: With sustainable mid-single-digit growth and notable volatility in prior years, capital projects must optimize return timing and flexibility. Our research translates market pace into EBITDA sensitivity scenarios for production investments, automation, and SKU rationalization.
Wood Interior Doors Market -
Supply chain timing: Raw material availability and price variability (lumber, engineered cores, specialty veneers) materially affect margins. The report models sourcing stress tests and identifies tactically preferable contract structures for 2026 procurement cycles.
Wood Interior Doors Market -
Product and channel mix: End-market preferences are shifting — particularly towards flush leaves and engineered options — requiring precision in SKU portfolios, inventory velocity metrics, and dealer incentives. We map demand signals to tactical product roadmaps for both renovation and new-construction channels.
-
M&A and partnership targeting: Moderate concentration leaves white space for bolt-on acquisitions and distributor alliances. Our intelligence highlights the value levers for targets (geography, finishing capability, custom lines) and a practical valuation frame aligned to anticipated cash flows.
Market dynamics — what’s shaping 2026 outcomes
The market’s trajectory is governed by three interlocking dynamics: demand-side composition, supply-side cost and capability, and regulatory/standards signals that affect specification behaviour.
-
Demand composition: Residential renovation remains the backbone of volume, while non-residential sectors (office reconfiguration, hospitality refurbishment) are resurging selectively. Customers are demanding a balance of cost-effectiveness and perceived quality — driving growth in engineered and hybrid wood solutions that replicate solid wood aesthetics at lower price and logistical complexity.
-
Cost and input pressures: Lumber cycles and engineered core materials have driven wide retail price bands — from low-cost hollow-core offerings to premium custom solid wood pieces. Our scenarios show margin sensitivity to +/-10–15% swings in core material pricing, underscoring the need for hedging, longer-term supplier agreements, and material substitution strategies in 2026.
-
Standards and specification trends: Industry studies and association data point to a modest shift toward flush door leaves and architectural-grade specifications in some segments. Regulators and industry bodies continue to influence procurement language, especially for fire, acoustic and performance attributes — affecting manufacturers’ testing, certification and product roadmaps.
Competitive landscape: capabilities and strategic postures
The competitive field blends large multi-national suppliers, regional specialists and distributor-platforms. Each archetype demands a different strategic response depending on your role — incumbent, challenger, or capital investor.
-
JELD-WEN (Charlotte, NC) : A global manufacturer with portfolio breadth spanning engineered veneers, flush and composite cores. Strengths lie in scale, channel access and standardized product lines suited to both residential and commercial projects. Strategic issues for rivals: JELD‑WEN pushes distribution economics and national specification relationships.
-
DSA Doors (Raleigh, NC) : Nimble, custom-focused producer emphasizing premium solid wood collections and configurable offerings. Recent catalog expansions and trade-show engagement highlight a go-to-market that leans on design differentiation and dealer intimacy. For larger players, DSA represents the premium niche anchor and a potential bolt-on for companies seeking custom capability.
-
Milgard Windows & Doors (Tacoma, WA) : Embedded in broader fenestration businesses, Milgard integrates interior door offerings with window and exterior door solutions — enabling cross-sell in renovation and new-build channels. Recent facility investments signal a push on innovation and product launches that could accelerate product lifecycle velocity in 2026.
-
Cleary Wholesale : Distributor and stocking platform with deep inventory plays and prehung deployment expertise. Distribution hubs such as Cleary exert strong influence on lead times and SKU rationalization for builders and contractors; partnerships or exclusive SKUs with such wholesalers can materially shorten customer acquisition timelines.
-
Hume Doors & Timber : Specialist in moisture-resistant engineered wooden doors for challenging environments. Their focus underscores the importance of application-targeted product lines — an approach that controls pricing power in niche micro-segments like coastal and high-humidity residential builds.
Recent industry movements to watch
-
Catalog and product refresh cycles are accelerating among custom door makers; expanded collections improve cross-sell but increase SKU management demands.
-
Facility and capacity investments by fenestration players indicate a trend to integrate door/window portfolios and leverage plant modernization to introduce new series and improve margins.
-
Association studies and market reports published in 2025 continue to influence procurement language — notably around architectural interior doors — which filters into specification and tender behaviour in 2026.
-
Price dispersion across core categories remains wide; the retail bands for hollow-core, solid-core and custom solid wood create both margin opportunity and replacement risk for OEMs and distributors.
What PW Consulting’s report delivers — practical, implementable outputs
Our full study is built to inform board-level decisions and operational playbooks alike. Key deliverables include:
-
Macro outlook model: validated historicals (2020–2025), base year metrics (2025) and scenario-driven forecasts for 2026–2032 at a global level.
-
Go-to-market frameworks: channel prioritization matrices, SKU rationalization tools, pricing elasticity benchmarks, and distributor negotiation playbooks tailored to door-specific logistics and finishing constraints.
-
Supply chain resilience playbook: supplier segmentation, contract templates, raw material hedging options and nearshoring analyses aligned to 2026 procurement cycles.
-
Competitive heatmaps and capability diagnostics: factory footprints, customization depth, warranty exposure and adjacent product integration opportunities (windows, exterior doors, millwork).
-
M&A and partnership roadmap: target profiles, valuation multiples aligned to market concentration realities, and integration checklists to preserve margin and design IP.
-
Regulatory and standards tracker: how specification shifts — including the modest move toward flush door leaves observed in recent association studies — can alter demand composition and product development priorities.
How to apply this intelligence in your 2026 planning cycle
-
Prioritize short-cycle wins: Trim underperforming SKUs, negotiate volume-based supply agreements for core inputs, and redeploy working capital into high-velocity finishes and prefabrication capabilities.
-
Invest selectively in modular automation: Target processes with highest labor intensity and rework exposure (finishing, prehang assembly). Payback windows are shortest where SKU standardization is feasible without sacrificing key customer choices.
-
Differentiate by application: Develop clear product plays for moisture-sensitive environments, high-acoustic specifications, and premium custom segments; avoid one-size-fits-all portfolios that yield margin compression.
-
Design distributor economics: Use data-driven incentives for stocking and co-marketing with wholesale partners to secure lead times and prime shelf positions in renovation channels.
-
Embed scenario planning: Use the report’s forecast sensitivity scenarios to stress-test capex, pricing and market-entry timing under alternative raw material and demand shocks.
Trailer and next steps
This preview outlines structural forces, competitor stances, and the strategic levers that will determine winners in 2026. To preserve the tactical edge for clients and partners, the full report contains granular segmentation by region, type and application, detailed SKU-level elasticity matrices, and downloadable financial models — data intentionally reserved for the full publication. For teams ready to convert insight into action, the full dataset and tailored advisory sessions are available through our report portal.
PW Consulting stands ready to convert this market intelligence into a prioritized 90-day action plan, bespoke M&A diligence, or a supply chain redesign tailored to your operating model. Contact our industry desk to schedule a briefing and receive the full segmentation data and scenario models that underpin the analysis summarized here.
For detailed analysis of this topic, please visit the official page: Wood Interior Doors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


