



PW Consulting: Modular Grippers Market Poised for 5.2% CAGR Through 2032

Modular Grippers Market — Strategic Preview for 2026 Decision-Makers
As lead industry analyst at PW Consulting, I present a focused intelligence brief that positions our full Modular Grippers Market study as an operative planning tool for executives preparing 2026 capital, product and M&A decisions. This piece is a “trailer” — it summarizes the market trajectory, strategic inflection points and actionable lines of inquiry that must shape boardroom choices this year, while reserving the granular segment-level schedules and proprietary vendor scoring for the full report.
Modular Grippers Market
Market trajectory: what the numbers tell us
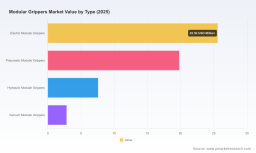
The modular grippers market has moved from early industrial uptake to a phase of steady commercialization. Using 2025 as the base year, the market expanded from approximately USD 45.3 Million in 2020 to USD 55.8 Million in 2025. Our modelling projects a continuation of that growth through the forecast horizon, reaching roughly USD 79.8 Million by 2032. That progression implies a compound annual growth rate in the mid-single digits (around 5.2%) — a profile consistent with a technology-infused component market that is maturing but still responsive to automation cycles, materials innovation and open-architecture system adoption.
Modular Grippers Market
Two complementary market structure signals are worth flagging for strategic clarity. First, concentration metrics show that the market is neither a tight oligopoly nor wholly fragmented — top-three firms do not control the majority of value, and the top-five together still leave substantial share to mid-tier specialists and regional players. Second, recent product and system introductions indicate that vendors are competing as much on software-enabled services, energy efficiency and configurability as on traditional mechanical specifications.
Modular Grippers Market
Why this matters for 2026 decisions
- CapEx and automation roadmaps: With steady growth but meaningful variation across applications, procurement teams must balance selectivity and flexibility. Investing in modular grippers today is not a one-off — it should be part of a platform strategy that prioritizes quick-change tooling, standardized interfaces (mechanical and electrical) and scalable control logic to protect future upgrades.
- Product and R&D prioritization: Innovations that reduce operating power, improve sensor integration and support soft-touch handling are the high-probability winners. Energy-optimized electric and hybrid grippers that operate in the low‑watt range are lowering TCO, making electrification a defensible R&D bet.
- M&A and partnerships: The mid-tier presence in the landscape creates opportunities to bolt on niche capabilities — soft-material fingertips, container-unloading modules, or cloud-based predictive maintenance suites — rather than pursuing broad horizontal consolidation alone.
- Supply chain and compliance: Sourcing strategies must incorporate evolving hygiene and food-grade standards as well as standardization requirements (ISO 9001/14001/45001); compliance failures now create integration frictions for global OEMs.
Report highlights: what the full study delivers
The full PW Consulting Modular Grippers Market report is structured to move quickly from insight to implementation. Key practical assets included are:
- Market sizing and trend maps (historical 2020–2025 and forward projections 2026–2032) with scenario variants tied to raw material volatility and adoption curves.
- Segmentation frameworks (by technology family, by functional configuration, and by application cluster) that identify where premium pricing and margin expansion are achievable. Note: selective segment metrics are illustrative in this preview; detailed split tables and elasticities are available in the complete report.
- Supply chain and procurement playbooks — bill-of-material risk matrices, recommended dual-sourcing approaches, and negotiation levers that reflect certification and compliance constraints.
- Vendor scorecards and decision matrices — an evidence-based framework for OEMs and system integrators to qualify suppliers on interface standards, software APIs, energy performance and aftermarket support.
- Case studies and ROI calculators — validated field deployments showing payback pathways under differing labor and throughput scenarios, enabling site-level capex prioritization.
- Regulatory and materials appendix — practical checklists for food, pharma and cleanroom environments, and guidance on selecting elastomers, silicones and hybrid materials for durability and hygiene.
- Technology roadmaps and scenario planning — mapping likely technology inflection points through 2032 and their consequences for prices, margins and lifecycle support.
Competitive landscape: positioning the key players
The market is populated by specialist OEMs, robotics-focused entrants and automation conglomerates. Our competitive analysis synthesizes public product developments, strategic moves and capability adjacencies to show where each player is investing and how they are likely to compete over the next 18–36 months:
- GIMATIC (Italy) — Strong in electric and pneumatic grippers and end-of-arm tooling (EOAT). Recent product evolution emphasizes higher force density in compact packages, targeting spaces where footprint and force matter.
- Zimmer Group (Germany) — A diversified portfolio across pneumatic, intelligent and electric modules. Their strategic push into cloud analytics and remote monitoring points to an attempt to move up the value chain from components to operational services and predictive maintenance.
- OnRobot (Denmark) — A leader in collaborative robot (cobot) grippers and quick-change integration. Their focus remains on easy-to-deploy, modular solutions that minimize integration time for system integrators.
- DESTACO (United States) — Platform capabilities in teachable electric grippers and sensors show intent to win applications where adaptive force and speed control translate into lower error rates and higher throughput.
- SCHUNK and Festo (Germany) — Both bring broad mechatronics portfolios and strong channel coverage. Festo’s bionic systems and SCHUNK’s sealed and collaborative grippers indicate parallel strategies: industrial-grade performance plus function-rich automation modules.
- Parker Hannifin and WEISS ROBOTICS (United States/Germany) — Positioning is complementary: Parker’s traditional strength in pneumatics and machine tools versus WEISS’s servo-electric and smart pneumatic offerings for precision assembly and life sciences.
- Copal Handling Systems and SoftGripping (Netherlands/Germany) — Niche innovators focusing on modular system integrations (palletizing, container unloading) and soft-material handling respectively. These players are attractive targets for OEMs seeking differentiated end-of-line capabilities or gentleness in handling fragile goods.
Recent product and partnership moves underscore the market’s thrust: compact high-force pneumatic evolutions, modular palletizers that integrate grippers into end-of-line automation, teachable electric grippers, and cloud partnerships enabling predictive maintenance. These developments are symptomatic of a market shifting from component sales to solution-led commercial models.
Market dynamics and risk map
- Materials and sourcing: Elastomers and silicone variants remain central to soft-gripper performance. Manufacturers weighing material choices must balance deformation resilience with hygiene certification timelines.
- Regulation and standards: Updated hygiene standards in Europe and cross-industry certification expectations are increasing time-to-deploy unless certification is pre-baked into product design.
- Energy and efficiency: The push toward electric and hybrid solutions is materially lowering operating power per unit — a competitive differentiator for high-duty cycle lines.
- Labor arbitrage and automation economics: Modular grippers are a high-leverage solution for labor-constrained environments; reconfiguration speed can materially reduce manual handling downtime and accelerate line changeovers.
- Concentration and competition risk: With moderate market concentration, pricing pressure from regional specialists and commoditization risk for basic modules are persistent threats to pure-play suppliers.
Practical next steps for executives in 2026
- Run site-level pilots that prioritize tooling interfaces and control-layer standardization — demand vendors demonstrate plug-and-play changeover in live settings.
- Include energy-performance and software support clauses in procurement contracts to capture TCO benefits over hardware-only bids.
- Target bolt-on acquisitions for fast access to soft-grip technologies or end-of-line integration competencies rather than broad horizontal consolidation.
- Require supplier roadmaps and certification evidence up front; make compliance and lifecycle support material to commercial scoring.
- Adopt the report’s ROI models to stress-test capex plans under conservative and accelerated adoption scenarios.
Methodology and credibility
The full PW Consulting study combines primary interviews with OEMs and system integrators, a verified historical datapool (2020–2025), and scenario-based forecasting to 2032. We triangulate public product disclosures, regulatory updates and verified supplier announcements to construct vendor profiles and scorecards. Our base-year is 2025, and our central forecast assumes current regulatory trends and incremental materials innovation continue without major supply shocks.
How to get the full intelligence
This preview outlines the strategic contours you must factor into 2026 planning. If your objectives include procurement scorecards, fixed-site ROI calculators, detailed segment splits and vendor-ranking spreadsheets, the full report and supporting datasets provide those deliverables — plus a proprietary vendor short-listing tool that links technical KPIs to commercial outcomes. Contact PW Consulting to license the complete Modular Grippers Market report and receive a tailored executive briefing that maps our findings directly to your plant footprints, automation timelines and 3-year investment plans.
For detailed analysis of this topic, please visit the official page: Modular Grippers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


