



GPR Market to Reach USD 400M in 2025, Poised for 7.5% CAGR (2026–2032) — PW Consulting Insight

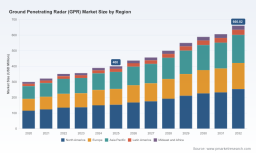
Ground Penetrating Radar (GPR) Market — 2026 Strategic Preview for Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused preview of our full Ground Penetrating Radar (GPR) Market study — a practical intelligence product designed to inform capital allocation, product strategy, and commercial execution in 2026. Grounded in a clear base year (2025) and a forward-looking forecast window (2026–2032), this preview synthesizes the top-line growth trajectory, competitive dynamics, technology inflection points, and the decision-ready frameworks executives will need this year.
Ground Penetrating Radar (GPR) Market
Top-line framing: growth trajectory and market structure
The GPR market reached an estimated USD 400 million in 2025 and is projected to expand through the 2026–2032 forecast period at a compound annual growth rate (CAGR) of approximately 7.5%, reaching a materially larger industry size by 2032. This pace reflects a steady commercialisation of advanced hardware, broader adoption of high-resolution survey workflows across infrastructure and utilities, and accelerating uptake of software and AI-enabled processing layers that increase field productivity and drive recurring revenue opportunities.
Ground Penetrating Radar (GPR) Market
Market concentration is meaningful: the top three suppliers control a clear majority of industry revenue, and the top five firms together command an even larger share. For strategy teams, that structure implies both visible acquisition targets and the need for focused differentiation in product, software, and service offerings.
Ground Penetrating Radar (GPR) Market
Why this study matters for 2026 decision cycles
- Timing: 2026 is a pivotal year for procurement and product roadmaps — budgets for multi-year infrastructure programmes and asset-replacement cycles are being committed now. Our study aligns with these decision gates, translating industry momentum into executable options.
- Risk mitigation: the market’s steady growth masks pockets of supply-side volatility (components, testing capacity, certification timelines). We provide scenario-based impact runs that let procurement and finance teams stress-test outcomes under different supply and regulatory paths.
- Revenue capture: higher-margin revenue pools are shifting from one-off hardware sales to bundled software, cloud processing, and data-as-a-service. The report quantifies commercial levers and go-to-market plays to accelerate this mix shift without exposing confidential segment granularity in this preview.
Key growth drivers and demand signals
- Infrastructure renewal and urban utility programmes: governments and agencies prioritising asset mapping and subsurface risk reduction are creating recurring demand for reliable, high-throughput GPR solutions.
- Technology convergence: integrations with positioning (GNSS), LiDAR, and high-resolution imaging workflows increase the value of GPR outputs in BIM and digital-twin initiatives — a structural change that supports premium pricing for integrated solutions.
- Software and AI: advances in automated target recognition, signal denoising, and 3D reconstruction are reducing operator skill barriers and accelerating adoption among construction, transport, and remediation users.
- Specialised security and defence applications: vehicle-mounted and ruggedised systems are finding steady demand where rapid standoff detection and cleared-area verification are mission critical.
Technology and product evolution
Operators face a technology choice matrix that balances depth of penetration, resolution, survey speed, and operational ergonomics. Our full study maps the trade-offs across product families and identifies where incremental R&D investment produces disproportionate commercial outcomes (for example, software-driven enhancements that improve effective survey throughput by 20–40%). We also profile pathways for hybrid solutions that combine cart-based, handheld, and vehicle-mounted modalities into single contract offerings — an increasingly common seller strategy to win multi-site deals.
Competitive landscape — what market leaders are doing
The competitive picture is both consolidating and innovating. A handful of established suppliers maintain leadership through broad product portfolios and strong channel networks; several others compete on specialised capabilities or software differentiation. Notable recent moves worth tracking for 2026 strategies include:
- GSSI (Geophysical Survey Systems, Inc.) — strategic integration initiatives: GSSI has formalised collaboration with a GNSS and mass-data workflow partner to embed GPR into geolocated, large-scale construction workflows. This type of partnership accelerates adoption in infrastructure segments where positional certainty and seamless data pipelines are procurement prerequisites.
- IDS GeoRadar — software and platform intensification: IDS has released successive software and monitoring solutions that emphasise AI-enhanced processing and ongoing site monitoring, signalling a push toward subscription-style revenue and higher lifetime customer value.
- Guideline Geo (MALÅ) — scientific and community engagement: continued participation at major technical conferences reinforces their leadership in 3D mapping and research-oriented applications, sustaining product credibility among institutional buyers.
- Sensors & Software, US Radar, Geometrics, and Chemring — targeted specialization: these firms occupy differentiated niches including archaeology, ruggedised/triple-frequency imaging, integrated geophysical platforms, and explosive hazard detection respectively. Their strategies stress depth over breadth, which can complicate incumbent competition for narrowly defined procurement scopes.
For commercial leaders, the implication is clear: defensible positions will require a mix of product breadth, software-enabled value, and targeted partnerships to win complex, multi-stakeholder procurements.
Regulatory, standards, and operational constraints
- Certification and standards bodies are maturing: leading manufacturers are updating quality and environmental certifications and participating in sector associations that set interoperability and training standards. This trend raises the bar for new entrants and can speed adoption among risk-averse institutional buyers.
- Operator competence and licensing: as automated processing reduces skill barriers, regulators in some jurisdictions are tightening training and operational licensing requirements to ensure quality and public safety.
- Supply-chain and component risk: miniaturised electronics and specialised antenna components remain supply-chain pinch points. Our scenarios model the financial and timeline impacts of component scarcity on both OEMs and systems integrators.
What the full PW Consulting GPR report delivers (practical content)
Our full report is constructed as a decision toolkit for executives, investment committees, and product teams. Highlights include:
- Market model (2020–2032): a transparent, auditable revenue model with top-line forecasts, scenario toggles, and sensitivity analysis calibrated to the 2025 base year.
- Strategic segmentation framework: a commercial taxonomy mapping buyer groups, procurement behaviours, and willingness-to-pay matrices — presented as actionable buyer personas rather than raw numerical splits in this preview.
- Competitive scorecards and playbooks: vendor benchmarking that scores capabilities across hardware, software, service, channel reach, and M&A posture — used to prioritise partnership or acquisition targets.
- Use-case ROI calculators: templates that translate product choice into operating-cost reductions, safety benefits, or project-duration savings for major verticals.
- Go-to-market and pricing playbooks: playbooks for channel partners, government tenders, and enterprise direct sales, including contract structuring to capture software/consumable revenue.
- Regulatory and procurement checklist: an executable list to accelerate approvals and specification alignment for infrastructure projects.
Note: this preview purposefully omits granular segmentation tables and exact numeric splits across regions, product types, and applications; these datasets and the underlying assumptions are available in full on the report page for subscribers and corporate clients.
Strategic recommendations for 2026
- Prioritise software-first product roadmaps: differentiate on processing, AI, and workflow integration rather than hardware-only specifications. Small software investments can unlock recurring revenue and improved customer retention.
- Accelerate partnerships with positioning and BIM platform providers: integrations with GNSS and digital-twin platforms materially increase procurement preference in infrastructure projects.
- Adopt a layered distribution strategy: mix direct enterprise sales for high-value accounts with certified channel programs for routine utility and construction buyers to optimise cost-to-serve.
- Pursue tuck-in acquisitions to close capability gaps: given measurable market concentration among leading vendors, acquisitive moves focused on software, monitoring, or niche sensor capabilities can be fast routes to scaled capability.
- Hedge supply-chain exposure: build dual-source strategies for key components, and model procurement contracts that protect margins under short-term component price volatility.
Methodology and data integrity
Our projections are anchored to a 2025 base year and rely on a mix of primary interviews with industry buyers and OEMs, proprietary shipment and pricing surveys, and public disclosures from leading vendors. The forecast period (2026–2032) uses a mix of bottom-up and top-down techniques, cross-validated by PW Consulting’s industry-validated scenarios. The headline CAGR and market size trajectories quoted here are rounded to reflect modelling consensus; the full dataset and scenario toggles are included in the report’s model workbook.
Next steps and how to access the full intelligence
This preview is intended to orient executive teams to the strategic stakes of 2026 and to showcase the practical value of the full PW Consulting GPR Market study. If you are preparing capital plans, R&D roadmaps, partnership evaluations, or M&A screenings this year, the full report provides the necessary quantitative granularity, supplier scorecards, and executable playbooks. Detailed segmentation, vendor-specific market shares, and the complete financial model are available on our report page and via direct inquiry for corporate subscriptions.
Contact our team to request an executive briefing, access the dataset, or commission custom scenario modelling tailored to your organisation’s portfolio.
— PW Consulting, Advanced Strategy & Industry Analysis
For detailed analysis of this topic, please visit the official page: Ground Penetrating Radar (GPR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


