



PW Consulting: Artificial Tears Market to Reach USD 3,310.2M by 2032 at 9.05% CAGR

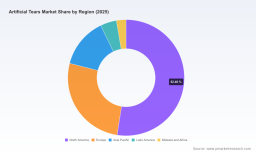
Artificial Tears Market 2026: Strategic Imperatives and Forecast — PW Consulting Insights
As the Artificial Tears market moves from recovery into an era of accelerated reformulation, channel evolution, and heightened regulatory scrutiny, 2026 will be a decisive year for market leaders and challengers alike. PW Consulting’s market model (base year 2025) shows the global artificial tears market expanding from approximately USD 1.82 billion in 2025 to an anticipated USD 3.31 billion by 2032, reflecting a compound annual growth rate (CAGR) of roughly 9.05% over the forecast window. The historical trajectory (2020–2025) underscores steady volumetric and value growth driven by demographic pressure, diagnostic momentum, and product innovation — trends that will inform strategy and capital allocation decisions in 2026.
Artificial Tears Market
Why this research matters for 2026 decision-makers
-
Timing. 2026 is the inflection point between legacy OTC channels and the next wave of preservative-free, value-added formulations. Decisions taken this year on manufacturing, registration, and channel investments will lock in share trajectories for the rest of the decade.
Artificial Tears Market -
Risk management. Recent regulatory events have elevated the cost of quality lapses and misclassification; the commercial impact of a recall or warning letter now runs much deeper than lost sales alone.
Artificial Tears Market -
Capital allocation. With mid-term market value set to nearly double from its 2025 base under our baseline scenario, firms need a prioritized playbook—what to build, buy, or partner—and a clear ROI timeline.
What PW Consulting’s Artificial Tears report delivers (practical scope)
-
Robust market model: five-year historical base (2020–2025) and a seven-year forecast (2026–2032) with scenario outputs (baseline, upside, downside) and sensitivity analyses keyed to regulatory shocks, reimbursement shifts, and raw-material supply disruptions.
-
Commercial playbooks: go-to-market templates for OTC-to-Rx transitions, clinic channel commercialization, e‑commerce rollouts, and private-label partnerships.
-
Regulatory and quality roadmaps: sterility compliance checklists, label strategy matrices, and a recall-readiness playbook tailored for ophthalmic products.
-
Competitive intelligence: strategic profiles, capability maps, pipeline tracking, and M&A target screening across incumbent and emerging players.
-
Reimbursement & evidence toolkit: mapping of reimbursement levers, payer engagement playbooks, and clinical evidence templates tied to diagnostic criteria (e.g., Schirmer testing pathways).
-
Operational diagnostics: manufacturing gap analyses, contract-manufacturing options, and logistics resilience recommendations to mitigate supply-chain and sterility risks.
Market dynamics and growth vectors
-
Demographics and epidemiology. Aging populations and rising prevalence of dry eye disease, combined with chronic screen exposure and contact lens usage, sustain long-term demand for lubricants and therapeutic tear substitutes.
-
Product innovation. Demand is shifting toward preservative-free formulations, longer-retention agents, and vehicle technologies that support dosing frequency reduction—trends that favor firms with formulation R&D and sterile-fill capabilities.
-
Channel evolution. Traditional retail remains important, but prescription-mediated reimbursement and clinic dispensing are growing in influence, altering pricing dynamics and product bundling strategies.
-
Regulatory uplift. Sterility is non-negotiable: ophthalmic products are treated as sterile drug products under FDA standards. OTC pathways that rely on sterility assurance face higher barriers and intensified post-market surveillance.
-
Payer behavior. Medicare and commercial insurers will reimburse artificial tears under defined coding and clinical criteria when prescribed, which elevates the value of physician-directed product adoption supported by diagnostic evidence.
Regulatory shocks and recent industry signals
-
Recall and sterility enforcement. A large-scale recall initiated in March 2026 involving over 3.1 million bottles highlighted the operational and reputational cost of lapses in sterility testing (FDA Official Recall Notice, March 2026). This event has already prompted buyers and distributors to demand higher transparency in supplier QC systems.
-
Misbranding risk. A July 2025 FDA warning letter to a manufacturer for misbranding a sterile lubricant as OTC underscores the regulatory sensitivity around product status and claims in this category (FDA Warning Letter, July 2025).
-
Implication. Companies must re-evaluate label strategies, invest in validated sterilization and cleanroom capacity, and prepare accelerated corrective-action plans to contain downside scenarios.
Competitive landscape — leaders, challengers, and implications
-
Alcon (Fort Worth, Texas) — A portfolio leader with established brands in the artificial tears space. Strengths lie in distribution scale, clinician relationships, and brand equity. Strategic focus for incumbents: defend clinician preference channels and accelerate preservative‑free innovations.
-
AbbVie (North Chicago, Illinois) — Leverages differentiated HydroCell® technology and preservative-free positioning. AbbVie’s advantage is technology-led differentiation that supports justification for clinic adoption and reimbursement conversations.
-
Bausch + Lomb (Bridgewater, New Jersey) — Broad lubricant portfolio and deep channel penetration. Competitive play: bundle therapeutics and diagnostics to create clinic-centric value propositions.
-
Thea Pharma (Jackson, Mississippi) — Niche play with sterile formulations for severe disease and night-time use but faces regulatory exposure from prior warning letters. Strategic emphasis: resolve standing regulatory issues, fortify labeling strategy, and convert specialty use into durable clinic prescriptions.
-
Akorn Consumer Health (Ann Arbor, Michigan) — Known for carboxymethylcellulose-based offerings. Cost and formulary placement are the levers to expand penetration in price-sensitive segments.
-
K.C. Pharmaceuticals (California) — Recent recall events have materially elevated counterparty risk. Near-term strategic priorities should include third‑party QC validation, customer remediation, and transparent communications to restore trust with distributors and clinicians.
-
Market concentration: Our CR3/CR5 analysis shows a moderate concentration profile (top 3 ≈ 37.8%; top 5 ≈ 52.4%), creating room for targeted M&A and niche strategies while limiting the ability of a single incumbent to unilaterally shape price points.
Strategic imperatives for 2026 (what to do, in order)
-
1) Invest in sterility and QA as a competitive moat. Capital allocation to validated sterile filling, environmental monitoring, and third-party audits should be a top 2026 priority. KPI: audit pass rate and time-to-corrective-action.
-
2) Create clinic-aligned value propositions. Build evidence packages (Schirmer-driven endpoints and real-world adherence data) to enable reimbursement conversations and clinic formularies.
-
3) Prioritize preservative-free formulations and dosing convenience. Differentiate on retention time and dosing frequency to win share in premium segments.
-
4) Strengthen supply chain transparency. Adopt serialized lot-tracking and proactive recall simulations to reduce time-to-notice and reputation impact.
-
5) Execute selective M&A and partnerships. Use the moderate concentration landscape to acquire niche technology, expand sterile fill capacity, or secure regional distribution where incumbents are light.
-
6) Embed recall-readiness into commercial contracts. Insist on supplier indemnities, quality SLAs, and joint remediation plans as standard terms.
-
7) Digital patient support. Deploy adherence apps and clinic-to-patient engagement platforms to increase persistence and elevate reimbursement justification.
Scenario planning and trigger-based decision rules
-
Base case. Our baseline models the market growing at roughly 9.05% CAGR from 2026 onward under stable regulatory and supply conditions.
-
Upside. Faster diagnosis adoption, expanded payer coverage for clinic-dispensed products, or a breakthrough vehicle technology can accelerate growth materially—favoring companies that scale manufacturing quickly.
-
Downside. Additional high-profile sterility events or tightened OTC controls could depress demand and compress margins; firms should prepare conservative inventory and recall-cost buffers.
-
Decision rule example. If a supplier audit reveals persistent environmental monitoring failures, trigger immediate dual-sourcing and escalate to a fourth-quarter capital plan to bring sterile-fill in-house.
Why PW Consulting’s report is essential for your 2026 playbook
-
Actionability: the report translates market forecasts into executable roadmaps—contract clauses, CAPEX prioritization, go-to-market timelines, and payer engagement scripts.
-
Proprietary modeling: our baseline and alternative scenarios are built from granular inputs and validated against recent industry shocks, providing stress-tested revenue and margin impacts.
-
Competitive edge: detailed company diagnostics and M&A target screens help buyers and sellers size synergies quickly without committing costly due diligence upfront.
PW Consulting’s Artificial Tears Market study is designed to support board-level strategy sessions, corporate development workstreams, and operational leaders planning 12–36 month initiatives. For access to the full dataset, regional and channel-level segmentation, pricing matrices, and the proprietary company market-share model that underpin our recommendations, visit PW Consulting’s research portal to request the complete report and supporting appendices. The macro trajectory is clear—2026 will separate organizations that treat sterility and clinical evidence as strategic assets from those that view them as compliance costs. Which side will you be on?
For detailed analysis of this topic, please visit the official page: Artificial Tears Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


