



PW Consulting: Chip Antenna Market to Reach USD 5,040M by 2032 at 11.78% CAGR

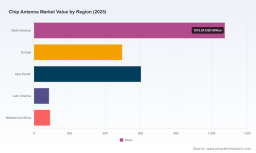
Chip Antenna Market 2026 Strategic Preview — A PW Consulting Perspective for Executive Decision-Making
As companies prepare capital allocations, product roadmaps, and M&A agendas for 2026, chip antennas are shifting from a tactical commodity to a strategic enabler across wireless architectures — from consumer wearables and smart meters to automotive connected systems and industrial IoT. PW Consulting’s latest market study provides a forward-looking compass: the chip antenna market, valued at approximately USD 2,350 Million in the report’s base year (2025), is projected to expand at a compound annual growth rate (CAGR) of 11.78% through the forecast period, reaching roughly USD 5,040 Million by 2032. This preview distills the strategic implications of that trajectory without disclosing the granular splits reserved for the full report, so that executives can act now while preserving incentive to access the complete intelligence set.
Chip Antenna Market
Why 2026 Is a Strategic Inflection Point
-
Technology convergence is accelerating. Next-generation wireless standards (including Wi‑Fi 6/7, UWB, NB‑IoT, and expanding 5G profiles) are increasing the technical complexity of antenna selection, integration and validation. Selection now affects board real estate, RF performance, certification timelines, and time‑to‑market in equal measure.
Chip Antenna Market -
Miniaturization and system integration are creating winners and losers. Design wins increasingly favor suppliers that couple high-frequency performance with manufacturability and supply resilience — not just price per unit.
Chip Antenna Market -
Regulatory and compliance friction has risen. Recent updates to recognized test laboratories and persistent OTA regulatory rules are materially changing validation pathways for vendors and OEMs, with implications for cost, schedule, and supplier selection.
Market Trajectory — What the Numbers Imply for Strategy
The mid‑decade picture is one of robust expansion. From a base of USD 2,350 Million in 2025, the market is on a path to more than double by 2032 at an 11.78% CAGR. Past performance (a steady climb from 2020 through 2025) demonstrates demand resiliency against cyclical headwinds. For decision-makers this means three practical considerations:
-
Volume opportunity is real, but margin compression is a risk for undifferentiated players. Rapid unit growth supports investments in automation and testing only when coupled with product or service differentiation.
-
Time-to-market and certification readiness are value drivers. OEMs that reduce validation friction and shorten integration cycles capture disproportionate share in emerging segments.
-
Supply chain continuity becomes a competitive moat. As volumes rise, supplier capacity, geographic redundancy, and test‑lab access will determine who can sustain growth without sacrificing price or delivery.
Key Market Dynamics Shaping Competitive Advantage
-
Product technology mix — LTCC, dielectric, and hybrid approaches — is evolving. Each approach carries tradeoffs between bandwidth, size, temperature stability and cost. Successful players are those that align material technology to target applications rather than pursuing one-size-fits-all portfolios.
-
Integration trends — embedded antennas and antenna‑in‑package solutions — are shifting the value pool upstream into design collaboration and IP. Antenna suppliers that can offer PCB co‑design services and calibrated simulation libraries shorten OEM design cycles and command premium positioning.
-
Certification & compliance complexity has increased. For example, regulatory developments around recognized test labs and over‑the‑air reception rules affect validation routes and market access timelines. Companies must map these regulatory nodes into product development roadmaps early to avoid costly rework.
-
Consolidation pressure is moderate. Market concentration metrics indicate room for both global leaders and specialized niche players. Strategic M&A activity will favor combinations that bring complementary technologies, packaged solutions, or geographic test‑lab and manufacturing capabilities.
Competitive Landscape — Profiles and Strategic Postures
The market exhibits a mix of large multidisciplinary component manufacturers and specialist antenna houses. Market concentration metrics show that the top three players capture a meaningful but not dominant share, while the top five extend that presence — a structure that favors targeted partnerships and tactical acquisitions.
-
Large global passives and components firms (e.g., established multilayer ceramic and LTCC specialists) leverage scale in materials, fabrication and global distribution. Their playbook focuses on multi‑band, multi‑application portfolios targeting smartphones, automotive, and mainstream IoT.
-
Specialist antenna and embedded‑antenna companies concentrate on system performance, customization and co‑design services for demanding sectors (automotive UWB, industrial IoT, and precision GNSS). Their advantage is high‑value design wins and deep integration with module vendors.
-
Regional and niche players are effective in cost sensitive or regionally regulated segments where local test labs and supply networks matter. These players frequently become acquisition targets once they demonstrate scalable quality and design IP.
Examples of strategic playbooks observed in the market include:
-
R&D-led differentiation (high-frequency, multi‑band LTCC and tuned dielectric solutions);
-
Service-led differentiation (PCB co‑design, integrated testing, and rapid prototype support);
-
Scale-driven cost leadership (vertical integration of materials and high-volume manufacturing);
-
Channel & ecosystem plays (strategic partnerships with module houses and systems integrators to lock-in design wins).
Recent Industry Moves — Signals to Watch
-
Product launches targeting Wi‑Fi 6/7, UWB and NB‑IoT indicate supplier prioritization of next‑generation connectivity segments — an explicit bet on higher-value, higher-performance antenna solutions for premium devices and industrial deployments.
-
Automotive-grade LTCC and AEC‑Q200 qualifications are becoming table stakes for suppliers seeking vehicle platform penetration, signaling that suppliers are investing in reliability and testing infrastructures.
-
Market entrants and established specialists are expanding low-cost and compact ceramic ranges for wearables and smart metering, underscoring a bifurcation between cost-sensitive consumer segments and high-performance industrial/automotive sectors.
Risks and Regulatory Considerations
-
Test-lab recognition and equipment authorization pathways are evolving. The report highlights regulatory datapoints — including recent updates to recognized test laboratories — that materially affect time‑to‑certification. Firms must incorporate regulatory lead times into product roadmaps and procurement timelines.
-
OTA reception rules remain an evergreen compliance consideration where antenna placement and integration choices can trigger regulatory scrutiny and customer dissatisfaction if not managed early.
-
Supply-chain geopolitical risks and raw‑material pressures (ceramic substrates, precious metal pastes) require scenario‑based inventory and sourcing strategies; the cost of getting this wrong increases as unit volumes scale.
Actionable Strategic Recommendations for 2026
-
Segment your portfolio by value profile and go‑to‑market model: Preserve low-cost commodity SKUs for volume channels while cultivating a high-margin design-services funnel for differentiated system wins.
-
Invest in co‑engineering capabilities and test infrastructures: Shorter integration cycles and faster certification will be decisive in winning design-ins in automotive and industrial accounts.
-
Build regulatory intelligence into product planning: Map certification paths and recognized-test-lab requirements for target geographies and prioritize design choices that minimize re‑testing risk.
-
Pursue targeted partnerships and tuck‑ins: Identify niche suppliers with advanced LTCC or antenna‑in‑package IP for bolt‑on acquisitions to rapidly broaden your capabilities.
-
Operationalize a multi‑scenario procurement model: Move from single‑source toward a tiered supplier architecture with regional redundancies and validated alternative test labs to protect launches against lab or capacity bottlenecks.
What PW Consulting’s Full Report Delivers
PW Consulting’s comprehensive study translates market growth and dynamics into operational blueprints. The full report includes:
-
A validated market-sizing model (historical 2020–2025 and forward 2026–2032) with scenario analysis for alternative adoption and pricing environments.
-
Technology and product benchmarking across LTCC, dielectric and embedded approaches, including performance matrices and BOM/PCB impact assessments.
-
Supplier scorecards, capability heatmaps and a transaction‑ready M&A playbook identifying targets, valuation KPIs and integration risks.
-
Regulatory mapping tied to certification timelines, recognized test‑lab pathways and OTA compliance checklists for major markets.
-
Commercial frameworks: pricing elasticity models, channel strategies, and procurement playbooks calibrated to volume and margin objectives.
-
Seven strategic playbooks tailored to product OEMs, module houses, component suppliers, and private equity investors — each with recommended actions for 12–36 month horizons.
Conclusion — From Insight to Execution
The chip antenna market’s compelling top‑line growth masks important inflections that will determine which players scale profitably. By 2026, organizations that combine technology differentiation, rigorous regulatory planning, and resilient supply architectures will capture disproportionate value. PW Consulting’s study equips executives with both the strategic perspective and the operational toolset to translate growth forecasts into executable plans — while preserving the proprietary segmentation and granular datasets that are critical for transaction and procurement decisions. Access to the full report provides the datasets, scoring models and vendor profiles required to move from strategic intent to measured, high‑confidence action.
For detailed analysis of this topic, please visit the official page: Chip Antenna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


