



PW Consulting: Primary Battery Market to hit USD 26.81M by 2032 at 5.4% CAGR

Primary Battery Market — Strategic Preview for 2026 Decision-Making
Executive teaser
As companies prepare strategic plans for 2026, the Primary Battery Market presents a mix of steady expansion, regulatory pressure, and concentrated competitive dynamics that demand disciplined, data-driven responses. PW Consulting’s forthcoming Primary Battery Market study synthesizes a seven-year forecast, competitive heatmaps, and executable playbooks designed to convert market intelligence into near-term advantage. This article previews the study’s strategic implications — demonstrating our analytical depth while deliberately withholding granular segment-level figures to guide you to the full report for operational detail.
Primary Battery Market
Market snapshot (macro view)
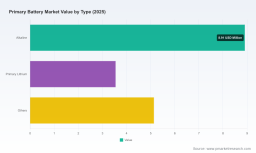
The primary battery market has navigated modest volatility in the early 2020s and is projected to resume steady growth across the 2026–2032 forecast window. Using 2025 as the base year, our topline projection shows a compound annual growth rate (CAGR) of 5.4% through 2032, with the market expanding from the mid-teens (Million USD) in 2025 toward an upper‑twenties (Million USD) level by 2032. This trajectory reflects a balance of steady end-user demand in consumer and industrial channels, pockets of faster growth where high-energy-density chemistries are needed, and the moderating effects of substitution and circular-economy pressures.
Primary Battery Market
Why this matters for 2026 planning
- Investment timing and sizing: With predictable topline growth, 2026 is an inflection year for transitioning from defensive cost management to selective capacity or technology investments. Firms that align capex with the forecasted CAGR can avoid under- or over-capacity while preserving optionality.
- Regulatory compliance as a strategic lever: New rules on waste batteries, recycled-content thresholds, and expanded labeling requirements will reshape product specifications and cost structures. Companies that embed compliance into product development early will convert regulatory burden into differentiation.
- Margin preservation in a concentrated market: The market exhibits material concentration among top players (CR3 ~59%, CR5 ~65%), creating both barriers and opportunities. Incumbents can leverage scale; challengers must pursue niche dominance, channel innovation, or integrated services.
- Supply-chain resilience: Recycled-content rules and recovery verification increase the strategic value of upstream supplier relationships and of investments in traceability systems.
Dynamics shaping the window to 2026
Three overlapping forces will dominate decision agendas in 2026:
Primary Battery Market
- Regulatory acceleration: The European Commission’s mid‑2025 battery rules and 2026 labeling and recycled-content mandates will shift compliance from a regional cost to an operational imperative. Expect procurement, R&D, and quality functions to be mobilized to ensure conformity across markets.
- Channel and use‑case evolution: Consumer electronics remain a core demand engine but growth pockets are emerging where single‑use, high‑reliability chemistries serve medical, IoT, and industrial remote-monitoring applications. Companies must map product-to-use-case economics rather than treating all primary cells as commoditized.
- Structural consolidation and specialization: With the market more concentrated than many suppliers assume, M&A and partnership plays will accelerate around scale, proprietary cell formats (coin, cylindrical, microbutton), and service layers (stewardship, take-back).
Regulatory milestones you cannot ignore (operational implications)
- European Commission: July 4, 2025 — new rules for waste batteries that require verified recycling efficiency and material recovery. Operational implication: design for recyclability and invest in certified recovery reporting.
- GetEnviroPass: August 18, 2025 — mandatory display of the separate-collection symbol. Operational implication: packaging and product artwork updates across SKUs and markets.
- Vermont: January 1, 2026 — producers must participate in approved stewardship plans to sell covered batteries. Operational implication: market-access planning and potential incremental fees or program participation costs.
- EU labeling and recycled content: From January 2026 — consumer-facing labeling now requires manufacture date, weight, and chemical composition; minimums for recycled cobalt, nickel, and lithium apply. Operational implication: supply‑chain tracing, supplier audits, and R&D trade‑offs between performance and recycled-content specifications.
Competitive landscape — what top players are doing
The primary battery competitive set blends global branded names with specialized OEM and industrial suppliers. Key strategic postures in the market include broad consumer branding, professional and industrial product lines, and niche high‑performance coin and primary lithium cells for medical and aerospace use. Highlights from the major players include:
- Energizer Holdings, Inc. (St. Louis, USA): Focused on mainstream alkaline and primary lithium offerings across consumer, industrial, and OEM channels. Plays to brand and retail scale while selectively pushing professional product lines.
- Duracell Inc. (Nashville, USA): Leverages the Duracell brand and a Procell professional line to defend market share in both consumer and industrial segments; pricing and retail partnerships are core levers.
- FDK Corporation (Tokyo, Japan): Strong in coin-type and cylindrical lithium primary cells known for high energy density and low self-discharge — positioned for electronics and precision industrial applications.
- Panasonic Corporation (Osaka, Japan): Offers both lithium and alkaline primary chemistries, competing on product breadth and integration into broader electronics ecosystems.
- GP Batteries International Ltd. (Hong Kong): Competes across alkaline, lithium, and zinc chemistries with an emphasis on cost-competitive consumer gadgets and professional devices in Asia.
- VARTA AG (Ellwangen, Germany): Emphasizes microbutton and primary lithium cells targeted at IoT, medical, and industrial applications where miniaturization and reliability matter.
- Renata SA (Biel, Switzerland): Specialist in coin cells (silver oxide, lithium, zinc-air) for professional and medical use, competing on precision and regulatory compliance for medical devices.
- Maxell Holdings, Ltd. (Tokyo, Japan): Focus on coin-type primary lithium and alkaline batteries for industrial and consumer electronics, often competing through OEM partnerships.
- Ultralife Corporation (Newark, USA): Niche player in non-rechargeable lithium cells and packs for remote, military, and industrial applications — differentiates on ruggedization and lifetime performance.
- Saft Groupe SA (Paris, France): Targets industrial, aerospace, and defense with primary lithium cells where certification and lifecycle performance are critical.
Collectively, these players demonstrate available strategic archetypes: scale-driven consumer brands, performance-focused specialists, and vertically integrated industrial suppliers. The market’s CR3/CR5 concentration metrics underline that scale and distribution matter, but so do niche technical advantages for premium, regulated applications.
What PW Consulting’s Primary Battery Market report delivers (practical content)
Our full study converts macro foresight into operational tools for 2026 action. Components include:
- Topline market model with historical (2020–2025) calibration and a 2026–2032 forecast scenario set (baseline, upside, downside) — enabling capex and revenue sensitivity analysis.
- Regulatory impact assessment mapping new EU and North American rules to product specs, cost buckets, and go-to-market timelines.
- Competitive heatmaps and supplier scorecards that evaluate capability across chemistry, format, certification, channel access, and sustainability readiness.
- Supply‑chain risk and opportunity matrix highlighting raw-material exposure, recyclate availability, and traceability gaps tied to recycled-content compliance.
- Go‑to‑market playbooks tailored for incumbents, challengers, and niche specialists: pricing approaches, channel strategies, and retail/industrial segmentation tactics.
- M&A and partnership screening with target profiles and value-creation hypotheses (technology, capacity, route-to-market), plus an integration checklist focused on compliance and traceability.
- Implementation timelines and a 100‑day sprint template for compliance readiness and product relabeling programs in 2026.
Note: The report purposefully limits public disclosure of granular regional or application-level share data in this preview. Detailed segment-level figures, proprietary scoring matrices, and deal-target lists are available only through the full report portal.
Practical 90–180 day actions for 2026
- Audit product registrations and labeling: Map SKUs against new labeling requirements (manufacture date, weight, chemical composition) and prioritize relabeling where cross-border sales pose noncompliance risk.
- Engage suppliers for recycled-content traceability: Institute supplier questionnaires, chain-of-custody checks, and pilot recycled-material sourcing contracts to de-risk compliance with minimum thresholds.
- Segment portfolio for investment: Classify SKUs by margin, regulatory exposure, and strategic priority; defer commodity investments and accelerate development of high-value, compliance-friendly formats for medical and industrial markets.
- Prepare stewardship and take-back pathways: Evaluate participation in producer responsibility organizations, particularly to enable market access in jurisdictions with stewardship mandates.
- Scenario-plan pricing and promotional elasticity: Model the pass-through of compliance costs under alternative competitive reactions to avoid margin erosion.
Why PW Consulting’s analysis is strategic rather than descriptive
Our approach is designed to translate macro forecasts and regulatory realities into executable decisions. We triangulate industry-reported volumes, proprietary channel checks, and supplier interviews to produce an actionable view that respects commercial sensitivity. The published CR3 and CR5 metrics in the study surface the competitive balance; our supplier scorecards then operationalize what winning looks like by chemistry, format, and regulatory readiness.
Next step — where to get the full intelligence
This preview outlines the strategic contours companies must act upon in 2026. To convert these insights into executable plans — with full segment-level data, detailed company benchmarking, and the proprietary models referenced above — access the complete Primary Battery Market report on our report page. The full dossier contains the precise regional and application splits, detailed cost curves, and downloadable slide decks you will need to brief boards and mobilize cross-functional teams.
PW Consulting stands ready to support scenario workshops, M&A diligence, and compliance implementation sprints informed by the report. Contact our Primary Battery Market team to schedule a briefing and unlock the full dataset and playbooks that will govern smarter 2026 decisions.
For detailed analysis of this topic, please visit the official page: Primary Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


