



PW Consulting: Specialty Optical Fibers Market to Hit USD 3,607.7M by 2032 at 8.6% CAGR

Specialty Optical Fibers Market — Strategic Preview for 2026 Decision-Makers
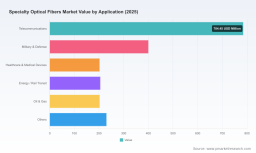
As companies position for the next wave of optical innovation, high-resolution market intelligence is no longer optional — it is a strategic instrument. PW Consulting’s Specialty Optical Fibers Market study (base year 2025, historical 2020–2025, forecast 2026–2032) frames the sector’s commercial trajectory and the tactical choices that will determine winners in 2026 and beyond. The global market reached approximately USD 2,025 million in 2025 and, growing at a compound annual growth rate (CAGR) of 8.6%, is projected to approach roughly USD 3,608 million by 2032. These headline dynamics reflect a mix of accelerating technology adoption, targeted defense and industrial demand, and new product architectures that reshape value chains.
Specialty Optical Fibers Market
Why this study matters for 2026
-
Timing of investment matters: with an 8.6% CAGR over the forecast window, the next 18–24 months will determine competitive scale for manufacturers planning capacity expansion, and they will be decisive for suppliers of test equipment and componentry that must move from lab-prototype volumes to repeatable commercial volumes.
Specialty Optical Fibers Market -
Technology inflection points are strategic breakpoints: hollow-core, multicore/space-division multiplexing (SDM), bend-insensitive single-mode fibers, polarization-maintaining fibers tailored for co-packaged optics, and specialty laser fibers are shifting value from commodity drawing to systems-level integration and characterization.
Specialty Optical Fibers Market -
Standards and testing capacity are gatekeepers to commercialization: the pace of standardization and availability of structured test/inspection equipment will affect time-to-market, particularly for multicore and hollow-core products that require new measurement methods.
Market dynamics shaping 2026 choices
-
Innovation-led demand: Recent product introductions and demonstrations underscore a rapid commercialization cycle. Throughout early-to-mid 2026, Tier-1 and specialist firms unveiled solutions aimed at co-packaged optics, L-band amplification, and terabit-scale multicore transmission — signaling near-term demand both from hyperscale data center architecture shifts and from advanced telecom upgrades.
-
Standards and measurement gaps: ITU-T’s roadmap for SDM (GSTR‑SDM) underscores industry alignment on architectures, but meaningful measurement gaps remain — notably standardized methodologies for cross-talk (XT) in multicore fibers and for differential group delay (DGD)/differential mode delay (DMD) in weakly coupled designs. These gaps drive two adjacent markets: calibration/test equipment and third-party certification services.
-
Sustainability and regulatory pressure: A significant portion of new specialty fiber introductions in recent years have been designed for biodegradability or reduced environmental impact. Procurement and regulatory trends are increasing the premium for materials and processes that meet eco-design criteria, affecting R&D priorities and supplier selection.
-
Defense and mission-critical adoption: Field deployments have demonstrated measurable system-level efficiency gains from fiber-based amplification and advanced fiber subsystems. This translates into durable, premium demand from military and critical-infrastructure programs where lifecycle qualification is a strategic procurement requirement.
-
Concentration and competitive structure: Market concentration metrics indicate a mix of scale players and specialized niche vendors. The top three participants capture a material share but do not dominate the sector, while the top five capture a majority — a structure that rewards both scale (for cost-competitive supply) and specialization (for high-margin, application-specific fibers).
What our report provides (practical, actionable intelligence)
-
Robust top-line sizing and scenario models. We present historical totals, base-year benchmarks (2025), and a point forecast to 2032 with sensitivity runs that stress-test assumptions around hollow-core adoption, multicore deployment rates, and defense procurement cycles.
-
Demand-driver maps by application archetype. The study dissects demand fundamentals for telecommunications, defense, healthcare, transportation/energy, oil & gas and other industrial verticals — highlighting use-case requirements (latency, ruggedization, sterilizability, radiation tolerance) without disclosing proprietary segment-level tables in this preview.
-
Technology and standardization heatmaps. We catalogue technology maturity (TRLs), adoption timelines, and the commercial barriers created by the absence of certain test standards. The report includes an actionable roadmap for moving lab-proven fibers to certified field deployments.
-
Supply-chain and manufacturing diagnostics. From raw material sourcing to draw-tower constraints and splicing/connectorization bottlenecks, the research identifies pinch points and capital profiles for greenfield vs brownfield expansion.
-
Commercial playbooks for OEMs, tiered suppliers and investors. Tactical guidance covers pricing strategies for value-based premiums, channel strategies for medical and defense segments, and partnership/JV templates to accelerate regional access.
-
M&A and partnership lenses. The study identifies target archetypes (IP-rich niches, regional capacity, test-equipment specialists) and describes valuation sensitivities tied to recurring-revenue service models versus one‑off product sales.
Competitive landscape — strategic positions and implications
The sector’s competitive topology blends major glass and cable incumbents with agile specialists. Scale manufacturers maintain advantaged cost positions and distribution reach; specialist firms capture high-margin niches through customized materials and deep application engineering. Key strategic archetypes in the market include:
-
Large integrated manufacturers (global R&D + volume capability): these players leverage scale to serve high-volume telecommunications and industrial markets while investing in next-gen specialty lines to defend margin erosion.
-
Specialist innovators (niche materials, sensing, laser-grade fibers): firms focused on aerospace, defense, medical and laser systems concentrate on performance differentiation, proprietary processes and close customer integration.
-
Systems and component integrators (connectivity, splicing, and co-packaged optics enablers): as fiber architectures evolve, firms that solve mechanical, thermal and connectivity challenges become indispensable to system OEMs.
Notable company movements in early 2026 illustrate these dynamics. Several market leaders launched new fiber suites and demonstrated multicore and hollow-core handling at international conferences, signaling both technological readiness and commercial intent. These releases — spanning bend-insensitive single-mode fibers for co-packaged optics, next-generation erbium-doped fibers for compact amplifiers, and multicore demonstrations targeting terabit transmission — emphasize an industry pivot toward system-level performance and integrability. Concurrently, splicing and inspection vendors showcased equipment aimed at accelerating field deployment of multi-element fibers, underlining testing as a strategic differentiator.
Strategic implications — how to act in 2026
-
Prioritize architecture-aware investments. For buyers or vertically integrating OEMs, prioritize fibers that minimize system-level cost (e.g., enabling compact amplifiers, reducing transceiver complexity). For manufacturers, align R&D to architectures showing fastest commercial traction (SDM, hollow-core, co-packaged optics).
-
Invest in testing and certification early. Given the current measurement standard gaps, first-mover advantage accrues to organizations that can certify product performance with independent, repeatable methods — either by investing in test capability or partnering with accredited labs.
-
Hedge technology risk through partnerships. Joint development agreements and licensing reduce the time-to-market risk for firms lacking specific materials know-how, and they enable rapid entry into regulated sectors like medical and defense.
-
Embed sustainability into product roadmaps. With procurement and standards bodies favoring eco-design, firms that can demonstrate reduced lifecycle impact will access premium tenders and preferred-supplier statuses.
-
Design supply-chain resilience. Dual-sourcing strategies for critical preforms and specialized coatings, coupled with regional manufacturing nodes, will mitigate geopolitical and logistic risk for mission-critical customers.
Conclusion — the strategic value of the full report
For 2026 strategic planning, this study provides the market context, the technology and standards assessment, and the actionable playbooks that executives need to make capital allocation, partnership and product roadmap decisions with confidence. We surface the competitive maneuvers of scale incumbents and specialist challengers, document the most consequential technology bottlenecks (measurement standards and hardware testing capacity), and quantify the macro growth opportunity that underpins investment decisions.
This preview intentionally demonstrates the analysis depth while omitting detailed segment breakdowns and proprietary financial models — the exacting tables, cross‑tabulations by application and region, and the underlying unit-cost models are available in the full report. For firms that must translate 2026 uncertainty into decisive action, the complete Specialty Optical Fibers Market study offers the precision benchmarks and scenario tools necessary to move from strategic intent to commercial execution.
For detailed analysis of this topic, please visit the official page: Specialty Optical Fibers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


