



PW Consulting: Automotive Sunroof Market Poised for 11.57% CAGR Through 2032

Automotive Sunroof Market — Strategic Primer for 2026 Decision-Makers
Executive snapshot
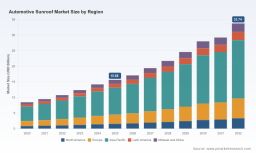
The Automotive Sunroof market is entering a decisive phase of scale and sophistication. After an acceleration through the early 2020s, total industry revenues climbed from USD 8.48 Billion in 2020 to USD 15.68 Billion in 2025. Our base-year analysis establishes 2025 as the inflection point: with continuing premiumization, electrification-driven vehicle architectures, and new glass and smart-material innovations, PW Consulting projects the market to expand at a compound annual growth rate (CAGR) of 11.57% through the 2026–2032 forecast window — reaching an anticipated market size north of USD 33 Billion by 2032. Equally important, market concentration is relatively high (CR3 ~68%, CR5 ~81%), which has profound implications for supplier strategy, OEM sourcing, and M&A activity in 2026.
Automotive Sunroof Market
Why this matters for 2026 corporate strategy
-
Timing: 2026 is a window in which investments in roof architecture and related value capture will either lock in product differentiation or leave players exposed to consolidation. Decisions on supplier selection, localized production, and platform integration made this year will determine cost curves and content share for the next vehicle generation cycle.
Automotive Sunroof Market -
Technology convergence: Sunroofs are no longer a single commodity option. They are becoming integrated modules — combining panoramic glass, smart electrochromic surfaces, solar collection, actuation electronics, and acoustic sealing — which requires systems-level sourcing and more advanced supplier qualifications.
Automotive Sunroof Market -
Supplier leverage: A concentrated supplier base means OEM procurement can extract scale benefits but also faces higher switching costs and capacity constraints. For component suppliers and Tier‑1s, 2026 is a make-or-break year to demonstrate modularity, cost-competitiveness, and IP depth.
Market dynamics shaping strategy
-
Premiumization & feature migration: Increasing consumer preference for larger glazing areas and panoramic designs is driving content per vehicle higher. This trend amplifies the importance of NVH performance, thermal comfort, and integrated solar options — features that command material and engineering investment but also support margin recovery through premium OEM pricing.
-
Electrification and weight sensitivity: Lightweighting imperatives in BEV and PHEV platforms are shifting material choices (thermoplastics, high-strength composites, lightweight actuators). Roof systems are now evaluated as part of the vehicle’s energy and range equation, not just as comfort options.
-
Localization and capacity plays: Rapid growth in Asian OEM demand — and related policy incentives — is driving capacity extensions and joint ventures in-region. Localization improves cost competitiveness and BOM stability but requires careful tech-transfer governance to protect IP and quality standards.
-
Regulation & quality risk: Recalls tied to assembly and material defects (for example, instances of sunroof glass detachment reported in 2026) underscore the reputational and warranty risk OEMs and suppliers face. Tighter regulatory scrutiny around occupant safety and glazing standards will increase qualification hurdles and total cost of supplier onboarding.
-
Input-cost volatility: Glass, specialized polymers, and actuator electronics remain exposed to commodity cycles and supply chain bottlenecks. Strategic buyers must model raw-material stress-tests and embed pass-through or hedging clauses into multi-year contracts.
Competitive landscape — capabilities you need on the radar
The market is led by established global players with deep OEM relationships and modular systems capabilities. Key incumbents include:
-
Webasto Group (Stockdorf, Germany) — a global leader in openable and fixed panoramic systems, motorized tilt & slide units, and solar-integrated modules supplying premium and volume OEMs. Recent strategic moves include capacity expansion in Europe and partnership activity in China to accelerate fixed transparent module production.
-
Inalfa Roof Systems Group B.V. (Venray, Netherlands) — known for low-noise modular panoramic systems with integrated glass and sensor platforms, supplying a broad roster of vehicle brands globally.
-
CIE Automotive (Bilbao, Spain) — offers modular roof platforms, electric actuation, and solar-control glass integration across passenger and light commercial segments.
-
Aisin Seiki Co., Ltd. (Nagoya, Japan) — provides advanced multi-panel panoramas, smart-glass options, and robust acoustic sealing tailored to OEM platform requirements.
-
Yachiyo Industry Co., Ltd. (Sayama, Japan) — supplies a mix of tilt & slide, panoramic, and pop‑up systems with motorized and premium material options.
-
Magna International Inc. (Aurora, Canada) — a longtime developer of thermoplastic modular roof panels; as of 2026, its rooftop systems business has been placed into a divestiture process, signaling consolidation and reshuffling among Tier‑1s.
-
Inteva Products LLC (Troy, USA) and Johnan Manufacturing Inc. (USA) — provide critical actuation, electronic controls, and region-focused manufacturing capability critical to North American OEMs.
Collectively, the incumbent cohort controls a large share of global content (CR3 ~68%; CR5 ~81%). This structure favors technology-rich suppliers but also creates openings for nimble innovators offering differentiated materials, integrated solar functionality, or disruptive assembly approaches.
Recent developments that change the playbook
-
Strategic partnerships and local capacity: In 2026, Webasto advanced its China strategy through an equity agreement with a regional glass manufacturer focused on fixed transparent modules — an arrangement that accelerates access to OEM programs in the fastest-growing market. This kind of JV model is becoming a dominant route for foreign suppliers seeking share without compromising localization speed.
-
Portfolio optimization and consolidation: Moves by major systems suppliers to divest or rationalize rooftop businesses indicate potential reconfiguration of supplier capabilities and pricing dynamics. Buyers and investors should expect both bolt-on M&A and targeted carve-outs to reshape supply options through 2027.
-
Capacity expansions in Europe and North America: Select suppliers have already increased panoramic glass production to meet OEM pull-through — signaling near-term capacity tightness and an opportunity for OEMs to lock supply or for Tier‑2s to ramp complementary capabilities.
-
Quality incidents and regulatory scrutiny: High-visibility recalls in 2026 tied to sunroof assembly defects have sharpened OEM attention on supplier process controls, incoming inspection regimes, and contractual liability — increasing the non-recurring engineering (NRE) commitments required to qualify new vendors.
Strategic recommendations for 2026 (prioritized)
-
Define future-content bets at platform-level: Treat roof systems as a cross-functional decision (body, thermal, NVH, electrical architecture). Build scenario-based BOMs for base, premium, and solar-integrated variants across vehicle programs to capture upside and quantify margin sensitivities.
-
Supplier segmentation and dual-sourcing: Given concentration and capacity dynamics, establish primary and secondary sourcing lanes with clear KPIs for quality, lead times, and tech migration. Negotiate holdback provisions and ramp clauses to mitigate supply shocks.
-
Invest in localized partnerships where market growth is fastest: JVs or minority investments with local glass or module manufacturers can accelerate program wins while preserving IP via staged transfers and guarded tooling contracts.
-
Embed rigorous quality governance: Strengthen supplier audit playbooks, adopt integrated testing regimes for glazing adhesion and dynamic loading, and require advanced process FMEAs and digital traceability to reduce recall exposure.
-
Evaluate M&A and divestiture opportunities: For suppliers, selectively pursue bolt-on capabilities (actuation electronics, smart glass) to create bundled offerings. For OEMs and investors, watch carved-out rooftop assets as acquisition targets that can be reshaped to meet platform demands.
What this PW Consulting report delivers — practical, execution-focused content
Our Automotive Sunroof Market research is structured to be a decision-ready toolkit for 2026. Highlights include:
-
Top-down market model with historical (2020–2025) validation and a 2026–2032 forecast, stress-tested under multiple demand, material-cost, and electrification scenarios.
-
Supplier capability maps, technology scorecards, and a competitive playbook that profiles leading vendors across quality, program wins, modularity, and regional capacity.
-
Commercial templates: sourcing/contract clauses, ramp schedules, and supplier KPIs tailored for sunroof systems and integrated glass modules.
-
Risk register and mitigation matrix covering regulatory, material, and assembly risks — including recall case studies and audit checklists for accelerated supplier qualification.
-
M&A and partnership decision frameworks that help buyers prioritize targets, assess valuation multiples for rooftop assets, and design earn-out and integration approaches.
-
Implementation-ready roadmaps for product teams: module architecture options, lightweighting levers, thermal/solar integration trade-offs, and estimated development timelines.
How to use this insight in 90, 180, and 365 days
-
90 days: Complete a supplier stress-test and dual-sourcing plan for priority platforms; defend warranty exposure through targeted quality audits.
-
180 days: Finalize JV/partnership terms or execute rapid capability acquisitions where localization unlocks program share; implement updated contract clauses for cost pass-through and capacity guarantees.
-
365 days: Launch integrated roof variants in next-generation platforms with validated supplier ecosystems and embedded life‑cycle cost modeling to capture higher content margins.
Closing — why consult this report before final 2026 decisions
The Automotive Sunroof market combines strong headline growth with concentrated supplier power and rising technical demands. Our analysis translates the macro growth trajectory into operational priorities: who to partner with, what capabilities to build or buy, and how to protect programs from quality and material shocks. The research surfaces the practical contractual, engineering, and commercial levers that executives must act on in 2026 to convert industry growth into durable competitive advantage.
For proprietary segment-level allocations, OEM-by-OEM content forecasts, and the full set of decision tools referenced above, PW Consulting’s full Automotive Sunroof Market report provides the complete intelligence and executable templates to guide your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Automotive Sunroof Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


