



PW Consulting: Microfocus X-ray Sources Market to Hit USD 658.96M by 2032 at 5.56% CAGR

Microfocus X‑ray Sources Market: Strategic Imperatives for 2026
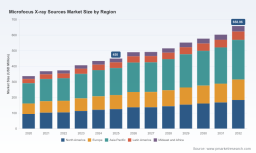
PW Consulting’s latest market study on Microfocus X‑ray Sources equips senior executives, product leaders and procurement teams with a decision-ready synthesis for 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the report traces a steady expansion of the market—from roughly USD 337 million in 2020 to USD 450 million in the 2025 base year—and a projected climb to approximately USD 659 million by 2032 at a compounded annual growth rate near 5.6%. These topline dynamics mask important inflection points in technology, regulation and commercial models; our research translates those signals into concrete options for value creation, risk mitigation and competitive positioning.
Microfocus X-ray Sources Market
Why this study matters for enterprise decision-makers in 2026
-
Transition from components to systems: Buyers increasingly evaluate microfocus sources not as stand‑alone tubes but as embedded elements of turnkey inspection, imaging and analysis solutions. Decisions now require integrated product, service and compliance roadmaps.
Microfocus X-ray Sources Market -
Regulatory and safety overlay: Recent standards and clearances—such as ISO guidance on effective focal spot measurement, FDA emphasis on safety for portable systems, and CE/FDA documentation requirements—raise the bar on traceability, test protocols and clinical risk management. Procurement criteria and product development timelines must reflect these constraints.
Microfocus X-ray Sources Market -
Cost and lifecycle pressure: High initial CapEx and ongoing maintenance for tube assemblies are persistent barriers to adoption in capital-constrained buyers (notably in clinical procurement and some industrial segments). Pricing, financing and service models are becoming as strategic as technical differentiation.
-
Technological differentiation: Advances in focal-spot control, nano/microfocus engineering and tube geometries (rod-anode, MesoFocus approaches) are enabling new inspection resolutions and lower-dose workflows, creating product tiering and new use cases that will define leaderboards in the coming three to five years.
What PW Consulting’s report delivers — operational, not theoretical
-
Robust market sizing and forecast model: A transparent, scenario-ready model covering 2020–2032 with sensitivity levers for price, replacement cycles and adoption curves—ready for integration into internal planning tools.
-
Demand-driver decomposition: Actionable analyses linking OEM pipelines, NDT adoption, clinical imaging trends and research lab procurement to near‑term revenue opportunities and downside scenarios.
-
Vendor benchmarking and concentration analysis: Comparative profiles, capability matrices and a market-concentration snapshot that reveals competitive dynamics and partnership opportunities for 2026 planning.
-
Product & technology roadmaps: Gap‑analysis templates for R&D prioritization—focal spot, power-efficiency tradeoffs, cooling and miniaturization—aligned to market willingness to pay and regulatory trajectories.
-
Procurement and commercial playbooks: RFP templates, evaluation scorecards, TCO calculators and service-level contract models that procurement and commercial teams can deploy immediately.
-
Regulatory readiness checklist: Mapped requirements for ISO, FDA and CE pathways, plus documentation templates to accelerate clearances and reduce time to revenue.
-
M&A and partnership origination: Opportunity heatmaps identifying target archetypes (technology tuck-ins, aftermarket services, regional distribution) and valuation sensitivities under alternative growth assumptions.
Competitive landscape — core vendors and what they signal
-
Hamamatsu Photonics (Japan): Established manufacturer focused on sealed microfocus sources for 2D/3D NDT and medical imaging—strong OEM relationships and a reputation for product reliability.
-
Micro X‑Ray (USA): Integrated designer/producer of micro- and mini‑focus tubes across broad voltage/power ranges—notable for configurable solutions that appeal to OEMs requiring modularity.
-
X‑RAY WorX GmbH (Germany): Specialist in high‑resolution open microfocus and rod-anode tubes for CT and DR—recent product updates indicate moves toward submicron resolution capabilities.
-
Comet Group (Switzerland): Offers MesoFocus and sealed microfocus technologies tailored to industrial inspection—strength lies in industrial-grade system integration and reliability.
-
MOXTEK (USA): Producer of microfocus sources and nano‑optic components, with strengths in niche imaging stacks and analytical instrument integrations.
-
Spellman High Voltage Electronics (USA): Supplier of microfocus generators and full-source assemblies for OEMs across medical and industrial domains—notable for high-voltage expertise and customization.
-
Anton Paar (Austria): Provider of high‑brilliance, low‑power microfocus sources for precision applications—targets scientific and laboratory customers demanding stability and compact footprints.
-
Sigray (USA): Developer of nano‑ and microfocus sources with an emphasis on advanced imaging and materials‑science use cases—driving innovation in source miniaturization and analytical performance.
Market concentration is meaningful but not monopolistic: the top tier of vendors collectively control a substantial share of industry revenue, creating attractive windows for targeted carve‑outs, strategic alliances and channel plays for well-capitalized entrants.
Recent developments shaping 2026 tactics
-
X‑RAY WorX announced a catalog update in March 2026 introducing a higher-voltage microfocus tube with submicron capabilities slated for later delivery—an indicator of demand for ultra‑high resolution in advanced NDT and research applications.
-
Industry engagement at shows through 2025 demonstrated continued interest in rod‑anode and specialized tube geometries, signaling that buyers are looking for both resolution and fractional improvements in throughput.
-
Standards and clearances—ISO focal‑spot measurement norms and tightened FDA expectations for portable systems—are pressuring vendors and buyers to validate performance claims with standardized evidence packages and stronger traceability.
-
Procurement friction due to material and maintenance costs persists, reinforcing the need for creative pricing, leasing and shared-service models to unlock stalled purchase cycles.
Strategic implications and recommended moves for 2026
-
For product leaders: Prioritize development that demonstrably reduces lifecycle cost and simplifies compliance evidence (instrument‑embedded QA tools, automated test logs) to accelerate hospital and regulated‑industry adoption.
-
For commercial teams: Offer bundled service contracts and flexible financing (pay‑per‑scan, leasing) to convert CapEx‑averse prospects and to capture aftermarket revenue.
-
For corporate development: Seek tuck‑ins focused on service networks, spare‑parts logistics or niche focal‑spot technologies rather than large horizontal acquisitions—these yield faster integration and clear ROI.
-
For procurement and operations: Implement the report’s vendor evaluation scorecards and TCO models to reduce acquisition complexity and to benchmark service SLAs against industry norms.
-
For regulatory and quality teams: Bake the ISO and FDA expectations into product release gates; invest in documentation automation to shorten clearance cycles and reduce rework.
-
For R&D and engineering: Balance pursuit of ultimate resolution with manufacturability and cost; incremental improvements in focal‑spot reproducibility and tube lifetime often deliver more commercial value than pursuing absolute technical extremes.
How PW Consulting supports execution
-
Custom due diligence and target screening for M&A, including technical diligence, regulatory gap analysis and commercial synergies.
-
Commercialization playbooks: product pricing, service design and channel strategies adapted to microfocus X‑ray business models.
-
Regulatory pathway mentoring: alignment to ISO focal‑spot measurement guidance, FDA 510(k) expectations for portable systems and CE/21‑CFR compliance mapping.
-
Procurement and vendor‑selection support: deployment of scorecards, RFP templates and negotiation frameworks tailored to capital equipment and recurring service portfolios.
In 2026, the microfocus X‑ray market is large enough to reward focused investments and disciplined commercial models, yet dynamic enough that timing and execution will determine winners. PW Consulting’s study condenses the complex technical, regulatory and commercial variables into decision-ready templates, scenario models and negotiation tools that accelerate time to value. For teams preparing budgets, product roadmaps or M&A pipelines this year, the full report contains the granular segment analyses, regional depth and vendor scorecards that support board‑level commitments and operational rollouts—contact PW Consulting or visit our report portal to access the complete dataset and practical attachments.
For detailed analysis of this topic, please visit the official page: Microfocus X-ray Sources Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


