



PPA Market to Reach USD 2,487.6M by 2032 at 7.0% CAGR — PW Consulting

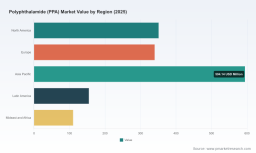
Polyphthalamide (PPA) Market — 2026 Strategic Preview
As corporate leaders and investment committees prepare for decisive capital allocation and product strategy moves in 2026, PW Consulting presents a focused strategic preview of the Polyphthalamide (PPA) market. This narrative synthesizes our most consequential findings from the full 2026–2032 study: a clear, actionable view of market growth dynamics, competitive positioning, regulatory pressure points, and the practical levers that will determine winners and losers. The piece is intentionally a “trailer” — it reveals analytical depth and the implications you need to consider now, while preserving granular subsegment datasets and proprietary models for subscribers to the full report.
Polyphthalamide (PPA) Market
Market snapshot: growth trajectory and what it means
PPA has moved firmly from a specialty engineering polymer to a mainstream strategic material for mobility, high-performance electrical & electronic (E&E) components, and industrial systems. Our base-year aggregation (2025) places the global PPA market at approximately USD 1,550 Million and documents sustained expansion from the start of the decade. Under our central forecast, the market grows at a compound annual growth rate (CAGR) of 7.0% over 2026–2032, reaching roughly USD 2,487.6 Million by 2032.
Polyphthalamide (PPA) Market
That growth profile produces three immediate implications for 2026 decision-making:
Polyphthalamide (PPA) Market
- Scale matters: the absolute market base is large enough that mid-tier players with disciplined margins can be highly attractive acquisition targets; conversely, incumbents without differentiated technology or integrated downstream relationships risk margin compression.
- Timing of investments is critical: with predictable mid-single-digit CAGR, investments in capacity, specialty grades, or vertical integration should be phased with sensitivity to raw-material and regulatory shocks rather than made on optimistic volume assumptions alone.
- Product mix will drive value: not all PPA applications grow evenly. High-temperature, flame-retardant and E&E-focused grades deliver disproportionate revenue quality and margin resilience under tightening emissions and safety regulations.
Industry dynamics shaping 2026
- Regulatory acceleration: Fuel-economy and CO2 targets continue to push automotive OEMs toward lightweight, high-temperature polymers. This regulatory tailwind is a structural demand driver for PPA in powertrain electrification and connector systems.
- Raw-material exposure: Terephthalic acid and other upstream feedstock price volatility remain a major operational risk. In 2026 the industry experienced material-driven revenue headwinds in specific regional pockets, underscoring the need for procurement stress-testing and hedging strategies.
- Safety and performance standards: Global safety rules and certification requirements for E&E and e-mobility components are raising the technical bar; flame-retardant and chemically resistant PPA grades are now standard requirements in many key programs.
- Concentration and competition: The sector shows a relatively high concentration among leading polymer producers, creating both stability and competitive barriers for new entrants. This concentration has important implications for pricing power and technology diffusion.
What the PW Consulting 2026 report delivers — practical assets for executives
The full study is designed as an operational toolkit for functional leaders. Highlights include:
- Market forecast models (2026–2032) with stress-case and upside-case scenarios, built at SKU-level elasticity assumptions and delivered in spreadsheet-ready format for integration into your corporate financial planning.
- Demand-shift matrices linking regulatory milestones (e.g., vehicle emissions timelines, safety standards) to grade-level demand by application cluster.
- Raw-material sensitivity engine that quantifies margin and cash-flow impacts from feedstock price swings and logistics events — customizable to your procurement terms and hedging policies.
- Supplier benchmarking and capability heatmaps that combine technical portfolio analysis with commercial footprint and service metrics (including lead times and regional compounding capabilities).
- Go-to-market playbooks tailored to three strategic archetypes — technology leader, cost-competitive scale player, and premium compounder — with prioritized initiatives, capex phasing, and go/no-go decision gates.
- M&A screening tool: a quantitative short-listing framework that synthesizes synergies, integration risk, and payback timing for potential targets in compounding and upstream feedstock positions.
- Regulatory impact assessment and compliance roadmaps — including testing and certification timelines — to align product development cycles with customer program windows.
These deliverables are supported by our proprietary datasets and scenario dashboards. As a preview, we summarize high-level themes below while omitting detailed subsegment tables and region-by-application breakdowns that are available in the subscriber package.
Competitive landscape — strategic postures of leading players
The market’s supply-side is anchored by global chemical majors and specialized compounders. Market concentration indicators reinforce that scale and product breadth are meaningful advantages: the top-three players account for a substantial portion of global revenues, and the top-five consolidate an even larger share. This structure shapes both competitive dynamics and the feasibility of new capacity entrants.
- BASF SE (Ludwigshafen, Germany) — Broad Ultramid Advanced PPA portfolio with rapid product innovation. Recent launches targeting high-voltage e-mobility connectors and UL-tested flame-retardant bridging grades illustrate a focused strategy to capture advanced E&E and automotive programs.
- Solvay SA (Brussels, Belgium) — Specialty polyamides expertise positions Solvay to serve demanding engineering applications where formulation science and regulatory compliance are decisive.
- Evonik Industries AG (Essen, Germany) — Deep capabilities in high-performance compounds and close customer co-development in automotive and industrial segments.
- Arkema S.A. (Colombes, France) — Rilsan-based offerings and composite know-how appeal to lightweighting and high-temperature niches.
- Celanese Corporation (Irving, Texas, USA) — Focused on resins for connectors and electronics, with recent capacity expansions to meet OEM program timelines.
- EMS-Chemie Holding AG (Domat/Ems, Switzerland) — Market-recognized Grivory HT products and dedicated high-temperature production lines enhance supply reliability for critical programs.
- DSM (Heerlen, Netherlands), DuPont (Wilmington, USA), and SABIC (Riyadh, Saudi Arabia) — Each competes on a mixture of global reach, application-specific grade portfolios, and customer-system integration capabilities.
- Regional and niche compounders — Akro-Plastic (Germany), Mitsui Chemicals (Japan), Kingfa (China) and others focus on specialized compounding, local footprint expansion, and cost-competitive supply. Notably, Kingfa’s recent Mexican facility start-up and other new regional actions reflect a continued emphasis on manufacturing proximity to OEM hubs.
Collectively, incumbents are pursuing three primary routes to capture value: (1) continuous grade innovation to secure OEM qualifications, (2) selective capacity additions near major customers, and (3) commercial partnerships with compounders to offer system-level solutions (material + design + processing). Our full competitive annex ranks these firms on a multi-dimensional scorecard (technology depth, capacity flexibility, regional service, and commercial agility).
Near-term risks and the 2026 watchlist
- Feedstock price volatility — particularly upstream aromatic intermediates — can flip operating results rapidly. Procurement and risk teams should model PPA margin sensitivity under staggered pass-through and contract structures.
- Regulatory synchronization — misalignment between product launches and evolving safety or emissions standards can delay revenue realization. Companies must lock certs and test cycles into program plans.
- Customer qualification timelines — OEMs increasingly demand holistic supplier audits (sustainability, traceability, LCA). Time-to-qualify remains a gating factor for new grades to reach production programs.
- Localization pressures — regional OEM strategies and nearshoring trends increase the commercial value of local compounding capacity; players without a local footprint may cede program share even if their materials are technically superior.
How to use this research in 2026
- Board-level capital allocation: use our scenario-based cash-flow models to set tranche-based capex releases tied to feedstock stability and customer qualification milestones.
- Product roadmaps: prioritize development resources on grades with the highest program win probability in electrified powertrains and E&E safety-critical applications.
- Procurement and commercial negotiations: apply the raw-material sensitivity outputs to craft dynamic pricing clauses and hedging strategies with major customers.
- M&A and partnership screening: leverage our target-screening framework to assess compounding or upstream bets against an objective synergy threshold and integration risk profile.
- Sustainability and circularity planning: align R&D and business-development initiatives to the certifications and recycled content targets likely to influence OEM sourcing decisions in the medium term.
Conclusion — the strategic choice for 2026
PPA is no longer a niche engineering polymer; it has become a strategic lever for performance, weight reduction, and regulatory compliance across automotive and E&E supply chains. The market’s mid-single-digit CAGR provides a stable backdrop, but the near-term landscape is defined by feedstock volatility, regulatory acceleration, and supplier concentration. Companies that combine disciplined commercial timing, targeted grade innovation, and flexible sourcing will capture outsized value.
PW Consulting’s full report supplies the detailed subsegment forecasts, supplier-by-grade benchmarking, and executable playbooks you will need to convert insight into 2026 action. For access to the complete dataset, downloadable models, and our interactive decision dashboards, consult the full study on our site or contact the PW Consulting engagement team.
For detailed analysis of this topic, please visit the official page: Polyphthalamide (PPA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


