



Battery Storage Inverter Market to Reach USD 11.3 Billion by 2032 at 8.2% CAGR — PW Consulting

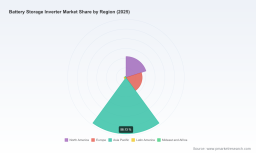
Battery Storage Inverter Market: Strategic Imperatives for 2026 Decision‑Makers
As battery energy storage systems (BESS) move from niche deployments to mainstream infrastructure, inverters sit at the operational and strategic center of the value chain. PW Consulting’s Battery Storage Inverter Market study synthesizes the technical, commercial, and policy vectors that will determine winners and losers between 2026 and 2032. The broader market has expanded from roughly USD 4.05 billion in 2020 to USD 6.4 billion in 2025 and is forecast to reach approximately USD 11.3 billion by 2032, implying an 8.2% compound annual growth rate across the forecast window. For executives setting 2026 budgets and product roadmaps, this study is designed to translate that macro momentum into practical, executable choices.
Battery Storage Inverter Market
Why 2026 Is the Pivotal Year
2026 marks the first full year of the study’s forecast period and the moment when many investments seeded in 2023–2025 will either scale or stall. Companies that align their R&D cadence, supply‑chain commitments, and commercial go‑to‑market with mid‑decade grid and regulatory shifts will extract disproportionate value. Our analysis shows that the market is neither a winner‑takes‑all commodity space nor an entirely fragmented cottage industry: the three largest players account for a material portion of industry shipments, with the top five consolidating an even larger share, pointing to sustained competitive pressure and opportunities for mid‑tier differentiation.
Battery Storage Inverter Market
What the PW Consulting Report Delivers
- Market sizing and trajectory. Full historical tracking (2020–2025) and scenario‑based forecasts (2026–2032) with high‑granularity demand curves at the product, application and system level—designed for investment cases and board presentations.
- Technology and product mapping. Comparative analysis of inverter topologies (e.g., grid‑forming vs. grid‑following), power class roadmaps, and integration patterns for PV‑plus‑storage and standalone BESS deployments.
- Commercial playbooks. Market entry and expansion blueprints, channel economics for OEMs and distributors, and monetization templates for software and services including BESS‑as‑a‑Service models.
- Supply‑chain risk and cost modeling. Input‑cost sensitivity (semiconductors, passive components, assembly labor), scenarios for regional manufacturing onshoring, and actionable mitigation strategies for procurement teams.
- Regulatory and incentive intelligence. Country‑level policy trackers, incentive qualification checklists, and compliance roadmaps—essential for capturing rebate and tariff opportunities in 2026 procurement cycles.
- Vendor scorecards and procurement tools. Anonymized supplier benchmarking across performance, reliability, warranty, software capability, and total cost of ownership to streamline RFPs.
Market Dynamics Shaping 2026 Strategies
The market’s 8.2% CAGR masks a mix of drivers and constraints that will play out with different intensity across geographies and applications. Key dynamics for 2026 include:
Battery Storage Inverter Market
- Grid services adoption. Increasing grid requirements—frequency response, black‑start capability, and inertia emulation—are pushing customers toward grid‑forming architectures and advanced controls.
- Convergence of hardware and software. Monetizable software layers (energy management, forecasting, remote diagnostics) are becoming decisive differentiators as hardware margins compress.
- Manufacturing localization and labor. Renewed investment in domestic power‑electronics facilities, particularly in the U.S., is creating labor pools and reducing geopolitical exposure but introduces near‑term cost and capacity tradeoffs.
- Policy and incentives. Targeted policy moves—such as incentive list updates and procurement incentives at the state/regional level—are shaping procurement timelines and technology choices for 2026 buildouts.
- Capital formation for large‑scale assets. Utility‑scale deployments are increasingly financed with structured offtake and merchant revenue mixes, raising expectations for predictable inverter lifecycle economics.
- Supply‑side innovation. Product launches in 2025–2026 that increase voltage platforms, consolidate functions (PV + battery + genset control), or expand single‑unit power ratings are forcing system integrators to reassess architecture and BOS planning.
Competitive Landscape — Who Matters and Why
The industry sits in a moderately concentrated position: the top three firms control a material share of shipments, and the top five widen that concentration. This structure creates both entry barriers and pockets of competitive advantage for firms that excel at system integration, software, or specialized power electronics. Below is a strategic read on the core players assessed in the report—each is profiled for product strategy, likely go‑to‑market moves, and capability gaps.
- SMA Solar Technology AG (Germany). Strength: mature residential-to‑utility product families and recognized large‑scale credentials. Strategic lens: leverage brand and system experience to capture integrated project services and grid‑scale procurement.
- Sungrow (China). Strength: high shipment volumes and broad product reach across utility and C&I segments. Strategic lens: economies of scale and rapid feature iteration enable aggressive global tendering but require localization strategies to sustain margins.
- GoodWe (China). Strength: focused hybrid and storage inverters for residential and smaller C&I use cases. Strategic lens: close partnerships with battery OEMs and channel play can expand footprint in distributed storage.
- Huawei (China). Strength: deep telco‑grade controls and grid‑interactive inverter platforms. Strategic lens: move up the value chain by selling integrated PV+BESS+controls bundles, especially where grid codes favor advanced functionality.
- Ginlong (Solis, China). Strength: recent expansion into higher‑power C&I inverters (notably a 125 kW product launch). Strategic lens: product differentiation through multifunction control will target emerging C&I and small utility markets.
- Growatt (China). Strength: commercial/hybrid inverter series designed for rapid storage integration. Strategic lens: targeted channel expansion and service capabilities can convert volume into recurring revenue.
- ABB. Strength: systems and BESS‑as‑a‑Service capabilities for industrial and utility customers. Strategic lens: monetize lifecycle services and asset performance management.
- Eaton. Strength: power management heritage and integration into C&I electrical ecosystems. Strategic lens: leverage existing electrical distribution relationships for bundled BESS solutions.
- Ingeteam (Spain). Strength: high‑efficiency stationary storage inverters for project‑grade applications. Strategic lens: pursue EPC partnerships for turnkey BESS deliveries.
- Dynapower (USA). Strength: advanced grid‑forming inverters for utility‑scale projects. Strategic lens: capitalize on U.S. capacity additions and grid modernization programs.
Recent product introductions—and their commercial implications—illustrate the market’s rapid technical evolution. Notable launches in 2025–2026 introduced higher‑voltage and higher‑power hybrid inverters that deliver system‑level efficiency gains and BOS simplification, which directly alter project economics for C&I and utility buyers.
Practical Implications for Corporate Decision‑Making in 2026
Executives should translate market direction into six tactical priorities for 2026 planning cycles:
- Prioritize modular, software‑enabled platforms. Invest in control and energy‑management software to capture ongoing service revenues and to protect hardware margins.
- Design for grid compliance and future‑proofing. Adopt inverter architectures capable of grid‑forming operation and firmware upgrades to meet evolving grid codes and ancillary‑services markets.
- Align manufacturing footprints with policy incentives. Use demand scenarios and incentive trackers to time capacity investments and qualify for local content incentives where available.
- Strengthen supply‑chain visibility. Model component risk (semiconductors, passives) and secure second‑source strategies for critical modules.
- Develop commercial pilots for BESS‑as‑a‑Service. Establish bundled offers with clear SLA and performance metrics to capture customers reluctant to make large CAPEX commitments.
- Engage early with regulators and utilities. Influence standards that determine interoperability and market access—proactive engagement accelerates deployment and reduces procurement friction.
How to Use the Full PW Consulting Report
The public summary here highlights strategic themes and the macro envelope. The full report contains the operational detail needed to act in 2026: downloadable vendor scorecards, RFP templates, regionally calibrated demand models, deployment scenarios tied to incentive milestones, and TCO/LCOE calculators that feed straight into finance and procurement workflows. For teams preparing capital approvals, the report’s scenario outputs and sensitivity tables reduce execution risk by making clear which assumptions drive value.
Conclusion
For 2026 decision‑makers, the battery storage inverter market offers both predictable growth and sharp technology inflection points. With the market more than doubling from 2020 levels and strong multi‑year CAGR, companies that combine product differentiation, software monetization, supply‑chain resilience, and regulatory agility will outcompete peers. PW Consulting’s Battery Storage Inverter Market study packages the necessary diagnostics, playbooks, and decision tools to move from strategic intent to measurable results—while preserving the detailed segmentation and vendor scoring that operational teams need to execute. Accessing the full report provides the granular inputs that convert the macro trends outlined here into high‑confidence investment decisions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Battery Storage Inverter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


