



PW Consulting: CIPP Market to Hit USD 44,992.31M by 2032 at 6.38% CAGR

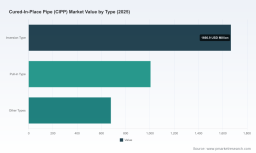
Cured-In-Place Pipe (CIPP) Market — Strategic Briefing for 2026 Decision-Makers
The global Cured‑In‑Place Pipe (CIPP) sector stands at a rare intersection of infrastructure imperative, regulatory momentum, and rapid product innovation. PW Consulting’s latest market study anchors on a 2025 base‑year market estimate of USD 3,349.8 Million and provides a structured, decision‑ready view of the 2026–2032 opportunity set. Our baseline forecast applies a 6.38% compound annual growth rate across the forecast window, while scenario analyses—reflecting accelerating technology adoption, certification rollouts and consolidation dynamics—outline upside pathways that materially expand addressable market value by 2032. This briefing summarizes the strategic value of the research for corporate leaders planning capital allocation, product roadmaps, and M&A in 2026, while preserving the proprietary micro‑segmentation that we publish in full on our research portal.
Cured-In-Place Pipe (CIPP) Market
Why 2026 is a Strategic Inflection Point
-
Regulatory and standards alignment. Recent clarifications of acceptance criteria (including established industry standards such as NASSCO specifications and state technical specifications) and new third‑party testing services for CIPP materials are removing certification friction for potable and wastewater applications. These developments lower adoption risk for utilities and create new commercialization levers for suppliers with validated product lines.
Cured-In-Place Pipe (CIPP) Market -
Technology and materials momentum. Innovations in UV curing, high‑temperature resins, and proprietary felt technologies are enabling shorter installation windows, expanded service temperature ranges, and improved long‑term structural performance. These technical advances translate directly into lower lifecycle cost propositions for municipalities and industrial owners.
Cured-In-Place Pipe (CIPP) Market -
Supply chain and cost pressures. While resin feedstock showed relative price stability in early 2025, material and labor quotes in 2026 are running higher than pre‑2020 averages. Expect 2026 procurement cycles to be more price‑sensitive—driving interest in either vertical integration or long‑term supply agreements to stabilize margins.
-
Market structure and consolidation opportunity. The sector remains commercially fragmented with notable niche specialists and technology‑centric players. This structure favors well‑executed roll‑up strategies and strategic partnerships that capture scale efficiencies, route density and account access to large municipal programs.
What PW Consulting’s CIPP Market Report Delivers (Practical, Actionable Content)
-
Robust market sizing and scenario forecasting: We provide a defensible 2020–2025 historical series, a 2026 base reset and multiple forecast scenarios through 2032 (baseline, accelerated adoption, and conservative). Each scenario is coupled with sensitivity tests around key variables—regulatory adoption timing, material pricing, and installation productivity.
-
Investment and ROI playbooks: Capital expenditure profiles for trenchless equipment, resin handling, and curing systems; NPV and payback models tailored to contractor, supplier and utility buyer archetypes; and lease vs. buy decision matrices for 2026 procurement cycles.
-
Go‑to‑market strategies: Channel mapping, tender and procurement timing for municipal programs, and field pilot design templates to shorten buyer approval cycles. These include messaging frameworks that translate technical advantages (e.g., potable‑grade liners, UV curing) into procurement language used by utility engineers and asset managers.
-
Supply chain diagnostics: Raw material sourcing maps, contract negotiation levers, and contingency plans for resin and felt inputs. The report highlights how manufacturers can mitigate margin compression through formula optimization, strategic stocking and supplier co‑development.
-
Competitive intelligence and M&A targets: A scored universe of strategic targets, tie‑up rationales (route density, technology access, geographic fill‑ins), and integration risk checklists. The report provides a prioritized pipeline for 12‑ to 36‑month consolidation plays.
-
Regulatory and certification tracker: Calendarized milestones for industry standards, emerging potable‑water approvals and third‑party testing services—critical to product acceptance in regulated procurements.
-
Field performance and warranty frameworks: Failure mode analysis, expected service life curves under differing cure/regimen options, and warranty structures aligned with lifecycle cost commitments from buyers.
-
Primary research assets: Executive interviews, supplier cost‑builds, anonymized utility buyer surveys and construction productivity observations to support contract negotiations and pricing strategy.
Competitive Landscape — Who Matters and Why
The market is characterized by specialized manufacturers, equipment providers, and felt/resin suppliers that together form the CIPP value chain. PW Consulting’s competitive analysis spotlights several firms that either shape product technology standards or act as attractive consolidation anchors.
-
United Felts (Martinsville, VA) : A felt and liner manufacturer with clear product innovation momentum. Recent IP milestones (patenting of proprietary felt technologies) and strategic acquisition activity to broaden UV‑capable liner capabilities signal a push toward integrated product platforms—combining material R&D with downstream liner systems. This positions them as a potential consolidation partner for providers seeking validated potable‑water solutions and global scale in UV liner manufacturing.
-
Perma‑Liner Industries (Clearwater, FL) : A manufacturer and system supplier recognized for trenchless equipment and UV inversion systems for municipal and residential rehab. Recent introductions of high‑temperature UV resins indicate a deliberate move to capture higher‑performance applications and shorten job cycle times—key differentiators in competitive bids where speed and minimal downtime command premium pricing.
-
Insituform Technologies / Azuria Water Solutions (Chesterfield, MO) : The pioneer brand with deep installed base and utility relationships. Scale and track record give them advantages in large municipal and force main projects. Their role in standards adoption and long‑duration project delivery often makes them a default partner for risk‑averse buyers—meaning competitive entrants must either out‑innovate on cost or co‑develop to win.
-
Bouckaert Industrial Textiles (BIT) : A materials specialist whose high‑quality polyester and fiberglass felts underpin many CIPP systems. The materials play is a strategic choke‑point: suppliers with felt control can materially influence liner performance, cost and lead times, which in turn affect contractor economics and product acceptance.
Recent developments we track closely include patented felt technologies and strategic acquisitions by material suppliers, the emergence of specialist UV and high‑temp resins, and the addition of third‑party certification and testing services. These moves are rewriting supplier bargaining power and accelerating product differentiation—key inputs to our competitor scoring and M&A recommendations.
Market Structure and Consolidation Dynamics
The CIPP market exhibits relatively low concentration among top firms, which creates both opportunity and risk. Low incumbent concentration means buyers can source competitively, but it also creates room for roll‑up strategies that capture route density and procurement leverage. For incumbent manufacturers and private equity, this is a market where smart, pragmatic consolidation—anchored on technology and distribution—can create value quickly. However, integration discipline and certification alignment are prerequisites to realizing synergies.
Our study quantifies concentration metrics and models multiple consolidation scenarios; those detailed breakdowns and target rankings are accessible in the full report and model package.
Strategic Implications — Actionable Priorities for 2026
-
Prioritize certification and third‑party validation. Products with early NSF/industry certifications will see faster adoption in potable and municipal pipelines—schedule testing early and budget for concurrent field pilots to accelerate procurement cycles.
-
Lock in resin and felt supply. With material and labor quotes elevated relative to pre‑2020, secure multi‑year supply agreements or pursue backward integration to stabilize unit economics.
-
Invest selectively in UV and high‑temp resin capability. These technologies reduce installation time and expand addressable projects; evaluate capital allocation relative to projected tender opportunities in target regions.
-
Build an M&A playbook now, not later. Identify targets that deliver route density, unique technology or municipal relationships and create integration templates for rapid scale‑up.
-
Use scenario‑driven capital budgeting. Prepare for a baseline growth pathway while keeping option value for accelerated adoption scenarios that could materially expand market value—our report includes the financial templates to execute both paths.
Where to Find the Full Intelligence
This briefing outlines why CIPP should be a strategic priority in 2026 and how firms can translate market dynamics into competitive advantage. PW Consulting’s full CIPP Market Report includes the granular segmentation, regional and application split analytics, vendor scorecards, valuation multiples, and downloadable financial models that underpin the strategic recommendations summarized here. For executives preparing capital plans, procurement managers tendering municipal contracts, and investors scanning consolidation targets, the full report provides the empirical backbone and executable templates needed to act with conviction.
Access the detailed tables, scenario models, and target lists on our report page to unlock the proprietary segment breakdowns and tactical playbooks referenced in this executive briefing.
For detailed analysis of this topic, please visit the official page: Cured-In-Place Pipe (CIPP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


