



PW Consulting: Instrument Transformers market to reach USD 261.9M by 2032 (6.5% CAGR)

Instrument Transformers Market 2026: Strategic Preview for C-Suite Decision Making
As power systems evolve under the twin pressures of decarbonization and digitalization, instrument transformers are quietly becoming strategic hardware — not just components. This preview from PW Consulting synthesizes the most consequential trends, regulatory inflection points and competitive dynamics that will shape capital allocation and product strategy in 2026. It is written to guide executive-level conversations while preserving the full, granular intelligence inside our complete Instrument Transformers Market report.
Instrument Transformers Market
Why this analysis matters for 2026 decisions
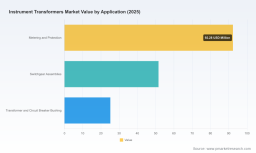
Executives face three immediate imperatives in 2026: secure grid reliability while integrating distributed energy resources (DERs); comply with tightening safety and testing standards; and structure supply chains to withstand component and testing bottlenecks. Our market modelling shows the instrument transformers market has moved from a foundational component market into a performance and compliance-driven segment: the market reached USD 169.0 Million (base year 2025) and, at a compound annual growth rate (CAGR) of 6.5% across our forecast horizon (2026–2032), is expected to reach USD 261.9 Million by 2032. Those topline dynamics translate into three practical consequences for corporate strategy: (1) higher margin opportunities for differentiated measurement and testing solutions, (2) rising expectations for integrated lifecycle services, and (3) renewed attention on standard-driven product redesign.
Instrument Transformers Market
Market trajectory and structural dynamics
-
Growth momentum: The market has grown steadily from the early 2020s baseline and is projected to expand at mid-single-digit rates through 2032. This growth is not uniform — it is being driven by modernization projects in transmission and distribution, electrification of new end-markets, and increased demand for high-accuracy measurement in grids with high DER penetration.
Instrument Transformers Market -
Concentration and competition: The market demonstrates moderate concentration. Leading global OEMs and specialized regional manufacturers compete on product breadth, testing capabilities and lifecycle services. The competitive landscape rewards scale in standards-compliant testing and localized manufacturing footprint to support fast project timelines.
-
Standards and testing: A wave of standards updates in 2024–2025 raises the bar on design, safety and uncertainty evaluation in testing. These regulatory shifts are increasing the technical threshold for suppliers and creating a differentiation axis for manufacturers that invest early in accredited testing infrastructure and design-for-compliance.
Regulatory and technical inflection points
-
New international standards: Recent publications have clarified safety requirements and introduced more rigorous methods for uncertainty evaluation in instrument transformer testing. These standards affect product design, factory acceptance testing (FAT), and the commercial terms of supply. Early adapters will convert compliance investments into sales advantages in conservative, safety-critical accounts.
-
Testing as a competitive moat: Alignment with updated testing protocols is no longer just a quality argument — it is procurement table stakes in many utility tenders. Vendors that have invested in expanded test halls and accredited procedures report shorter qualification cycles and improved win-rates on technical bids.
-
Integration with grid analytics: Measurement accuracy and secure digital outputs are becoming embedded in utility asset management and protection schemes. Suppliers who link device-level precision with data-ready communications and cybersecurity postures are capturing differentiated service revenue.
Competitive landscape — who matters and why
The market is composed of large, diversified power-equipment conglomerates and niche specialists. The following archetypes — and representative firms — illustrate strategic positioning:
-
Global integrated suppliers with systems breadth: These players offer instrument transformers as part of a broader grid-equipment portfolio and compete on full-solution integration and global service networks. Their advantage is seamless interoperability with switchgear, protection relays and substation automation stacks.
-
Technology-focused incumbents and specialists: Firms that focus on instrument transformers and associated metering solutions compete on engineering depth, custom designs and testing excellence. They frequently partner with utilities and OEMs for bespoke applications.
Key vendors mentioned in our research include leading global names and respected regional specialists. Each has invested along slightly different strategic axes: factory capacity and test facilities; digital measurement and communications; and regional manufacturing footprints. In 2024–2025, several firms announced capital investments and capacity expansions targeted specifically at meeting updated testing standards and faster delivery windows — a sign that supply-side players view compliance and speed as the most defensible differentiation routes.
What the PW Consulting report delivers (practical contents)
Our full report is designed for strategy teams, procurement leads, product managers and corporate development groups. It combines quantitative forecasting, scenario planning and practical tools for decision-making:
-
Market sizing & validated forecast (historical 2020–2025; forecast 2026–2032) with sensitivity scenarios and drivers decomposition.
-
Regulatory and standards matrix mapping the 2024–2025 updates to design, testing and procurement implications.
-
Competitive profiles and capability maps highlighting where each major vendor competes — product portfolio, test infrastructure, and service offerings — plus strategic moves observed in 2024–2025.
-
Buy-side decision framework: a procurement checklist that marries technical compliance, lifecycle cost, and supply risk considerations for tender evaluation.
-
Risk heatmaps and mitigation playbooks covering supply chain disruptions, test-lab bottlenecks, obsolescence risks, and standards-driven redesigns.
-
Go-to-market and M&A playbooks tailored to potential entrants and incumbents considering joint ventures, bolt-ons or capacity investments.
-
Representative case studies and vendor win-loss analyses that uncover tender-level success factors.
Implications for different stakeholders
-
For procurement and operations teams: Prioritize suppliers with accredited testing capability and transparent uncertainty metrics. Redesign contracts to include FAT timelines and clauses for standards-driven requalification.
-
For R&D and product teams: Accelerate efforts to meet the new testing and safety requirements, and embed digital outputs that align with utility analytics stacks. Consider modular designs to reduce requalification costs.
-
For corporate development and strategy teams: Use the mid-single-digit CAGR trajectory to evaluate scale-up economics, and consider bolt-on acquisitions that close capability gaps in testing, digital metering, or regional manufacturing.
-
For service and aftermarket leaders: Build accredited calibration and testing services as a margin-bearing complement to hardware sales; position these services within long-term service agreements.
Recommended near-term actions for 2026 planning
-
Run a compliance-gap audit across product lines against the latest international standards and requalify roadmaps where necessary. Compliance is now a market access filter in many large tenders.
-
Invest selectively in test capacity or partner with accredited labs to shorten qualification cycles — faster FATs are directly correlated with higher procurement win rates in our tender analyses.
-
Segment customers by procurement behavior (risk-averse utilities vs. private developers) and align commercial models accordingly — warranties, integrated services and performance guarantees matter more in safety-critical procurements.
-
Pursue targeted M&A to acquire testing capabilities, digital metering stacks or local manufacturing to reduce lead times in priority markets.
-
Embed scenario planning into annual capex cycles: model both conservative and accelerated DER adoption curves to stress-test product roadmaps and capacity plans.
How to use this preview — next steps
This strategic preview is intentionally selective: it surfaces the actionable insights executives need to begin 2026 planning while reserving the granular segment-level data, vendor-level benchmarking tables and downloadable decision tools for the full report. For teams preparing procurement cycles, product roadmaps or acquisition screens this year, the full dataset and vendor dossiers will enable detailed tender simulations, cost-to-serve models and a prioritized action list for compliance investments.
PW Consulting stands ready to brief executive teams on the implications of the new standards framework, to facilitate vendor due diligence, and to run bespoke scenario workshops that translate these market trajectories into board-level capital allocation decisions.
To access the full market dataset, segmentation analyses, vendor profiles and decision-toolkit, please refer to our Instrument Transformers Market report. The full report contains the segment-level breakdowns, regional dynamics and the comprehensive vendor benchmarking that underpin the strategic recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Instrument Transformers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


