



PW Consulting: 2-EHMA Market Set to Expand at 6.1% CAGR (2026–2032)

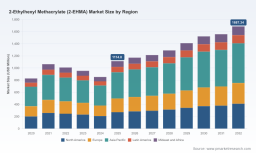
2-Ethylhexyl Methacrylate (2-EHMA): Strategic Market Brief for 2026 Decision‑Makers
As PW Consulting’s Senior Strategic Advisor and Lead Industry Analyst, I present a focused industry briefing that positions 2‑Ethylhexyl Methacrylate (2‑EHMA) as a high‑importance specialty monomer for firms evaluating portfolio moves, supply‑chain redesigns, and M&A targets in 2026. This article synthesizes market trajectory, competitive structure, feedstock dynamics, regulatory contours, and pragmatic use cases for corporate strategy. It intentionally demonstrates analytical depth while withholding the granular split tables and core segment numbers available in the full report—designed to guide executive decisions that must be taken now.
2-Ethylhexyl Methacrylate (2-EHMA) Market
Executive snapshot
- Market evolution: The 2‑EHMA market has exhibited meaningful volatility through the 2020–2025 period, with a measured rebound to an estimated USD 1,114.8 Million in the base year 2025 following mid‑cycle adjustments.
- Near‑ to mid‑term outlook: Our forecast projects a steady recovery and expansion through 2032, reaching approximately USD 1,687.3 Million by 2032, underpinned by a compound annual growth rate (CAGR) of 6.1% over the 2026–2032 forecast window.
- Market structure: The sector shows a high degree of concentration among a few global suppliers—market concentration metrics indicate that the top three players control the majority share and the top five reach an even higher combined share—creating a landscape where industrial partnerships, capacity plays, and differentiated product grades deliver outsized influence over pricing and access.
Why this matters for 2026 corporate decision‑making
2026 is a pivot year: many industrial buyers and producers are re‑pricing risk, re‑assessing feedstock exposure, and accelerating sustainability roadmaps. For 2‑EHMA, these trends translate into actionable decision levers:
2-Ethylhexyl Methacrylate (2-EHMA) Market
- Supply security vs. cost: With feedstock price shifts and regional logistics complexities, buyers must decide whether to pursue fixed‑volume offtakes, flexible short‑term contracts, or backward integration. The market’s concentration amplifies the leverage obtained through strategic supply agreements or equity partnerships.
- Product premiumization: Suppliers able to demonstrate consistent quality, lower impurity profiles, or eco‑credentialed grades can command margin premiums as coatings and adhesive formulators prioritize performance and lifecycle impacts.
- M&A and inorganic growth: Elevated concentration means bolt‑on acquisitions or long‑term JV arrangements can meaningfully accelerate market entry and secure downstream channel access with limited incremental scale.
Market trajectory and what the numbers imply
The historical series from 2020 through 2025 illustrates a market that weathered demand swings—reflecting downstream cyclicality in coatings, adhesives, and specialty polymers—before strengthening into the 2025 base year. A projected continuation of this recovery delivers a mid‑single‑digit CAGR (6.1% across 2026–2032). Translating this trajectory into strategic implications:
2-Ethylhexyl Methacrylate (2-EHMA) Market
- Investment timing: Producers evaluating capacity additions should prioritize staged investments (debottlenecking and modular units) that align capex deployment with the forecasted steady growth rather than large one‑off brownfield expansions.
- Pricing strategy: A predictable growth path supports structured pricing agreements indexed to feedstock movement, but firms must retain flexibility to respond to episodic raw material shocks.
- Portfolio allocation: Companies with exposure to multiple monomers should consider increasing 2‑EHMA allocations selectively—where formulations benefit from its hydrophobicity and glass transition properties—while protecting cash flows through short lead‑time production options.
Competitive landscape — capabilities and strategic postures
The competitive map features both global incumbents and regional specialists. A few illustrative profiles highlight strategic choices that matter to buyers and investors:
- Evonik Industries AG (Essen, Germany): Offers VISIOMER® EHMA and a sustainable VISIOMER® eCO grade. Evonik’s emphasis on branded, application‑oriented grades and active presence at industry forums underlines a strategy focused on premiumization and customer intimacy through technical service.
- BASF SE (Ludwigshafen, Germany): Produces industrial grades used in polymerization and chemical syntheses. Its regulatory diligence—evidenced by recent Safety Data Sheet updates—signals a risk‑management approach suited to large industrial customers demanding consistent compliance and traceability.
- Mitsubishi Gas Chemical Company, Inc. (Tokyo, Japan): Serves coatings, adhesives, and fiber treatment niches. The company’s position suggests a balanced strategy of portfolio breadth and targeted application support in Asia and export markets.
- China‑based suppliers (e.g., Shanghai Hechuang, Longchang, Henan GP): These firms provide competitive cost positions and regional supply continuity. Their prominence is key to buyers seeking diversified sourcing; however, differences in quality controls and sustainability credentials require careful supplier qualification.
Recent corporate moves—such as trade show promotion of sustainable grades, SDS revisions, and public supply announcements—signal that incumbents are investing in both market visibility and operational governance. For strategic buyers, this reinforces the value of technical audits, pilot programs, and staged contract commitments before committing to long‑term offtake agreements.
Supply‑chain and feedstock dynamics
Two near‑term forces are shaping margins and sourcing tactics:
- Feedstock price shifts: Observed declines in 2‑ethylhexanol prices in late‑2025 across multiple geographies have created a temporary easing of input costs. For manufacturers, this opens a window to restore margins or rebalance inventory policy; for buyers, it is an opportunity to renegotiate pricing clauses or re‑calibrate inventory targets.
- Regulatory reporting and compliance: While current EU REACH listings do not impose authorization or specific Annex restrictions on 2‑EHMA, the compound appears on certain national and regional reporting rolls (for example, emissions and toxic release inventories). Firms must therefore maintain robust reporting and incident‑management capabilities—especially when expanding production or entering new jurisdictions.
Risk matrix and scenario planning
We recommend three scenarios for board and C‑suite review:
- Base Case (aligned with our 6.1% CAGR): Staged capacity additions, portfolio focus on higher‑margin grades, and fixed/floating blended contracts for feedstock to capture stability and upside.
- Downside (demand softening or regulatory tightening): Prioritize working capital efficiency, reduce exposure to long‑tail contract commitments, and accelerate customer diversification into resilient end‑uses.
- Upside (accelerated demand from new formulations or sustainability drives): Rapidly scale via JVs or targeted acquisitions, and secure prioritized access to raw materials through equity stakes or long‑term supply agreements.
What the full PW Consulting report delivers (operational and actionable)
To convert insight into action, the full report includes:
- A validated historical market time series and calibrated forecast model (2026–2032) with sensitivity testing and scenario outputs;
- Granular regional and application segmentation with demand drivers and buyer archetypes (note: the detailed segmentation tables and exact sub‑region/app share figures are presented in the report to preserve competitive confidentiality);
- Supplier scorecards and capability matrices, including technical grade comparisons, sustainability credentials, and capacity overlays;
- Feedstock exposure analysis with hedging templates and recommended procurement structures tailored to different buyer risk profiles;
- Commercial playbooks for premium product launches, commercial negotiation checklists, and example term‑sheet language for offtakes and JVs;
- M&A screening tools, target prioritization criteria, and a short list of acquisition archetypes with estimated payback ranges under our base and upside cases;
- Due diligence checklists (technical, regulatory, environmental) and a 90‑day integration roadmap for post‑transaction execution.
How to use this research in 90, 180 and 365 days
- 90 days: Run supplier technical audits for critical grades, negotiate short‑term hedged purchase orders, and launch a cross‑functional task force to validate use‑case ROI for premium formulations.
- 180 days: Finalize at least one strategic supply agreement with flexible volume options, pilot a sustainability‑certified grade with a key customer, and shortlist inorganic targets for deeper diligence.
- 365 days: Execute staged capacity or JV plans aligned with demand triggers from the report’s scenario analysis, and operationalize the procurement and pricing frameworks included in the report.
Closing guidance for executives
2‑EHMA sits at an inflection of steady demand growth and supplier concentration. In 2026, firms that combine pragmatic supply‑chain engineering (short‑term hedges, diversified sourcing), focused product premiumization, and selective inorganic moves will be best placed to convert forecast growth into sustainable margin expansion. The full PW Consulting 2‑EHMA Market study provides the granular segmentation, supplier economics, and transactional playbooks necessary to operationalize these strategies—accessing that detail will materially shorten the path from insight to impact.
For boards and strategy teams ready to translate this briefing into a decisive action plan, PW Consulting offers a tailored executive briefing and scenario war‑gaming session to align senior stakeholders on the optimal course. Detailed segment tables, firm‑level financial proxies, and the complete competitive scorecards are available in the full report.
For detailed analysis of this topic, please visit the official page: 2-Ethylhexyl Methacrylate (2-EHMA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


