



PW Consulting: HSM Market to Reach USD 3,797.8M by 2032 at 13.5% CAGR

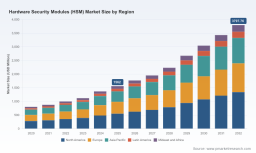
Hardware Security Modules (HSM) Market: Strategic Implications for 2026 Decision-Making
As enterprises accelerate digital transformation and governments tighten cryptographic standards, HSMs have moved from “nice-to-have” infrastructure components to mission-critical strategic assets. PW Consulting’s new HSM Market research (base year 2025; forecast 2026–2032) captures this transition with a data-first perspective: the market has expanded rapidly over the past five years and is forecast to sustain double-digit growth through the next decade at a 13.5% CAGR. In plain terms, the sector more than doubled in scale since 2020 and is projected to approach multi‑billion-dollar scale by 2032—conditions that materially affect procurement timing, vendor selection, risk planning, and architecture decisions in 2026.
Hardware Security Modules (HSM) Market
Why this research matters in 2026
-
Regulatory inflection points are forcing action. Recent updates—PCI DSS 4.0’s tightened HSM requirements and U.S. Treasury mandates requiring FIPS 140‑3 Level 3 certified hardware for certain government financial systems—mean many organizations cannot defer HSM refresh cycles without regulatory and contractual risk.
Hardware Security Modules (HSM) Market -
Quantum and post‑quantum cryptography (PQC) are now procurement drivers. NIST’s finalization of PQC algorithms (notably ML‑KEM and ML‑DSA) has created a hardware refresh imperative for federal agencies and operators of critical infrastructure; most vendors today provide external PQC support, while only a few are redesigning hardware/firmware for genuine quantum-safe operations.
Hardware Security Modules (HSM) Market -
Cloud, AI, and confidential computing create new demand patterns. Enterprises protecting large AI datasets and models, and those adopting confidential compute architectures, look to HSMs for model and key protection—driving demand for both cloud-hosted and on-premise appliances that integrate with modern orchestration frameworks.
-
Supplier concentration and certification complexity introduce procurement risk. The top industry players command the majority of market share (the three largest vendors account for a significant portion and the top five for an even larger share), creating both leverage and single‑vendor risks for large buyers.
Structural dynamics and growth drivers
-
Payments and financial services remain foundational demand vectors, but enterprise use-cases—PKI, database encryption, authentication, IoT and embedded security (notably automotive OTA and V2X), and AI model protection—are broadening the end-market footprint.
-
Cloud adoption is changing consumption models. Dedicated cloud HSM offerings and HSM-as-a-service are maturing, delivering FIPS-validated, managed hardware for teams that prefer operational flexibility. At the same time, regulated workloads continue to push investment into certified on-premise HSMs.
-
Cost and supply-chain pressures persist. Specialized silicon, secure elements, and certified manufacturing increase unit costs and create procurement lead times that buyers must build into IT roadmaps.
-
Certification and lifecycle complexity raise TCO. FIPS 140‑3, PCI requirements, and emerging PQC validation paths add non-recurring engineering and validation costs for vendors—costs that are often passed along or reflected in integration timelines.
Competitive landscape — who matters and how
The market exhibits a mix of long-established incumbents, specialized cryptographic suppliers, cloud giants, and emerging vendors focused on confidential compute and AI security. Broadly, vendor differentiation today falls into four vectors: certification pedigree, hardware architecture (dedicated appliance vs. embedded module vs. FPGA/SoC), cloud-native integration and service models, and PQC readiness.
-
Large system vendors and traditional HSM specialists—such as Thales Group (Paris), Entrust (Dallas), IBM (Armonk), and Utimaco (Aachen)—remain go‑to suppliers for regulated, high-assurance deployments. These vendors combine product breadth, formal certifications, and long experience in payments and PKI markets.
-
Cloud hyperscalers—AWS and Microsoft Azure—provide managed CloudHSM offerings providing fast time‑to‑value and compliance-certified hardware for enterprise cloud-native workloads. Their strength is operational speed; their questions are often around isolation, lifecycle portability and some regulatory nuances.
-
Specialists and embedded suppliers—Infineon, Yubico, Securosys, Lattice Semiconductor, ETAS and others—focus on secure elements, microcontrollers, and FPGA-based modules for embedded, IoT, and automotive use-cases where size, power, and integration matter.
-
Next-gen entrants—Fortanix, Futurex—target confidential compute, AI data protection and cloud-native cryptography, combining software-defined controls with HSM-grade protections and emerging PQC capabilities.
-
Defense and critical-infrastructure vendors—Motorola Solutions, Ultra Electronics, Atos—continue to win specifications where bespoke hardware, rigorous certification and national security requirements are decisive.
Recent vendor activity illustrates the market’s evolution. A notable product launch in late 2025 introduced high‑performance multi‑tenant HSMs with explicit PQC readiness and industry-targeted features (notably for smart metering and automotive). In 2026 several vendors completed or updated FIPS 140‑3 certification paths—strengthening procurement propositions for government and regulated buyers—while alliances emerged to integrate HSM-driven key management into AI data infrastructure ecosystems. These developments underscore three trends: faster product iteration toward PQC, the strategic importance of modern multi‑tenancy and cloud integration, and the material impact of certification milestones on procurement preferences.
What PW Consulting’s report provides (practical deliverables)
-
Forward-looking market sizing and scenario forecasts calibrated to 2025 base-year data and a 2026–2032 projection horizon, with sensitivity analysis for regulatory and quantum adoption timelines.
-
Vendor scorecards and a capability matrix covering certification coverage, PQC roadmap, performance benchmarks, multi‑tenancy and cloud integration features, and managed service maturity.
-
Procurement playbooks and TCO models that capture capital, integration, compliance, and lifecycle renewal costs—designed for CISOs, procurement leads and CFOs to evaluate replacement vs. retrofit strategies.
-
Migration and integration blueprints for common enterprise architectures: on‑prem clustered HSMs, hybrid cloud HSM strategies, edge/embedded deployments for IoT and automotive, and confidential compute architectures for AI workloads.
-
Compliance checklists and acceptance test plans for PCI DSS, FIPS 140‑3 Level 3, and PQC migration validation—mapped to procurement contract clauses and SLA language.
-
Risk registers and mitigation playbooks that address supplier concentration, lead‑time exposure, and supply‑chain cost volatility.
-
Executive decision frameworks and board‑level briefing templates to accelerate internal alignment when HSM investments compete with other security and infrastructure priorities.
Actionable recommendations for 2026 enterprise decisions
-
Treat HSM strategy as part of your cryptographic lifecycle roadmap. Given regulatory timetables and PQC developments, create a prioritized replacement or retrofit path for ‘must‑replace’ systems and a second tranche for ‘can‑defer’ systems, with explicit timelines tied to compliance deadlines.
-
Prioritize vendors with demonstrable FIPS 140‑3 Level 3 coverage and a clear hardware‑level PQC plan. External or “bolt‑on” PQC options reduce short‑term risk but do not substitute for a vendor roadmap that addresses firmware and silicon changes where required.
-
Design for modularity and portability. Use abstraction layers and key management protocols that enable workload portability between on‑prem HSMs and cloud HSMs, reducing lock‑in and simplifying audit and incident response.
-
Hedge supplier concentration: combine strategic partnerships with primary suppliers and secondary spot-capacity agreements or managed services to mitigate delivery delays and certification gaps.
-
Factor full integration costs into TCO: hardware purchase is only the beginning—plan for integration, application changes (PKI, payment pipelines, DB encryption), testing, certification evidence collection, and staff training.
-
Embed PQC testing into procurement pilots now. Establish lab testbeds that validate vendor PQC claims against your specific application stack and performance SLAs before enterprise-scale rollouts.
-
For AI and confidential compute use-cases, evaluate vendors that provide end‑to‑end protection for datasets and model keys—HSMs alone are necessary but not sufficient; orchestration, attestation and key lifecycle tooling are equally important.
How to use this research
This analysis is intended to inform board-level prioritization, procurement strategies, and architecture roadmaps for 2026. It exposes the strategic levers and pragmatics you must control—regulatory deadlines, PQC migration, supplier risk, and integration cost—while reserving granular segment tables and vendor share breakdowns for the full report. For procurement teams and CTO offices that need the complete decision toolkit (detailed regional and application splits, downloadable TCO models, vendor scorecards and contract language templates), the full study provides the necessary datasets and executable artifacts to move from strategy to procurement within quarters rather than years.
In an environment where policy, quantum-readiness and cloud-native architectures converge, a deliberate, data-driven HSM strategy is not optional—it is a competitive and compliance imperative. PW Consulting’s HSM Market research gives you the strategic view and the practical tools to act decisively in 2026.
For detailed analysis of this topic, please visit the official page: Hardware Security Modules (HSM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


