



PW Consulting: Carbon Brush Market Poised for USD 399.99M by 2032 at 4.1% CAGR

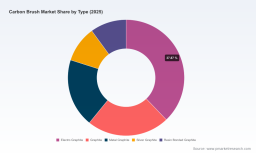
Carbon Brush Market — 2026 Strategic Outlook: A PW Consulting Executive Preview
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present this executive preview of our Carbon Brush Market research to highlight the strategic choices facing industrial manufacturers, OEMs, procurement leaders, and investors in 2026. Grounded in a rigorous assessment with base year 2025, our study traces developments across 2020–2025 and provides a scenario-driven forecast for 2026–2032. The market, which expanded from roughly USD 250 Million in 2020 to about USD 301 Million in 2025, is modeled to grow at a 4.1% CAGR through the forecast window and approach the USD 400 Million mark by 2032. These macro dynamics — and the competitive structure that places the top three suppliers at just under half of the market and the top five at roughly mid‑fifties concentration — set the context for the tactical decisions we expect organizations to take in 2026.
Carbon Brush Market
Why this market matters to 2026 decision-makers
-
Strategic leverage: Carbon brushes remain a small but mission‑critical component across motors, generators, signal and current transmission assemblies, and grounding systems. Even modest shifts in brush life, wear rates, or unit pricing can materially affect total cost of ownership for fleets of motors or high‑value rotating equipment.
Carbon Brush Market -
Timing of inflection points: 2026 represents an operational inflection driven by ongoing electrification of industrial systems, incremental renewables deployment (notably wind and related generator systems), and steady modernization of material‑handling and process equipment. These trends heighten demand for reliable, lower‑wear carbon solutions and aftermarket service models.
Carbon Brush Market -
Supply‑side fragility: Graphite raw material sourcing is geographically concentrated, and episodic supply constraints have already led to price volatility and lead‑time risk. Procurement teams must reconcile near‑term availability with multi‑year volume needs.
Key drivers and headwinds shaping 2026 strategies
-
Demand drivers: Continued modernization of industrial motors, electrification of transport and off‑highway equipment, increased deployment of variable‑speed drives, and growth in heavy industrial applications drive base demand. At the same time, the aftermarket for brush replacement, refurbishment, and condition‑based maintenance is a rising share of vendor revenue.
-
Material and cost pressures: Graphite feedstock is concentrated in a handful of producing countries, creating episodic price and availability risk during demand spikes. Successful players are investing in material substitution strategies, recycling initiatives, and upstream partnerships to stabilize input costs.
-
Technology substitution and product evolution: Brushless motor topologies continue to displace some brush applications, particularly in consumer and certain automotive subsegments. Conversely, large rotating equipment (including wind turbine generators, heavy industry motors, and specialized traction systems) continues to rely on engineered carbon brush solutions, often with premium formulations for extended life and reduced maintenance.
-
Regulatory and quality bar: OEM specifications and manufacturing quality systems matter. Compliance with standards — including detailed specifications for dimensions, electrical performance, and wear (as captured in norms such as ISO, DIN and ASTM regimes) — plus ISO 9001:2015 manufacturing controls, are table stakes for suppliers seeking long‑term OEM contracts.
What this means for procurement, product, and corporate strategy in 2026
-
Procurement playbook: Lock in diversified graphite supply through multi‑tier contracts, implement strategic buffer stock levels tied to risk scenarios, and qualify secondary suppliers in non‑core geographies. Incorporate clause structures that allow for targeted cost pass‑throughs and performance‑linked rebates for long‑term agreements.
-
Product and R&D priorities: Invest in materials science that reduces wear and friction without compromising conductivity — for example, high‑density electrographitic formulations and hybrid composites. Pilot predictive‑maintenance enablement (sensors and brush wear telemetry) with strategic customers to create sticky aftermarket revenue.
-
Commercial and M&A moves: Expect mid‑market consolidation and bolt‑on plays focused on technical capabilities (e.g., advanced formulations, precision machining) and channel coverage. Buyers should prioritize targets that bring proprietary materials, OEM approvals, or strong position in high‑growth verticals like renewables and traction systems.
-
Operational resilience: Upgrade supplier qualification frameworks to include material traceability, sustainability criteria, and audit schedules. Manufacturing footprint decisions should balance nearshoring to reduce lead times with regional capabilities for specialty brush formulations.
Practical deliverables in the full PW Consulting report
-
Robust market sizing and methodology: Transparent assumptions and reproducible demand models covering historical 2020–2025 performance and scenario outputs for 2026–2032, including high/medium/low adoption pathways.
-
Actionable go‑to‑market playbooks: Step‑by‑step procurement, product development, and aftermarket commercialization plans calibrated by strategic priority and resource intensity.
-
Supplier landscape and scorecards: Comparative capability matrices, risk heatmaps, and supplier selection templates to accelerate qualification and bidding processes.
-
Financial and valuation tools: Pricing and margin benchmarks, unit economics templates, and M&A screening criteria that translate market dynamics into transaction readiness.
-
Compliance and testing checklist: Practical templates to align product specifications with OEM and international standards, reducing time to qualification for new brush grades.
Competitive landscape: positioning the leading players
The market exhibits moderate concentration: the leading three suppliers together account for a significant share, and the top five extend that hold into the mid‑fifties. This configuration fosters both competitive innovation and selective partnership opportunities.
-
Ohio Carbon Industries — a custom‑capability leader: Strong in bespoke brushes, grounding solutions and machined graphite for defense, aviation, and transit systems. Their value proposition centers on engineered solutions for mission‑critical applications and close collaboration with OEMs on specifications and testing.
-
St Marys Carbon — engineering depth in heavy‑duty applications: Well‑regarded for carbon graphite brushes, bearings, and mechanical carbon components across industrial and defense markets. St Marys' historical depth in manufacturing and material know‑how makes it a natural partner for reliability‑focused OEMs.
-
Helwig Carbon Products — broad product systems and aftermarket focus: Offers brush holders, spring assemblies and shaft grounding systems along with brush products — an integrated approach attractive to clients seeking single‑source supplier relationships for assemblies and spares.
-
Sinotech — specialist in small and precision motors: Custom engineering for miniature, stepper, and servo motors positions Sinotech well as industries pushing for higher precision and lower friction at small scales.
-
Anglo Carbon & Contacts — regional OEM relationships: Known for fractional‑horsepower solutions and earthing products, with deep ties to transport and domestic appliance segments in its home geography.
-
Aupac and Toyo Tanso — Asia technical platforms: Both companies supply micro‑motor and small appliance segments with high throughput manufacturing and established local OEM relationships.
-
Resonac and CFC Carbon — advanced materials and new‑generation carbon: These players emphasize high‑value graphite composites, felt, and pyrolytic materials, offering pathways for performance improvements and thermal/electrical integration in advanced devices.
-
Mersen — electrographite and industrial breadth: Mersen’s electrographitic lines and targeted product launches for heavy manufacturing reflect a playbook of higher‑end industrial applications and lifecycle performance gains. Their recent high‑density brush series, introduced in 2024, illustrates the industry’s push for reduced wear and extended lifecycles.
-
Schunk Group — renewables and environmental hardening: With an explicit focus on wind turbine generator systems and an expanded renewable energy portfolio announced in late 2024, Schunk has positioned itself to capture premium demand in offshore and harsh environment applications.
Technology, compliance and supply considerations you cannot defer
-
Raw material traceability: Given the concentration of graphite mining in a small set of countries, buyers should require chain‑of‑custody statements and engage in dual‑sourcing where possible.
-
Standards and factory credentials: ISO 9001:2015 certification and compliance with OEM specifications (standardized norms covering dimensions, electrical performance and wear characteristics) are non‑negotiable for tier‑one contracts.
-
Sustainability and circularity: Reuse, recycling and reduced material intensity will increasingly influence procurement decisions, both for cost reasons and to satisfy end‑customer ESG requirements.
2026 decision calendar — a pragmatic sequence
-
Q1: Rapid diagnostics — conduct a supplier risk and inventory audit, quantify exposure to material concentration, and run a stress test of 12‑ and 24‑month demand scenarios.
-
Q2: Secure and diversify — negotiate long‑lead contracts with primary suppliers, qualify secondary sources, and pursue validated substitution pilots for high‑risk components.
-
Q3: Deploy tech pilots — trial high‑density and low‑wear brush formulations with select accounts; implement condition‑monitoring pilots to prove value of predictive maintenance offerings.
-
Q4: Scale and lock — finalize commercialization and aftermarket pricing models, secure certifications for new grades, and sequence rollout across prioritized verticals.
Our full PW Consulting Carbon Brush Market report provides the granular segmentation, regional and application splits, supplier financial profiles, and Excel‑based models that operationalize the recommendations above. This executive preview is intended to equip leaders with the strategic framing necessary for decisive action in 2026; the detailed tables, scenario spreadsheets, and supplier scorecards in the full study will convert strategy into executable steps. Visit PW Consulting’s Carbon Brush Market page to access the complete research package, consulting playbooks, and subscription access to our dynamic forecast models.
For detailed analysis of this topic, please visit the official page: Carbon Brush Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


