



PW Consulting: OCTG Market to Reach USD 38.95B by 2032 at 6.8% CAGR

Oil Country Tubular Goods (OCTG) Market — 2026 Strategic Preview
Executive snapshot
As the upstream energy sector recalibrates for a complex 2026, OCTG remains a cornerstone of project execution and field performance. Our PW Consulting baseline shows the global OCTG market expanding from roughly USD 17.4 Billion in 2020 to an estimated USD 24.5 Billion in 2025, and continuing along a growth trajectory that reaches close to USD 39.0 Billion by 2032 — a compound annual growth rate of 6.8% across the forecast window. These headline dynamics reflect a mix of recoveries in exploration and production activity, accelerated investment in high-spec applications and selective infrastructure awards that demand premium tubular solutions.
Oil Country Tubular Goods (OCTG) Market
Why this research matters for 2026 decision cycles
- Investment prioritization: Capital allocation for 2026–2028 must account for the OCTG market’s steady growth profile and the accelerating portion of demand that requires premium materials and services. Understanding where pricing and specification inflation will occur is now a board-level concern.
- Procurement and sourcing: Trade policy shifts, standard updates and raw-material volatility are compressing lead times and margin buffers. Procurement strategies that ignore these dynamics will face increased supply risk or unexpected cost inflation.
- Competitive positioning: The market exhibits moderate concentration — the top three and five suppliers account for a meaningful share of global supply — creating both entry barriers and targeted opportunities for differentiated players.
Market trajectory and structural drivers
Two complementary forces are driving the OCTG market through 2026 and beyond. First, the recovery and selective expansion of upstream activity in target basins are lifting volumetric demand and underpinning long-term contracts. Second, there is a structural uplift in demand for higher-spec tubulars — corrosion-resistant alloys, premium connections and engineered solutions for complex wells — that pushes average selling prices upward even as producers seek cost efficiencies.
Oil Country Tubular Goods (OCTG) Market
Our historical series (2020–2025) captures the market’s path through cyclical stress and incremental recovery, while scenario-led forecasts (2026–2032) stress-test outcomes under competing commodity price, policy and project-award assumptions. The 6.8% CAGR embedded in our central scenario is not uniform across all product classes or geographies; rather, it masks a re-weighting toward premium, high-value applications that will have outsized implications for supply chain design and margin capture.
Oil Country Tubular Goods (OCTG) Market
Dynamics and near-term risks
- Trade and regulatory shocks: Recent antidumping and countervailing duty investigations initiated by the U.S. Department of Commerce (April 2026) have already begun to reshape sourcing strategies for OCTG imports. These proceedings can materially alter competitive advantages across suppliers and should be factored into bilateral and long-term contracts.
- Standards and specification updates: The American Petroleum Institute published a new foundational line pipe standard in June 2026, while ISO technical work on casing, tubing and drill pipe remains active. Specification changes tend to produce procurement lag, testing bottlenecks and short-term demand spikes for compliant stock.
- Raw material and pricing volatility: Market data indicate movements in FOB pricing for OCTG on North American terms earlier this year. Even modest per-ton swings feed directly into producer margins and can trigger pass-through clauses in supplier contracts.
- Project-driven concentration of demand: Large upstream awards and regional pipelines create episodic demand concentration that benefits suppliers with scale or local footprint — and penalizes those with longer lead times or single-source exposure.
Competitive landscape — supplier implications
The competitive field combines global integrated steelmakers, specialized tubular manufacturers and regional players with export capabilities. Each archetype brings distinct value propositions and risk profiles that buyers and investors must map to project requirements.
- Tenaris (Buenos Aires, Argentina) — Tenaris’s portfolio emphasizes seamless and welded casing/tubing, premium connections (Hydril®), corrosion-resistant alloys and a growing service layer (Rig Direct®, OCTG Experience workshops). Their dual focus on technology and service enables value capture beyond the transaction, making them a natural partner for operators prioritizing performance and reliability.
- Vallourec (Courbevoie, France) — Vallourec remains oriented toward high-spec seamless carbon steel OCTG and proprietary connection systems (VAM®). Recent contract awards for major energy projects and targeted product deployments demonstrate the company’s ability to convert engineering-led solutions into project wins — a model that favors close integration with EPCs and national oil companies.
- United States Steel Corporation (Pittsburgh, USA) — As an integrated supplier with a domestic manufacturing footprint, U.S. Steel offers seamless and ERW casing/tubing options tailored to U.S. energy demand. Their position is strategically relevant when trade interventions or security-of-supply considerations drive onshore sourcing preferences.
- TMK Group (Moscow, Russia) — TMK’s mix of welded and seamless OCTG, premium connections and international distribution capability positions it well for cross-border projects and markets where long-established relationships and logistics proficiency are decisive.
- Borusan Pipe (Istanbul, Turkey) — Borusan’s core strength lies in welded OCTG solutions and a competitive manufacturing cost base, which supports both regional supply and export-led contracts. For buyers seeking balance between cost and delivery performance, regional players like Borusan are often pivotal.
Recent corporate developments exemplify strategic pathways: a leading supplier’s technical workshops aimed at E&P decision-makers, and significant line-pipe awards tied to offshore developments. Such events are not isolated PR items; they materially influence procurement timetables, specification adoption and local content negotiations.
What the full PW Consulting OCTG report delivers (operative content)
- Validated market-sizing and a five-scenario forecast (2026–2032) calibrated to commodity, capex and policy levers.
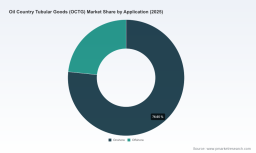
- Demand-by-product and application modeling with sensitivity analyses for pricing, specification shifts and project award cadence (note: detailed splits for region/product/application are available in the full report).
- Supplier landscaping and scorecards — manufacturing footprint, technical capability, premium-connection patents, lead-time maps and financial resilience indicators.
- Procurement playbook — contract templates, hedging approaches for raw-material exposure, SLAs for run-ready deliveries and risk allocation matrices.
- Operational toolkits — inventory optimization algorithms for tubulars, CapEx sizing for consolidation or nearshoring, and a checklist for technical compliance with the latest API/ISO updates.
- Strategic M&A and partnership opportunities — target screening for bolt-on technologies (CRA, premium connections), geographic expansion candidates and JV structures that de-risk market entry.
Strategic imperatives for executive teams in 2026
- Re-price contractual exposure: Incorporate granular indexation and triggers for raw-material movements and trade policy shifts to avoid profit erosion.
- Prioritize supplier segmentation: Classify suppliers by capability (e.g., premium connections, CRA proficiency, service integration) and allocate volumes accordingly — not all suppliers should be treated as fungible.
- Invest in specification governance: Centralize engineering approval and standard-change monitoring to shorten procurement cycles when API or ISO updates come into force.
- Build contingency capacity: Identify near-shore or strategic stock points for critical tubulars to mitigate disruption from trade actions or freight volatility.
- Monetize services: Operators and suppliers that move up the value chain with training, run-ready services and field-engineering capture higher margin pools and reduce total cost of ownership for clients.
- Use M&A as a means to secure technology: Acquihires or minority stakes in premium-connection or CRA specialists can unlock performance differentiation without full-scale greenfield investment.
How to use this preview — and where to go next
This preview is designed as a strategic roadmap for 2026 planning cycles: it signals where the market is heading, what risks are materializing, and which supplier archetypes will be decisive. For procurement leaders, project sponsors and strategic investors seeking executable intelligence, the full PW Consulting OCTG market study provides the underlying data, segmented demand models and supplier scorecards needed to convert insight into contract and investment decisions.
We have deliberately withheld granular regional and application splits in this extract to preserve the commercial value of the underlying models. Accessing the full dataset will enable scenario runs tailored to your specific exposure — whether you are evaluating a Gulf basin development, a North American shale program, or an export-led pipeline project.
Final note — timing matters
Regulatory filings, standard revisions and a handful of large project awards will compress decision windows through 2026. Firms that align procurement, technical governance and commercial strategy now — informed by rigorous market models and supplier intelligence — will convert the OCTG market’s predictable growth into durable competitive advantage. PW Consulting’s full report provides the tools to do exactly that.
For detailed analysis of this topic, please visit the official page: Oil Country Tubular Goods (OCTG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


