



PW Consulting: Tetramethyl Ammonium Hydroxide Market to Expand at 5.2% CAGR Through 2032

Tetramethyl Ammonium Hydroxide (TMAH) Market — Strategic Preview for 2026 Decision-Makers
PW Consulting presents a strategic preview of the Tetramethyl Ammonium Hydroxide (TMAH) market designed to orient executives, investors, and corporate strategy teams as they make high‑stakes decisions in 2026. This briefing synthesizes our market modelling, regulatory mapping, and competitive intelligence into actionable implications, while intentionally withholding detailed segment-level datapoints to encourage stakeholders to consult the full report for transaction‑grade detail.
Tetramethyl Ammonium Hydroxide Market
Why TMAH matters now
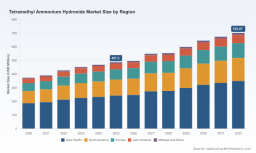
TMAH is a mission‑critical specialty chemical across semiconductor photolithography, display manufacturing, and a range of industrial and laboratory uses. After steady expansion through the early 2020s, our updated market model shows the industry growing from roughly USD 374 million in 2020 to approximately USD 487.3 million in the base year 2025, and continuing on a compound annual growth path of about 5.2% through the 2026–2032 forecast horizon. Under our baseline assumptions, the market nears USD 702 million by 2032.
Tetramethyl Ammonium Hydroxide Market
For 2026 decision cycles, that growth trajectory creates a window where strategic moves — capacity investments, supply‑chain reconfiguration, product differentiation and targeted M&A — can materially alter competitive positioning. But realizing upside requires careful management of three tightly linked vectors: raw‑material exposure, regulatory & safety risk, and product‑quality differentiation for electronic‑grade applications.
Tetramethyl Ammonium Hydroxide Market
Core dynamics shaping 2026 strategy
-
Raw‑material and input volatility. TMAH production is fundamentally linked to trimethylamine feedstocks derived from methanol and ammonia. Historical shocks — notably the 2021 methanol price surge that increased TMAH solution costs and compressed supplier margins — underline the sensitivity of producer economics to upstream commodity swings. Firms with limited input hedging or spot exposure experienced margin erosion during that period.
-
Regulatory and hazardous‑materials overhead. TMAH is classified as highly toxic and corrosive across major jurisdictions. Compliance regimes (including EU REACH SVHC obligations, US TSCA certification, and China’s Dangerous Chemicals regulations) create recurring compliance costs and capex requirements for storage, transport, emergency response and waste treatment. Noncompliance risk or underinvestment in safety infrastructure can lead to operational disruption and reputational damage — a material consideration for buyers and financiers.
-
Policy‑driven demand reallocation. Recent policy moves matter: China’s 2026 Semiconductor Equipment Industry Development Guide explicitly lists electronic‑grade TMAH as a priority and introduces subsidies for downstream purchases of domestic material; parallel public investment — including sizable allocations from a national semiconductor fund — aims to accelerate local R&D and capacity. These interventions create both demand pull and competitive pressure for non‑Chinese suppliers and influence long‑term supplier selection dynamics.
-
Market concentration and competitive dynamics. The TMAH market shows measurable concentration: our analysis indicates the top three players account for roughly 62% of industry sales, and the top five about 68%. This concentration amplifies the strategic importance of relationships with tier‑one suppliers, and makes targeted partnerships, strategic equity stakes, or selective capacity expansion effective levers to secure supply and pricing advantages.
What the full report delivers — practical, transaction‑ready outputs
To translate the dynamics above into executable decisions, the complete PW Consulting TMAH report contains the following operational tools and analyses (summarised here at a headline level):
- Bottom‑up market model (2020–2032) with scenario toggles (base, upside, downside) that drive demand, pricing and margin forecasts suitable for valuation and capex planning.
- Segmented demand forecasts by grade and application plus differentiated pricing curves for electronic, industrial and laboratory grades — available in the full dataset.
- Supply‑chain mapping and concentration heatmaps, including production locations, capacity utilisation, and logistics sensitivity by trade lane.
- Raw‑material cost driver analysis with input cost pass‑through models and recommended hedging mechanisms tailored to common contracting structures in the sector.
- Regulatory impact assessment (EU, US, China and key Asia Pacific jurisdictions) identifying compliance capex, certification timelines, and probable inspection risk points.
- Supplier and customer scorecards — financial health, quality certifications, production tech, and compliance track records — to support vendor selection and due diligence.
- M&A playbook and valuation comparables for buyers and sellers, including synergies from vertical integration (e.g., ammonium sourcing, on‑site chemical recycling) and bolt‑on opportunities in wet‑chemicals for semiconductor fabs.
- Operational checklists for safe handling, storage and disposal aligned with international best practice — critical for insurance and financing approval.
Note: this introduction deliberately omits segment‑level market shares and granular revenue splits. The full report contains downloadable tables and interactive models for subscribers and clients.
Competitive landscape — strategic takeaways
Our company intelligence covers global incumbents and regional specialists. Several observations are pivotal for 2026 strategy:
-
Incumbents with electronic‑grade focus enjoy structural advantages. Producers that combine ultra‑clean production processes with geographically proximate capacity to semiconductor fabs capture premium pricing and lower logistics risk. Investments in chlorine‑free synthesis methods and cleanroom graded operations are differentiators that translate into higher switching costs for downstream fab customers.
-
Regional champions are leveraging policy to scale. Firms with strong domestic positions and localised manufacturing are best positioned to capture subsidy flows and fast follower demand where governments prioritise semiconductor materials. This dynamic is reshaping supplier selection, particularly for large downstream purchasers seeking secure supply under incentivised procurement frameworks.
-
Niche specialists serve high‑margin laboratory and analytical channels. Reagent‑grade and pentahydrate suppliers that target research and analytical markets maintain distinct value pools separated from commodity industrial volumes; these channels remain attractive for companies seeking margin diversification without large incremental capex.
-
Consolidation risk is real but selective. Given current concentration metrics, targeted consolidation — particularly acquisitions that bring electronic‑grade expertise, proprietary processes, or regional footprint — can rapidly shift local market power. However, integration risks (quality harmonisation, regulatory alignment) are non‑trivial and must be priced into transaction models.
Strategic options for 2026 — decision frameworks
For executives preparing capital allocation and sourcing strategies this year, we recommend evaluating five near‑term options through a structured decision framework that balances supply security, margin protection and regulatory resilience:
-
Hedge & partner. Negotiate multi‑year offtake contracts with indexed pass‑throughs plus input‑price collars. Combine contractual protection with strategic minority investments in key suppliers to align incentives without full integration.
-
Localise selectively. Where policy subsidies or procurement regimes materially improve economics, consider greenfield or JV options to locate electronic‑grade capacity within incentive geographies — but only after scenario testing for demand concentration and contractual lock‑in.
-
Differentiate on quality and services. For suppliers: move up the value chain by certifying for the highest grades, offering customised formulations, and providing fab‑level service agreements that include contamination control and emergency response.
-
Verticalise inputs. Integrate upstream where feasible to reduce exposure to methanol/ammonia price cycles — acquisition of trimethylamine capacity or long‑term feedstock contracts can be decisive during commodity shocks.
-
Stress test scenarios. Run decision trees against three plausible 2026‑2028 outcomes: continued steady growth (baseline, ~5.2% CAGR), accelerated domestic substitution driven by policy, and downside stress from trade disruption or raw material shock. Quantify working‑capital demand, cash‑flow timing, and covenant risk for each.
Operational cautions and risk mitigants
Two operational realities consistently undercut strategy execution:
-
Underestimating compliance capex. Many entrants under‑invest in storage, secondary containment, and emergency response, creating latent liabilities that can derail expansion plans and increase insurance costs.
-
Ignoring logistics complexity. TMAH movement requires specialised carriers, packaging and routing to comply with hazardous‑goods rules; failing to secure qualified logistics partners can result in delivery delays and contractual penalties.
Mitigants include long‑lead procurement of compliant infrastructure, third‑party logistics partnerships with hazardous‑materials specialisation, and explicit contract clauses allocating responsibility for transport and storage compliance.
Next steps for 2026 decision‑makers
PW Consulting’s full TMAH report is structured to move teams from awareness to action: it couples rigorous market models (2020–2032) with supplier scorecards, regulatory playbooks, and financial templates for both organic and inorganic growth paths. For firms evaluating capex in 2026, or planning supplier selection and risk management programs, the report provides the scenario outputs and deal‑level artefacts needed for board‑level approvals and lender diligence.
If your 2026 strategic plan requires securing electronic‑grade supply, sizing a manufacturing investment, or assessing acquisition targets, the full dataset and advisory support will reduce execution risk and compress the decision cycle. This preview highlights the levers; the comprehensive intelligence pack delivers the transactional detail.
How to proceed
Access to the full report and the interactive models is available through PW Consulting. The detailed segmentation, regional allocation, price curves and downloadable forecasts are intentionally gated — they are provided to clients and subscribers to ensure decision‑grade confidentiality. Engage with our team for a tailored briefing and scenario run‑through calibrated to your company’s exposure and strategic ambitions.
For detailed analysis of this topic, please visit the official page: Tetramethyl Ammonium Hydroxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


