



PW Consulting: Tool Steel Market to Reach USD 9.94 Billion by 2032 at 6% CAGR

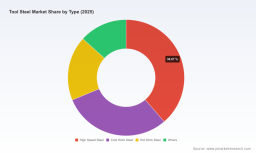
Tool Steel Market — Strategic Brief for 2026 Decisions
As Pw Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused, action-oriented introduction to our Tool Steel Market study. This brief translates the study’s core macro signals into concrete decision levers for executives preparing strategy, investments, and operations in 2026. It demonstrates the analytical depth of the full report while intentionally preserving the detailed segment-level outputs—so your team will know what to test and where to deploy capital, but will need the full report to execute with precision.
Executive snapshot: What the macro facts tell you
- The tool steel market demonstrates a durable recovery and steady expansion trajectory. Using 2025 as the base year, our historical series (2020–2025) and forward-looking forecast (2026–2032) show a consistent compound annual growth rate of roughly 6.0% through the forecast horizon.
- Measured on the aggregate level, the market has grown from the mid-single-digit billions in 2020 to a stronger position in 2025, and our baseline forecast reaches a near-ten-billion-dollar scale by 2032. This trend signals both steady end-demand and structural drivers that support multi-year investment horizons.
- Market structure is neither a pure commodity nor a highly concentrated oligopoly. Our concentration metrics (CR3 ≈ 30%; CR5 ≈ 45%) indicate a moderately fragmented landscape where leading producers hold meaningful scale advantages but sizeable value remains with regional and specialized players.
Why this study matters for 2026 strategic decisions
2026 will be a pivot year for tool steel participants for three reasons. First, secular demand drivers—industrial electrification, higher-performance mobility components, and continued automation of manufacturing—are transitioning procurement and product roadmaps from cost-centric to performance- and sustainability-centric criteria. Second, supply-side forces such as alloy innovation, recycling economics, and capacity rationalization are consolidating margins and reshaping negotiating power. Third, the 6% CAGR baseline creates a planning envelope that makes moderate-capacity and capability investments viable—but only if directed at the right subsegments and geographies.
In practical terms, this report converts those macro realities into decision-ready outputs: supplier-scorecards for procurement negotiations, capex scenarios tied to demand elasticity assumptions, product roadmaps aligned with alloy innovation timelines, and M&A playbooks that prioritize integrability and margin expansion. The depth of the analysis supports both defensive moves (securing feedstock, hedging alloy premiums) and offensive plays (new high-value grades, downstream integration into tooling and service).
Key strategic implications across the value chain
- Procurement and input risk management — The predictable growth envelope enables procurement to move from ad hoc spot buys to multi-year sourcing frameworks. The report provides tooling for quantifying exposure to alloy-cost volatility and for structuring forward contracts and recycling partnerships to reduce earnings variability.
- Capacity and footprint planning — With the market expanding forecasted through 2032, capacity expansion should be calibrated to grade complexity rather than sheer volume. Our scenario models show greater ROI when investments target advanced high-speed and specialty grades or near-market finishing capacity versus undifferentiated long products.
- R&D and product strategy — Prioritizing development in machinability, wear resistance, and heat-treatment compatibility yields outsized commercial payback. The study outlines timing windows where incremental composition improvements unlock premium pricing in tooling applications.
- Commercial and go-to-market — Sales and service capabilities (engineering support, remanufacturing, field trials) are decisive in capturing premium segments. The full report includes commercial playbooks for converting engineering relationships into recurring revenue streams.
- M&A and partnership screening — The market concentration metrics suggest fertile ground for bolt-on acquisitions that bring differentiated technologies, regional market access, or downstream customer intimacy. We provide a scoring matrix to prioritize targets based on technology fit, cultural integration risk, and immediate margin accretion potential.
- ESG and circularity — Material lifecycle economics improve under tighter recycling loops and alloy standardization. The study quantifies potential cost offsets from reclaimed alloy streams and recommends contractual constructs to share upside across the value chain.
Competitive landscape — how to read today’s leaders
The full competitive analysis maps capability clusters and strategic postures rather than repeating commoditized product lists. Below are concise strategic profiles of three incumbent players that exemplify distinct competitive models featured in the study.
- Proterial, Ltd. (Tokyo, Japan) — A specialty tool steel manufacturer with a portfolio that includes grades for cold working molds, high-speed cutting, hot-work dies, and precision blades. Proterial’s strengths are deep material expertise for high-performance tooling and a value proposition focused on application-specific alloy solutions. Strategically, competitors and customers should watch for how Proterial converts specialty-grade know-how into system-level services (tooling design partnerships, aftermarket optimization).
https://www.proterial.com - voestalpine High Performance Metals (Vienna, Austria) — Operating globally under recognized brands, voestalpine combines a broad product set for hot, cold, and high-speed applications with distribution reach. Its playbook centers on brand-enabled premiumization and integrated supply chains. For challengers, the strategic question is whether to compete on breadth or double-down on niche specializations where technical entry barriers are higher.
https://www.voestalpine.com - Hitachi Metals, Ltd. (Tokyo, Japan) — Known for advanced grades for molds and dies, Hitachi Metals has historically invested heavily in alloy innovation and quality control. Its strategic footprint is strongest where precision and reliability matter most—high-value tooling and components. Competitors should note that R&D-led differentiation remains a durable moat if paired with commercial scale.
https://www.hitachi-metals.com
Collectively, these companies illustrate the two primary axes shaping industry competition in 2026: technological depth (grade and process innovation) and go-to-market scale (distribution, service, and integration). Our report’s competitor matrices translate these axes into playbooks for entrants and incumbents alike.
What the full report contains — practical, operational outputs
The Pw Consulting Tool Steel Market study is engineered for decision-makers. Highlights include:
- Macro demand scenarios (baseline, upside, downside) calibrated to a 6.0% CAGR baseline and stress-tested for recession, raw-material shock, and accelerated electrification vectors.
- Segment-level demand modeling by region, product type, and application—presented as decision rules and allocation levers (note: detailed segment tables are reserved for the full report).
- Supplier and competitor scorecards with standardized KPIs: technology differentiation, margin profile, capacity flexibility, service and aftermarket capability, and integration risk.
- Capex and M&A playbooks including payback thresholds, post-merger integration checklists, and regulatory risk overlays for cross-border deals.
- Procurement tools: hedging calculators, alloy-price sensitivity matrices, and sample contract constructs that align incentives for recycling and long-term supply stability.
- Commercial frameworks for premiumization: price-to-performance maps, customer segmentation logic, and service-bundling approaches that demonstrate margin uplift opportunities.
- Implementation templates: 18‑month milestones, KPIs for a center-of-excellence, and a roadmap for piloting supply-chain and product initiatives in 2026.
How to use this study in your 2026 planning cycle
Here are three concrete use cases the report is designed to support:
- Capital allocation — Use the capex scenarios to stress-test plant expansions and R&D programs under the 6.0% CAGR baseline and alternative demand shocks. The report identifies where incremental capacity delivers margin expansion versus where it dilutes returns.
- M&A targeting — Apply our target-scoring matrix to prioritize acquisition candidates that close capability gaps (e.g., finishing, heat treatment, alloy know-how) rather than simply adding volume.
- Commercial optimization — Implement the supplier scorecards and pricing frameworks to renegotiate customer contracts, introduce value-based pricing for high-performance grades, and build service-based revenue streams.
What we intentionally withhold here — and why
To preserve the strategic value of the full study, this brief purposefully omits the granular segmentation tables and the specific regional/application revenue breakdowns that inform high-precision procurement and M&A bids. Those tables are the operational inputs teams need to size opportunities by geography and application and are available in the full report along with downloadable financial models and scenario files.
Final takeaways
As companies finalize their 2026 plans, the Tool Steel Market offers a clear strategic paradox: the macro growth outlook supports investments, but success will hinge on choosing the right kind of investments—those that emphasize grade differentiation, service integration, and supply-chain resilience instead of volume alone. Pw Consulting’s study equips leaders to make those choices with confidence, providing both the high-level framing and the decision-grade tools needed to act.
For clients and decision-makers ready to convert these insights into immediate action, the full report provides the guarded segmentation data, downloadable models, and implementation templates that convert strategic intent into measurable outcomes. Contact Pw Consulting to access the complete Tool Steel Market study and the supporting decision toolset.
For detailed analysis of this topic, please visit the official page: Tool Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


