



PW Consulting: Chillers Market Set for 4.92% CAGR Through 2032

Chillers Market — 2026 Strategic Preview
Executive snapshot
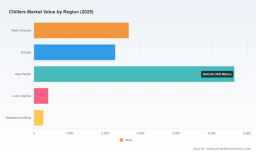
As organizations plan capital allocation and product strategy for 2026, the chillers market is entering a period defined by regulatory acceleration, technology substitution, and concentrated competitive rivalry. PW Consulting’s latest study — anchored on a 2025 base year with historical tracking from 2020–2025 and forward-looking scenarios for 2026–2032 — finds the global market at roughly USD 11.3 billion in 2025, rising to approximately USD 11.95 billion in 2026 and projecting toward USD 15.6 billion by 2032 at a compound annual growth rate of 4.92%. These headline figures frame a market that has already recovered from the pandemic-era trough and is now navigating a structural transition that will determine winners and laggards over the next investment cycle.
Chillers Market
Why this research matters for 2026 decisions
-
Regulatory timing forces strategic choices. Finalized rules in major jurisdictions (notably the U.S. EPA actions and revised EU F-gas rules) set hard dates for low‑GWP adoption and limit the window for selling or installing legacy high‑GWP chillers. For 2026 planning this means procurement teams, product managers, and channel leaders must co‑ordinate to ensure compliance while avoiding stranded inventory and warranty exposures.
Chillers Market -
Hardware innovation is accelerating at the product level. Magnetic‑bearing compressors, two‑stage economized centrifugal designs, inverter screw platforms, and high‑temperature heat‑pump chillers are being commercialized with an explicit focus on data‑center and high‑ambient environments. These technology choices affect total cost of ownership (TCO), use‑case fit, and aftermarket service mixes.
Chillers Market -
Supply chain and trade policy risk are non‑trivial. Expanded tariffs on steel and aluminum derivatives and re‑rated import duties in 2025 increase landed cost volatility. Procurement strategies deployed in 2026 must combine longer blanket contracts, alternative sourcing, and in some cases nearshoring to maintain margin targets.
-
Concentration amplifies strategic moves. The market shows meaningful concentration (top‑three suppliers account for roughly half of industry sales, with the top five approaching a substantial majority). That structure both raises barriers — making scale and service footprint advantages decisive — and creates opportunity for focused challengers in differentiated niches (e.g., low‑GWP retrofits, micro‑data center cooling, or district heat‑recovery integrations).
Market dynamics and the decision calendar for 2026
Executives should treat 2026 as a pivotal execution year rather than a planning buffer. The study maps regulatory milestones (e.g., post‑2025 installation bans and 2027–2032 GWP thresholds) against product roadmaps and channel windows. Practical implications include:
-
Inventory policy: avoid lock‑in to high‑GWP chillers with long lead times; prioritize configurable, refrigerant‑agnostic platforms where possible.
-
Capital expenditures: accelerate pilots of magnetic‑bearing and economized centrifugal systems for high‑density cooling to gather operational data before wide deployment.
-
Service and aftermarket: monetize retrofit opportunities and refrigerant conversion services; 2026 is when retrofit pipelines mature into stable revenue streams for first movers.
-
Pricing strategy: factor in tariff pass‑through and localized production economics; consider hedging material exposure and dynamic price levers tied to contract clauses.
Competitive landscape — what the majors are doing and what it means
The competitive analysis in our report profiles the leading OEMs and highlights how their product portfolios are aligning to the new environment. Key observations:
-
Trane Technologies is pushing screw‑and‑modular platforms and data‑center focused solutions; their emphasis on high‑temperature heat‑pump chillers and modular designs signals a strategy to capture both new‑build and liquid‑cooling conversions.
-
Carrier is leveraging centrifugal AquaForce and AquaEdge lines to maintain strength in large‑scale facilities and hyperscale data centers; their playbook emphasizes efficiency at scale and integrated service contracts.
-
Johnson Controls (YORK) is deploying two‑stage economized designs and magnetic‑bearing models targeted at very high‑density IT loads — a clear bid to own the premium data‑center cooling segment where TCO analysis favors higher upfront over ongoing operational cost.
-
Daikin and Mitsubishi Electric are advancing low‑GWP and high‑ambient performance variants; their global footprint and refrigerant roadmaps make them formidable in regions with early regulatory stringency.
-
Asian manufacturers (LG, Gree, Midea) and regional specialists (Blue Star, Airedale) are focusing on price/efficiency trade‑offs and local channel penetration, with an increasing share of inverter and modular solutions to match diverse project needs.
Recent industry moves underline these trends: in early 2026 Johnson Controls unveiled a two‑stage economized YORK chiller for zero‑water data‑center lift; Daikin previewed large magnetic‑bearing Magnitude units and low‑GWP fan‑deck solutions; Trane launched a high‑temperature heat‑pump screw chiller and an Ascend data‑center platform. These product events are not isolated innovations — they are strategic bets on where demand and regulation intersect.
Practical content of the PW Consulting report (what you will use immediately)
The full study is designed to be operational for product, commercial, and M&A teams working on 2026 initiatives. Key deliverables include:
-
A calibrated market model (2020–2025 actuals, 2026–2032 scenarios) with sensitivity levers for refrigerant policy, tariff shocks, and data‑center growth rates.
-
Regulatory tracker and compliance roadmap mapping by jurisdiction and impact windows to inform procurement and product‑launch timelines.
-
Competitive scorecards and product benchmarking focusing on efficiency, refrigerant flexibility, modularity, and aftermarket service capability.
-
Supply‑chain risk matrix with tariff exposure, single‑sourcing flags, and recommended contingency plans for 12–24 month horizons.
-
TCO and payback calculators customisable by application (e.g., data center, industrial process, commercial building) to support CAPEX approval packages.
-
Go‑to‑market playbooks for retrofit services, OEM partnerships, and district cooling pilot programs designed for rollout in 2026.
How to use these insights in 2026 — an action plan
-
Immediate (0–6 months): perform a refrigerant compliance audit across the installed base; suspend orders likely to be non‑compliant after 2026; prioritize retrofit deals that both meet regulatory timelines and preserve margin.
-
Near term (6–18 months): accelerate product introductions that are refrigerant‑agnostic or use approved low‑GWP blends; pilot high‑value use cases (hyperscale data centers, process cooling) to validate TCO and service models.
-
Medium term (18–36 months): rationalize supplier networks in light of tariff dynamics; pursue strategic partnerships or tuck‑ins to close capability gaps in magnetic‑bearing compressors, controls, or refrigerant conversion services.
-
Board level: use the market concentration and scenario outputs in capital allocation reviews — investments in digital service platforms and retrofit capabilities are likely to yield higher margin resilience than pure volume plays.
Concluding perspective — where the value will be created
Between now and 2032, value creation in the chillers market will be concentrated in three domains: compliant high‑efficiency hardware for mission‑critical cooling, aftermarket and retrofit services that monetize regulatory transitions, and supply‑chain strategies that protect margin against tariff and material volatility. Our forecast pathway — from an estimated USD 11.3 billion in 2025 to about USD 15.6 billion by 2032 at a 4.92% CAGR — hides material heterogeneity by application and geography. Some niches, particularly those tied to rapid data‑center growth, may expand much faster; others will be pressured by substitution and regulation.
PW Consulting’s full Chillers Market report contains the granular, segment‑level forecasts, regional breakouts, and supplier benchmarking required to convert these strategic insights into executable plans. For teams preparing budgets, product roadmaps, or M&A screens in 2026, the report provides the calibrated inputs and playbooks needed to move from uncertainty to decisive action.
For detailed analysis of this topic, please visit the official page: Chillers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


