



PW Consulting: Gypsum Board Market at USD 124.21M in 2025, 3.6% CAGR to 2032

Gypsum Board Market 2026: Strategic Signals for Executives — A PW Consulting Preview
Introduction
As the construction sector recalibrates after a period of uneven demand and supply-side shocks, gypsum board manufacturers, suppliers, and investors face a 2026 decision window that will determine competitive positions for the rest of the decade. PW Consulting’s Gypsum Board Market study (base year 2025, forecast 2026–2032) synthesizes macro trends, competitive moves, raw-material dynamics, regulatory friction points, and near-term demand scenarios into an operational playbook for senior leaders. In brief: the market is on a moderate growth trajectory with a multi-year compound annual growth rate (CAGR) of 3.6%, a clear recovery from mid-cycle softness, and a structurally tight supply environment that will reward proactive strategic responses.
Gypsum Board Market
Market Snapshot — What Every Boardroom Should Know
-
Scale & trajectory: By the 2025 base year the global gypsum board market reached a material size, and our forecast shows a rebound into 2026 followed by steady expansion through 2032. The study’s bottom-line projection reflects the economy-normalization path embedded in our 3.6% CAGR scenario, and alternate scenarios capture downside macro and upside stimulus-driven demand.
Gypsum Board Market -
Concentration & competitive intensity: Market concentration is meaningful — the top three and top five players control a clear majority of value and channel access. This concentration creates both risks (supply-side pricing power, rapid technological diffusion among incumbents) and opportunities (consolidation arbitrage, differentiated service models for niche channels).
Gypsum Board Market -
Volatility signals: The market experienced a transient contraction in the mid‑decade before rebounding into 2025. Near-term year‑to‑year oscillations are expected as quarry production, construction cycles, and trade flows adjust; our scenario work identifies the inflection points that matter to procurement, manufacturing footprint decisions, and portfolio rebalancing.
Why This Study Matters for 2026 Decisions
-
Capital allocation under uncertainty: Board-level capital planning for 2026 must weigh incremental capacity investments against raw-material supply risks and regulatory headwinds. Our analysis quantifies margin sensitivity to raw gypsum availability and transport costs and models the payback profiles of brownfield versus greenfield investments under three macro paths.
-
Product and channel prioritization: As developers and contractors demand faster installation cycles, improved fire and moisture performance, and lower embodied carbon, firms need a clear evidence base to prioritize R&D and SKU rationalization. The report maps demand elasticities and margin pools by performance attributes — enabling go/no-go decisions for premium product rollouts and retrofit segments.
-
M&A and partnership targets: With the market’s top-tier firms holding dominant shares, mid-market players should consider bolt-on acquisitions and regional alliances to close distribution gaps and capture underserved niches. Our M&A playbook grades targets not only by revenue and cost synergies but by integration risk and regulatory exposure.
-
Regulatory and circularity trade-offs: Recycling pathways and beneficial-use approvals are uneven across jurisdictions. The study provides a regulatory risk matrix that helps firms decide whether to invest in recycling technology, pursue local beneficial-use approvals, or adjust procurement strategies to mitigate disposal liabilities.
What the Report Contains — Practical, Executable Intelligence
-
Executive dashboard: Clear KPIs and scenario outputs for 2026 board deliberations, including cost curves, margin sensitivity, and break-even analyses for capacity options.
-
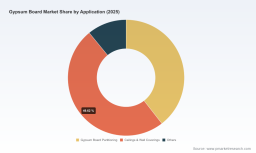
Demand scenarios and segment playbooks: Segmented demand forecasts (historical 2020–2025 baseline plus 2026–2032 projections) and practical recommendations for product, application, and channel prioritization. Note: while the report contains the full granular segmentation, this preview intentionally omits detailed regional and application-level numbers to preserve the study’s proprietary value.
-
Supply-chain heatmap: Spatial analysis of quarry access, transport bottlenecks, and plant-level utilization across primary markets, with recommended near-term logistics hedge strategies.
-
Regulatory impact guide: Jurisdictional summaries and actionable steps to address recycling approvals, specification changes, and procurement rules that influence product acceptance in public and large-scale projects.
-
Competitive intelligence pack: Profiles and strategic assessments for leading manufacturers, distribution channels, and modular system integrators — calibrated for immediate use in vendor selection and negotiation planning.
-
M&A and investment playbook: Identification of value-creation levers, synergies, earn‑out structures, and integration checklists for transactions designed to scale channel access or add differentiated product lines.
Competitive Landscape — Positioning and Strategic Moves
The competitive field is shaped by legacy manufacturers with integrated gypsum sources, growing regional champions, and strategic newcomers focused on specialty performance and circularity. Our proprietary company assessments synthesize product mix, manufacturing footprint, brand strength, and recent strategic moves.
-
USG Corporation (Chicago, Illinois, USA) has doubled down on raw-material control and recently expanded gypsum supply capacity to secure feedstock for board manufacturing. This move reduces feedstock exposure and supports predictable cost curves for core product lines.
-
Knauf (Iphofen, Germany) continues to push product performance through regional R&D hubs and locally tailored launches aimed at humidity- and fire-sensitive applications, reflecting a playbook that combines global platforms with regional customization.
-
Saint-Gobain Gyproc (Paris, France) maintains a portfolio strategy focused on acoustic and specialty products for multi-family and high-end residential — a defensive position that preserves margins in mature markets.
-
National Gypsum, CertainTeed, American Gypsum, Etex, Boral, and Yoshino are executing differentiated strategies ranging from premium productization to cost leadership and regional consolidation. Their public moves in product launches and pricing actions signal tactical responses to raw-material and labor cost pressure.
Recent Signals That Should Shape 2026 Plans
-
Product innovation and recognition: Recent product launches and awards underscore the market premium available to differentiated, performance-led boards. Firms considering premium entries should evaluate channel readiness and contractor acceptance timelines carefully.
-
Supply anchoring by incumbents: Strategic capacity and quarry investments by leading players are reducing raw-material vulnerability for those firms, increasing the competitive pressure on less vertically integrated competitors.
-
Regional raw-material supply trends: National-level gypsum production and consumption patterns point to tightening availability in certain markets. Procurement teams must build scenario plans for feedstock substitution, alternative sourcing, or temporary inventory cushions.
-
Pricing and labor dynamics: Recent price adjustments and labor-driven cost pass-throughs indicate that manufacturers with flexible cost structures and differentiated value propositions will have the upper hand in 2026 contract negotiations.
Risk Factors & Early Warning Indicators
-
Regulatory friction on recycling: In major urban jurisdictions, recycling approvals face technical constraints that can create unexpected disposal costs. Firms should monitor rulemaking closely and engage with regulators early to accelerate beneficial-use certifications.
-
Raw gypsum availability: Quarry production variability and aggregate consumption trends serve as leading indicators of margin pressure. Our report provides monitoring thresholds that trigger procurement playbooks.
-
Contractor adoption lags: Even high-performance composites require time to gain specification traction. Pilots, performance documentation, and contractor incentives reduce time-to-adoption risk.
Recommended Strategic Moves for 2026
-
Secure feedstock and logistics before expanding capacity — opt for phased capacity plans tied to clear feedstock delivery contracts and documented milestone triggers.
-
Prioritize a two-track product strategy: defend core margins with optimized standard SKUs while selectively investing in high-margin performance boards where specification windows and contractor training can be accelerated.
-
Accelerate regulatory engagement relevant to recycling and beneficial-use approvals — effective engagement shortens commercialization timelines for recycled-content products and reduces disposal risk.
-
Pursue targeted M&A or JV transactions that close channel gaps and add low-cost regional production, rather than trophy assets that increase integration complexity.
Conclusion — The Strategic Value of This Study
PW Consulting’s Gypsum Board Market study is designed to be a decision accelerator for 2026. It combines a rigorous market-size base, scenario-driven forecasting, supply-chain diagnostics, regulatory risk assessment, and a competitor playbook to help executives make timely, high-confidence choices. While this preview outlines the major directional insights, the full report contains the granular segmentation, regional breakdowns, and model outputs that are essential for transaction diligence, plant-level planning, and procurement contracting. For boards and senior leadership teams planning capital allocation, M&A, product launches, or procurement hedges in 2026, the study translates market complexity into prioritized actions and measurable KPIs.
PW Consulting invites industry leaders to review the complete report package for the detailed forecasts, regional and application splits, supplier scorecards, and the executable 90‑day action plan that accompanies the study.
For detailed analysis of this topic, please visit the official page: Gypsum Board Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


