



PW Consulting: Masterbatch Market to Hit USD 20.22B by 2032 at 5.5% CAGR

Masterbatch Market 2026: Strategic Imperatives for Decision-Makers
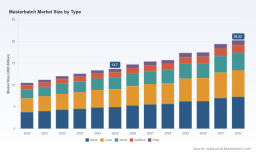
As companies prepare strategy and capital allocation decisions for 2026, the masterbatch market is no longer a background input — it is a strategic lever. PW Consulting’s forthcoming Masterbatch Market study frames that lever with a data-driven roadmap: the market expanded materially through the early 2020s, reached approximately USD 13.7 Billion in our 2025 base year, and under the operating scenarios in this study we expect continued expansion through 2032 to roughly USD 20.2 Billion. Our core forecast (2026–2032) implies a steady mid-single-digit CAGR of 5.5%, but beneath that headline growth are differentiated opportunities, regulatory inflection points and supply-side constraints that will determine winners and losers in the next three to five years.
Masterbatch Market
Why this study matters for 2026 decisions
-
Investment prioritization: With a market poised for durable growth, C-suite and corporate development teams must choose whether to expand capacity, pursue bolt‑on M&A, or buy innovation through partnerships. Our study quantifies market trajectories at the aggregate level and translates them into investment break‑evens under alternative raw‑material and regulatory scenarios.
Masterbatch Market -
Product and portfolio strategy: Masterbatches sit at the intersection of polymer chemistry, formulation know‑how and customer‑facing value propositions (color, functionality, recyclability). The report converts demand trends into a pragmatic product prioritization matrix that helps R&D and commercial teams decide where to push premiumization, where to optimize for cost and where to pursue circular formulations.
Masterbatch Market -
Risk and supply‑chain resilience: Volatility in feedstock markets and uneven upstream capacity additions introduce material risk. Our supply‑chain stress tests and hedging templates equip procurement and treasury teams to model margin sensitivity to feedstock swings and to design procurement strategies that balance cost, availability and ESG requirements.
What the report delivers — practical, actionable outputs
-
Market sizing and scenario forecasts (base year 2025; historical 2020–2025; outlook 2026–2032) with three demand scenarios and a probabilistic central case suitable for budgeting and strategic planning.
-
Segmentation-ready decision tools: while this introduction intentionally highlights the aggregate trajectory, the full report provides granular splits across product types, polymers and regions, together with interactive dashboards for bespoke slicing and sensitivity analysis.
-
Price and margin modelling: templates that translate raw‑material price trajectories into unit margin and EBITDA implications across typical masterbatch formulations.
-
Regulatory impact assessments: scenario frameworks that quantify compliance cost and product redesign needs under evolving EU and global standards.
-
Competitive landscaping and capability maps: benchmarking of technology, capacity footprint, sustainability credentials and go‑to‑market models across global suppliers.
-
M&A playbook and target identification: shortlists of strategic targets by capability and geography, valuation benchmarks and integration risk checklists tailored to corporate acquirers and private equity sponsors.
-
Operational levers: manufacturing footprint optimization, carbon and circularity pathways, and a rapid implementation plan for standardization of pigments and masterbatch dosing to reduce complexity and cost.
Market dynamics shaping 2026 strategy
-
Regulatory acceleration: The tightening of plastics regulation (notably extended producer and packaging requirements) is pushing brand owners and converters to demand higher recycled content and better recyclability from masterbatch suppliers. Targets that mandate significantly higher recycled content by 2030 and beyond mean that companies will need validated circular solutions rather than ad‑hoc substitutes.
-
Raw‑material and cost structure pressures: Feedstock cost oscillations have been a structural theme. High polymer prices in the recent period increased the urgency for cost‑saving formulations and for filler technologies that materially reduce virgin polymer loadings. Our modelling shows certain filler masterbatches can deliver double‑digit percentage reductions in raw material spend in specific applications — an operational advantage that can be translated into either margin or price leadership.
-
Standardization and quality assurance: International standards introduced in 2025–2026 for pigment dispersion and masterbatch testing have raised the bar for supply‑chain traceability and analytical capability. Compliance with these standards is not only a regulatory checkbox but also a reputation and quality differentiator for converters and brand owners.
-
Market concentration and competitive intensity: The report documents a market structure in which the top three global players account for a clear majority of market share, and the top five command an even larger share. That concentration creates both barriers and focal points for partnership: large players can offer scale, technical centers and integrated product lines; mid‑sized specialists can compete on agility, niche formulations and closer OEM ties.
Competitive landscape — capability and strategic implications
The study examines the strategic positioning of the leading participants and how their capabilities translate into commercial outcomes. Key profiles and takeaways include:
-
Ampacet Corporation — a global leader in custom color and additive masterbatches. Ampacet’s strength is its deep application engineering capability and broad portfolio across color, functional additives and recycling‑oriented solutions. Recent new product introductions underline a continued focus on circularity and differentiated functionality; for buyers, Ampacet represents a reliable partner for high‑value, customized solutions but at a premium price point.
-
Avient Corporation — a supplier that combines solid color masterbatches with color/additive hybrids and recycled‑resin solutions. Avient’s strategy blends product breadth with sustainability credentials, positioning it well for packaging customers who require recycled content and consistent coloration at scale.
-
Cabot Corporation — notable for its specialty black masterbatches and conductive compounds, and for early commercial circular black masterbatches made from recovered feedstock. Cabot’s technical depth in carbon‑based masterbatches gives it a defensible niche in high‑performance and conductive applications.
-
LyondellBasell — with offerings designed for PET packaging and a focus on processing innovation, LyondellBasell competes on polymer integration and supply security. Their capability to tailor masterbatches to specific polymer processing windows is a competitive advantage for converters seeking throughput and efficiency gains.
-
BASF — leveraging its chemical R&D credentials, BASF provides a range of color and additive masterbatches, including products positioned for sustainability and ecological applications. For corporates, BASF’s scale and materials science depth make it a partner for premium, regulatory‑forward product programs.
These strategic profiles imply differentiated routes to market: scale and integration versus specialization and fast innovation. The full report pairs these qualitative assessments with our quantitative benchmarking to identify potential white spaces, capability gaps and likely targets for acquisition or partnership.
Recent developments and near‑term signals
-
New product activity: Market incumbents continue incremental innovation; for example, a major supplier recently launched a scavenger product that has been recognized in industry awards for recycling and stabilization performance — an illustration of the quality and sustainability‑driven incremental innovation that will continue to define supplier selection.
-
Industry engagement and visibility: Regional trade shows and industry exhibitions in 2026 have been important venues for suppliers to showcase circular formulations and to demonstrate manufacturing and testing capabilities; these venues are also where converters validate performance claims before adoption.
Strategic playbook for 2026 — five priority moves
-
Make circularity a product development KPI: Set measurable targets for recycled content and validated recyclability in priority SKUs. Use the report’s circularity templates to cost and performance test formulations before committing capital.
-
Hedge feedstock exposure: Implement a mix of spot, forward and strategic supply partnerships for critical pigments and fillers. Our margin sensitivity models show the difference in profitability under various hedging mixes.
-
Identify high‑ROI capacity investments: Prioritize upgrades that reduce batch changeover time and improve dispersion testing capabilities — investments that yield faster time‑to‑market for custom colors and lower scrap rates.
-
Pursue targeted M&A or JV activity: Consider bolt‑on acquisitions to fill technical gaps (e.g., conductive masterbatches or CaCO3‑based filler technologies) or joint ventures to secure recycled feedstock streams.
-
Commercialize quality and standards compliance: Turn compliance with new pigment‑dispersion and masterbatch standards into a commercial differentiator — i.e., guaranteed dispersion certificates, traceable raw‑material provenance and lifecycle claims that hold up to auditor scrutiny.
How PW Consulting’s Masterbatch Market study supports execution
This study is intentionally operational. Beyond headline sizing and a central CAGR projection, we provide scenario tools, unit economics models and a prioritized action matrix that can be put into motion immediately. For executives needing quick answers, we summarize tactical recommendations tied to P&L outcomes and investment timelines; for teams leading business transformation, we provide the layered analysis and implementation checklists required to execute at scale.
We have deliberately kept this introduction at the macro level — showcasing the strategic insights and decision frameworks that matter for 2026 while reserving the full segmentation, granular regional and application‑level data for the complete report. For procurement directors, R&D leads, M&A teams and CEOs who require the underlying model, full segment breakdowns and interactive dashboards, the full Masterbatch Market study supplies the detailed evidence base to inform and justify high‑stakes decisions.
Contact PW Consulting to access the full report, interactive models and a bespoke briefing tailored to your company’s positioning in the masterbatch value chain.
For detailed analysis of this topic, please visit the official page: Masterbatch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


