



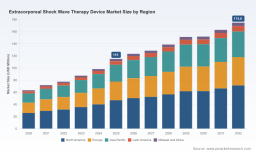
PW Consulting: Extracorporeal Shock Wave Therapy Market to Hit USD 174.8M by 2032 at 5.9% CAGR

Extracorporeal Shock Wave Therapy Device Market: Strategic Imperatives for 2026 Decision‑Makers
Between 2020 and 2025 the global extracorporeal shock wave therapy (ESWT) device market recorded sustained expansion, with market value more than doubling from the early decade baseline to an established mid‑market scale by the 2025 base year. Our forward view—spanning 2026–2032—anticipates a continuation of that expansion at a compound annual growth rate (CAGR) of 5.9%, underpinned by technology diffusion, broadened clinical adoption and evolving service models. This executive preview outlines why PW Consulting’s full market study is a strategic asset for executives planning investments, product launches, or partnerships in 2026, while deliberately preserving the granular segmentation tables and numeric splits that form the core intelligence in the full report.
Extracorporeal Shock Wave Therapy Device Market
Why this study matters now
-
Timing: 2026 is a pivotal year—manufacturers are introducing next‑generation platforms, professional societies are revising guidance, and payers are updating coding and coverage stances. The convergence of these forces means decisions made today determine market access and commercial momentum for the next five years.
Extracorporeal Shock Wave Therapy Device Market -
Clear growth trajectory: The market has demonstrated durable growth through 2025 and our model projects steady enlargement through 2032. This creates opportunity for both incumbent premium vendors and agile challengers that can control cost‑to‑serve or unlock new clinical use cases.
Extracorporeal Shock Wave Therapy Device Market -
Regulatory and reimbursement inflection points: ESWT sits at the intersection of medical device regulation and payer evidence demands. As of early 2026, notable payers maintain investigational status for certain musculoskeletal indications, and regulatory frameworks continue to treat ESWT devices as subject to high‑scrutiny pathways. These realities materially affect go‑to‑market sequencing, clinical trial design and pricing strategies.
What the full report gives you (practical, action‑oriented modules)
-
Proprietary market model (USD, revenue unit: Million) with historical 2020–2025 calibration and scenario forecasts for 2026–2032, including sensitivity and Monte Carlo runs to stress test key assumptions.
-
Segment strategy playbooks: commercial positioning options for device types and clinical applications, evidence requirements by payer archetype, and pricing levers for differing sales channels (hospital capital, clinic lease, distributor models).
-
Regulatory and reimbursement navigator: a country‑level matrix of submission pathways, common clinical endpoints accepted by regulators, and recommended dossier contents to accelerate coverage reviews.
-
Clinical evidence mapping and trial design guidance: prioritized endpoints, comparator selections, sample size envelopes and timelines calibrated for reimbursement dossiers.
-
Competitive intelligence suite: vendor profiles, technology capability maps, go‑to‑market plays, M&A targets scored on commercial and clinical complementarities (note: the full report contains detailed share and revenue splits by segment).
-
Commercial readiness and adoption playbooks: sales training curricula, ROI calculators for hospital procurement committees, and suggested post‑sales clinical support programs to drive utilization.
Market dynamics through a 2026 lens
Three practical forces will shape decisions in 2026:
-
Clinical momentum versus evidentiary friction: Clinicians increasingly prefer non‑invasive and outpatient therapies. At the same time, major payers continue to require stronger real‑world evidence for routine reimbursement in several indications, and some codes retain investigational language—pressuring suppliers to build robust value dossiers rather than rely solely on device performance claims.
-
Regulatory scrutiny and product differentiation: Devices are subject to rigorous regulatory pathways in key markets. Vendors that combine technical differentiation (energy delivery modes, focal depth control, multi‑modality platforms) with well‑documented safety and efficacy in targeted indications will gain privileged access to high‑value customers.
-
Market structure and pricing pressure: Market concentration metrics indicate a fragmented competitive landscape. Fragmentation creates opportunity for smart entrants and contract manufacturers but also drives price competition in commoditizing segments; successful players will balance hardware innovation with services and consumables to protect margins.
Competitive landscape—what to watch
Our qualitative review of leading vendors identifies distinct strategic postures and tactical plays that will influence market shares and partnership opportunities in 2026:
-
Storz Medical AG (Germany): Continues to invest in platform evolution—recent product introductions emphasize deeper energy penetration and multi‑wave capability for musculoskeletal and urological indications. Their playbook blends high‑end systems with clinical training programs to defend premium segments.
-
Zimmer MedizinSysteme GmbH (Germany): Leverages integration with orthopedic instruments and rehabilitation workflows, positioning focused‑wave systems as therapeutic complements for pain and circulation enhancement in orthopedics.
-
EMS Electro Medical Systems S.A. (Switzerland): Known for radial devices targeting musculoskeletal care; their brand equity in physiotherapy networks is a commercial advantage for adoption in outpatient settings.
-
BTL Industries (Czech Republic): Emphasizes portability and physiotherapy‑oriented solutions, pursuing clinic chains and ambulatory care networks that prioritize throughput and lower capital intensity.
-
Dornier MedTech GmbH (Germany): Focused on urology and erectile dysfunction indications as well as musculoskeletal therapy; cross‑indication presence supports diversified revenue streams.
-
MTS Medical AG, Gymna (Belgium), Richard Wolf GmbH and Longest Medical (China): Each pursues particular niches—clinical focus, service models, or lower‑cost offerings. Chinese and other low‑cost entrants are intensifying price competition in commoditized segments.
-
Medispec Ltd. (Israel): Active in both orthopedic and sexual health applications; recent trade show participation demonstrates ongoing investment in clinician engagement and international distribution.
Recent field signals—product launches and congress participation in 2026—underscore an intensifying commercial push. Manufacturers are not just refreshing hardware; they are expanding clinical support and evidence generation efforts to address payer concerns.
Strategic implications: four actionable scenarios
-
Accelerated clinical acceptance: If payers relax investigational status in key musculoskeletal codes, premium devices and bundled service offerings will capture rapid share. Recommendation: prioritize high‑quality registry programs and targeted randomized evidence to trigger coverage policy changes.
-
Reimbursement stagnation: If investigational stances persist, adoption will favor cash‑pay elective and clinic‑level treatments (e.g., aesthetics, outpatient rehab). Recommendation: develop consumer finance options and DTC education while controlling unit economics.
-
Commoditization pressure: Increased supply from low‑cost vendors compresses device margins. Recommendation: shift to recurring revenue models—disposables, software, service contracts—and make clinical outcomes a differentiation tool.
-
Premium innovation premium: Vendors that combine multi‑mode energy profiles with validated outcomes in higher‑margin indications (urology, selected orthopedics) can sustain price premiums. Recommendation: invest selectively in pivotal trials and strategic clinical partnerships.
How to use this intelligence in 90–180 days
-
For executives: Reweight your product roadmap to prioritize features that accelerate payer acceptance (patient‑reported outcomes, durable improvements) and align R&D milestones to reimbursement timelines.
-
For commercial leaders: Rebuild the sales cadence to include clinical liaisons, outcome dashboards and post‑sales utilization analytics—tools that organ procurement and hospital committees now expect.
-
For investors and M&A teams: Screen targets using our M&A scorecard that weights clinical evidence, distribution access, and service‑based revenue potential—criteria that predict multiple expansion in a fragmented market.
-
For regulatory and reimbursement teams: Begin early payer engagement with real‑world evidence plans and prepare modular regulatory submissions tailored to regional expectations.
PW Consulting support and next steps
PW Consulting’s full ESWT market study provides the complete numerical backbone—detailed segment shares, country‑level forecasts, device‑type trajectories and unit economics—that operational teams need to execute the scenarios above. We intentionally hold the granular splits in the full report to ensure subscribers receive the proprietary, transaction‑grade intelligence required for confident decision‑making.
-
If your immediate need is tactical: we offer a 4‑week “Go‑to‑Market Readiness” engagement that extracts targeted slices of the model, produces a payer engagement memo, and delivers a prioritized trial design for coverage submissions.
-
For investors: our M&A readiness package includes valuation sensitivity analyses, a competitive landscape deep dive, and an integration playbook for rapid scale‑up.
To convert growth potential into market leadership in 2026, organizations must pair product excellence with rigorous evidence generation, payer engagement and adaptive commercial models. PW Consulting’s full study equips teams with the data, scenario workstreams and tactical templates required to move from hypothesis to execution. Access to the report’s detailed segmentation, country forecasts and vendor share matrices is available on our research portal for subscribers and qualified purchasers.
For detailed analysis of this topic, please visit the official page: Extracorporeal Shock Wave Therapy Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


