



PW Consulting: High Performance Alloys Market to Reach USD 16,560M by 2032 at 5.31% CAGR

High Performance Alloys Market 2026: Strategic Preview for Executive Decision-Making
As PW Consulting’s Senior Strategy Advisor, I present a focused preview of our High Performance Alloys (HPA) Market research — a study designed to convert complex metallurgical dynamics into clear, executable choices for 2026. The HPA sector is transitioning from recovery-driven growth to a structurally different industry shaped by advanced aerospace programs, electrification, supply‑chain realignment, and raw‑material stressors. This preview is intended to demonstrate the analytical depth of our work while reserving the full segmentation and proprietary modelling for subscribers to the full report.
High Performance Alloys Market
Market snapshot: growth trajectory and what it means for 2026
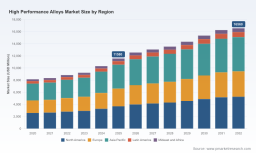
Following a steady recovery in the early 2020s, the global high performance alloys market reached an inflection in 2024–2025 and, on the backbone of aerospace revitalization, energy transition projects, and next‑generation transport programs, registered a strong base by the report’s 2025 baseline. Our analysis shows the market is growing at a compound annual growth rate (CAGR) of approximately 5.31% over the 2026–2032 forecast horizon. Put practically: executives should plan around a multiyear expansion path that moves the industry from a solid mid‑market base in 2025 to materially larger demand pools by the early 2030s. This sustained growth changes how capital is allocated across sourcing, inventory, certification, and capacity planning.
High Performance Alloys Market
Key demand and supply dynamics shaping 2026 decisions
- Aerospace and advanced mobility remain primary growth engines. Programs requiring elevated temperature resistance, fatigue strength and long life cycles — including hypersonic and next‑generation jet engines — underpin demand for specialized nickel‑ and cobalt‑based alloys.
- Material cost volatility is an operational risk. Nickel and cobalt prices have been notable inputs to producer cost models; recent market movements (observed through 2026) have created narrow windows where forward buying or hedging materially improves margin predictability.
- Regulatory and certification friction is a gatekeeper. Aerospace certification and environmental production standards add long lead times and meaningful incremental costs for new grades or new suppliers. These compliance costs should be reflected in project gating and ROI calculations.
- Manufacturing modality shift — powders and AM are strategic inflection points. Powder metallurgy and additive manufacturing (AM) alloys are moving from niche to critical for complex geometries and weight reduction targets; materials suppliers who certify powders for AM create differentiated customer lock‑in.
- Supply base fragmentation creates consolidation opportunity. The sector is moderately concentrated: incumbent technical leaders coexist with agile niche specialists. This structure favors selective M&A, joint‑ventures for capacity, and pay‑for‑performance supply agreements.
Competitive landscape — strategic implications from leading players
Our report analyzes company strategies across product development, customer qualification pipelines, geographic reach, and supply resilience. Highlights follow as directional insights rather than exhaustive profiles (full company scorecards and capability matrices are in the complete report).
High Performance Alloys Market
- High Performance Alloys, Inc. — A U.S. producer/distributor focused on small‑to‑medium lot high‑temperature, wear‑ and corrosion‑resistant alloys. Their agility in short‑run orders and distribution networks makes them a preferred partner for specialized engineering applications and aftermarket parts. For OEMs and Tier‑1s, they are a fast source for qualification runs and prototype materials.
- Special Metals Corporation — A technology‑led organization with deep ownership of industry‑standard alloy families (nickel & cobalt bases). Their strength is in certified alloys for extreme environments, long‑term supply contracts, and close OEM relationships, especially in aerospace. Competitive responses should assume Special Metals will defend certification pipelines aggressively.
- Alleima — A materials innovator emphasizing advanced stainless and high‑temperature grades, with recent product launches that explicitly target sustainable energy and aerospace thermal protection. Their strategy signals an intent to capture upstream value by pairing alloy innovation with industry certification and sustainability narratives.
- VDM Metals — A specialist in nickel‑based alloys for corrosive/high‑temperature processes. Their European base, technical depth, and process know‑how make them a go‑to supplier for energy and chemical processing segments where corrosion resistance is mission‑critical.
- voestalpine High Performance Metals Division — Large‑scale capabilities in tool steels and nickel‑base alloys, with strong integration into automotive and industrial supply chains. Their scale and downstream relationships create barriers for new entrants targeting volume segments.
Recent industry actions — including Alleima’s new high‑strength and high‑temperature alloy launches (2025) and advanced powder metallurgy introductions for hypersonic applications in early 2026 — illustrate two strategic trends: (1) product launches are being designed around sustainability and thermal protection, and (2) powder/AM readiness is shifting from laboratory validation to commercialization. For buyers and competitors, this demands a fast response in qualification timelines and R&D partnerships.
Practical contents of the full PW Consulting report
The complete study is built as a decision engine for executives. Elements you will find (and rely on) include:
- Scenario‑driven demand model (2026–2032) with sensitivity levers for raw material pricing, certification timelines, and adoption rates of powder/AM solutions.
- Validated cost‑to‑qualify and time‑to‑market matrices for new alloy grades and powder/AM launches — essential for project-level capital planning.
- Supplier scorecards and a procurement playbook that maps supplier capabilities to buyer risk appetites (including dual‑sourcing strategies, strategic inventory sizing and hedging tactics).
- Regulatory and certification roadmap with estimated timelines and cost impacts for aerospace and energy markets — enabling you to schedule investments and contractual milestones precisely.
- Commercial playbooks for pricing, contracting, and value-based offers for both manufacturers and distributors — including sample contract clauses to manage price pass‑throughs and long‑tail liabilities.
- M&A and partnership heatmap that identifies target profiles, integration risks, and expected synergies for roll‑up or strategic alliances.
We intentionally withhold detailed regional and application split tables in this preview to protect the competitive advantage encoded in our modeling. The full report includes proprietary segmentation, regional demand curves, and application‑level revenue forecasts required for project‑level decisions.
Risk factors and early warning indicators for 2026
- Raw material shocks. Nickel and cobalt price swings materially change producer margins and buyer economics. Short windows of price weakness can justify forward buying; sustained volatility favors long‑term contracts with indexation mechanisms.
- Certification delays. A single OEM qualification delay can cascade into multi‑year demand shortfalls for specific grades. Track first article approvals and supplier audit schedules as leading indicators.
- Technological substitution. Faster adoption of powder metallurgy or alternative chemistries (to reduce critical metal content) can change the addressable market for legacy wrought or cast products.
- Geopolitical supply interruptions. Chromium, manganese and other feedstock flows are increasingly sensitive to geopolitical events; maintain alternative sourcing routes and material substitution contingencies.
How boards and executives should use this intelligence in 2026
Translate the market view into a concise set of actions that align to your risk profile and growth ambition:
- Procurement & hedging (0–6 months): Implement tiered hedging and negotiate indexed long‑term supply agreements for critical inputs. Pilot a dual‑source strategy for at least one critical alloy family to de‑risk lead time shocks.
- Product and certification sprint (6–18 months): Allocate investment to certify one powder/AM grade and one wrought/cast grade for a target OEM program. Use our time‑to‑qualify matrices to budget both capex and working capital needs.
- Manufacturing & capacity (12–36 months): Prioritize flexible capacity that supports both conventional manufacture and powder feedstock to capture shifting demand without stranded assets.
- M&A and partnerships (12–24 months): Pursue bolt‑on acquisitions for feedstock security or specialist powder capability; form co‑development agreements with AM houses to accelerate commercial proof points.
- Performance metrics: Track purchase price variance vs. index, time‑to‑certification, supplier on‑time performance, and revenue share from AM/powder products as KPIs tied to executive incentives.
Final thought — why this report matters for 2026
The high performance alloys sector in 2026 is not merely expanding; it is re‑shaping. The confluence of technology adoption (powder/AM), persistent raw material pressures, and certification complexity means that traditional procurement, product development, and M&A playbooks must be retooled. Our PW Consulting report converts these structural changes into a pragmatic, prioritized set of moves — from tactical hedging to strategic partnerships — that protect margins and unlock growth. For executives who need to make capital allocation, sourcing, or M&A decisions this year, the difference between reacting and leading will be access to accurate demand scenarios, supplier performance diagnostics, and certification roadmaps — all of which are included in the full study.
To access the complete dataset, company scorecards, and the decision‑ready playbooks referenced above, please consult the full High Performance Alloys Market report available on our site. The detailed segmentation tables and proprietary financial models are available exclusively to subscribers and clients who require executable intelligence for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: High Performance Alloys Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


