



PW Consulting: Tamping Machine Market to hit USD 3,670.02M by 2032 at 5.26% CAGR

Tamping Machine Market — Strategic Briefing for 2026 Decision-Makers
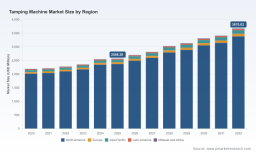
PW Consulting’s 2026 market study on tamping machines synthesizes seven years of historical performance (2020–2025), an updated base year (2025), and a forward-looking forecast window (2026–2032). The global market exceeded USD 2,568 million in 2025 and — under a central case that assumes continued modernization of rail fleets, steady infrastructure investment and phased adoption of automation — is projected to approach roughly USD 3,670 million by 2032 at a compound annual growth rate (CAGR) of approximately 5.26%. This briefing highlights the practical, decision-focused intelligence the full report delivers to executives planning capital allocation, procurement, operations and M&A in 2026, while intentionally withholding the line-by-line segmentation tables that are available in the complete study.
Tamping Machine Market
Why this study matters for 2026 strategy
-
Timing CapEx: The market trajectory and deployment lead times in our forecast allow asset owners to schedule fleet renewals and major procurements to avoid cost spikes tied to component shortages or regulatory certification windows.
Tamping Machine Market -
Technology adoption: The study maps the commercialization timeline for autonomy and battery-electrified tampers, enabling procurement teams to specify interoperable platforms instead of vendor-locked legacy systems.
Tamping Machine Market -
Service & aftermarket economics: Detailed TCO and aftermarket scenarios help operators and OEMs convert one-off sales into long-duration service contracts that stabilize cash flows.
-
M&A and partnerships: Competitive intensity metrics and capability overlays identify acquisition targets and alliance opportunities to close gaps in automation, electrification or geographic footprint.
-
Risk management: Supply-chain vulnerability mapping (notably steel inputs and key hydraulics/electronics) supports hedging strategies and alternative sourcing plans.
What the full report contains (practical, actionable modules)
-
Market sizing & forecast model (2020–2032): reconciled top-down and bottom-up construction of the global market with scenario variants for low/central/high infrastructure spending.
-
Segment-level intelligence: type, application and regional views with shipment forecasts, adoption curves and sensitivity testing. (Note: the granular segment tables are available in the full report.)
-
Product and technology matrix: comparative benchmarking on productivity (m/h), energy architecture (diesel/electric/hybrid/battery), automation readiness, and modularity for retrofits.
-
Competitive landscape and capability maps: strategic profiles, product roadmaps, recent moves and SWOT-style implications for each major vendor.
-
Demand-side buyer requirements: procurement specification templates, certification checklists, and sample SLA/maintenance contract language aligned to rail operators’ operational KPIs.
-
Supply-chain diagnostics: critical-material dependency analysis (steel, hydraulic components, semiconductors for controls), lead-time modelling and cost-inflation scenarios.
-
Commercial playbooks: pricing strategies, service-pack bundling, financing structures and pilot-to-scale commercialization plans.
-
M&A and partnership shortlist: commercially validated targets and strategic rationale for bolt-ons, technology buys and JV structures keyed to 2026 execution calendars.
Key market dynamics to account for in 2026
-
Automation is arriving at scale. Demonstrations of autonomous tamping across turnouts and complex track formations have moved from R&D showcases into field pilots. Early deployments are reshaping staffing models and enabling higher-throughput windows that reduce the disruption footprint of maintenance works.
-
Electrification and battery power are strategic differentiators. Compact battery-driven tampers reduce diesel dependence and lower onsite emissions, offering operational advantages in labor-constrained regions and in projects with restrictive access windows.
-
Precision continues to be a product design axis. High-frequency and elliptical tamping technologies—combined with sophisticated geometry measurement systems—are driving value in premium segments where uptime and ride quality command a price premium.
-
Material and component risk is real. Steel remains a central input for tines and structural components; fluctuations in raw-material markets propagate into lead times and cost. Our scenarios quantify the impact of multi-quarter steel price shocks on replacement schedules and spare parts provisioning.
-
Regulation and certification create commercial gates. CE and Machinery Directive approvals, plus national certification regimes, materially affect time-to-market for updated platforms and should be built into procurement timelines.
Competitive landscape — what to watch (executive summary)
-
Plasser & Theurer — A technology and scale leader known for continuous-action tampers and high-productivity machines. Recent demonstrations and product refreshes underline a clear push toward autonomy and all-electric drives, increasing throughput while tightening the performance envelope for competitors.
-
MATISA — Differentiates through high-frequency elliptical tamping and an emphasis on tight track-geometry outcomes. Their technology is attractive to operators prioritizing lifecycle ride quality over lowest-capex procurement.
-
ROBEL — Focused on compact, battery-capable vertical tampers and modular products that address labor and emissions constraints. Regulatory approvals and product ergonomics make them a preferred choice for targeted maintenance contracts and short-access windows.
-
S7 Rail — Known for patented hydraulic drives and reliable universal tampers; competitive where rugged simplicity and regional serviceability matter.
-
Regional manufacturers (Remputmash Group, Kalugaputmash, Gemac, CRCC) — These players offer value in localized markets or as part of integrated infrastructure project sets. CRCC’s integrated project capabilities, in particular, create advantages in turnkey track programs where machinery supply is bundled with construction services.
-
Market structure — Top-tier vendors capture a meaningful share of global revenues while specialist and regional players retain critical footholds; the market exhibits moderate concentration, leaving room for targeted consolidation and niche innovation plays.
Strategic imperatives and recommended 2026 actions
-
Prioritize pilot deployments of autonomy and battery technologies in low-risk corridors to de-risk full-scale rollouts within two procurement cycles.
-
Reframe procurement specifications around total cost of ownership and interoperability rather than lowest initial capex; require telemetry and open-data interfaces for future-proofing.
-
Lock conditional supply agreements for critical steel and hydraulic components and model multi-quarter price shocks to set realistic spare-part buffers.
-
Shift commercial models toward service contracts and consumable sales; build spare-part logistics hubs in-situ to lower downtime and increase aftermarket margins.
-
Scan for bolt-on acquisitions that supply missing capabilities (e.g., autonomy stacks, battery packs, regional service networks) and prioritize targets identified in the report’s M&A shortlist.
-
Invest in workforce reskilling; hybrid roles that combine diagnostics, remote operation and mechanical trade skills materially reduce OPEX per km of maintained track.
-
Engage early with certification authorities when introducing new drive systems or automation features to avoid lengthy re-certification delays.
Using this briefing and the full PW Consulting study
This briefing distils the study’s most consequential themes and decision levers for 2026. The full deliverable contains the granular regional and application breakdowns, vendor unit economics, pricing decks and downloadable financial models that executives use to justify CapEx, structure procurement auctions, and negotiate long-term service agreements. For teams preparing procurement specifications, M&A diligence or new-product roadmaps, the complete dataset and scenario tools are an operational necessity.
PW Consulting’s tamping machine study equips executives with the market-scale confirmation, trend evidence and playbooks needed to convert insight into execution. If your 2026 plan requires precise deployment timing, vendor shortlists, or a defensible financial case for investing in automation or electrification, the full report provides the empirical foundation and actionable templates to move from strategy to signed contracts.
For detailed analysis of this topic, please visit the official page: Tamping Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


