



Single-use Bioreactors Market Set for 15.45% CAGR - PW Consulting Insights

Single-use Bioreactors Market: Strategic Preview for 2026 Decision-Making
Executive snapshot
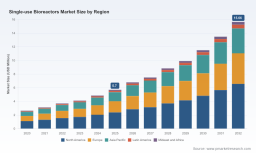
Single-use bioreactors (SUBs) have moved from an experimental convenience to a strategic core of modern bioprocessing. PW Consulting’s latest market study frames this transition with a clear, actionable narrative: the global SUB market has expanded sharply over the past half-decade and, under current drivers, is set to continue compounding at a double‑digit pace. Between the 2020 base period and the 2025 reporting year the sector more than doubled in scale; our forecast shows the market accelerating further from the 2026 base, tracking at a compound annual growth rate (CAGR) of 15.45% through the 2026–2032 horizon. By 2032 the sector is projected to be multiple times its mid‑decade size, creating substantial opportunities — and distinct risks — for OEMs, suppliers, and end‑users.
Single-use Bioreactors Market
Why this study matters for 2026 strategic choices
- Timing matters: 2026 is a pivot year for regulatory tightening, capacity planning, and capital allocation. Companies that calibrate investments now will reap outsized benefits as adoption moves from early‑adopter laboratories to sustained commercial production environments.
- Operational trade-offs are quantifiable: SUBs materially reduce upstream validation and cleaning burden relative to stainless steel, compress time‑to‑clinic and commercial scale‑up, and shift cost profiles from CAPEX to OPEX. Our analysis translates those trade‑offs into decision rules for procurement, process design, and budgeting.
- Competitive positioning requires read‑throughs: Product launches and platform expansions are reshaping the competitive landscape — deciding whether to partner, build, or buy hinges on a firm grasp of capabilities, scale limits, and the regulatory bar for extractables/leachables and closed‑system integrity.
Market trajectory — the macro picture
The historical series captured in our study shows a steady, technology‑led climb through 2025, followed by an acceleration as vaccine, antibody, and cell‑therapy demand intersect with operational incentives to lower capital and labor burdens. Against that backdrop the 2026–2032 forecast period reflects sustained adoption across R&D and commercial biomanufacturing use cases. While we deliberately withhold granular split tables in this preview, readers should note three macro takeaways from the aggregate data:
Single-use Bioreactors Market
- Adoption is broadening across scales — from benchtop, small‑volume platforms supporting process development, to high‑volume single‑use assemblies designed for commercial production.
- Economic calculus favors substitution in many scenarios: for select workflows total cost of ownership and time to market considerations make single‑use systems the preferred option.
- Market concentration is significant. Incumbent life‑science OEMs and a handful of specialized suppliers will continue to capture the lion’s share of value unless new entrants combine novel value propositions with robust regulatory and supply‑chain strategies.
Regulatory and operational dynamics shaping 2026 strategies
Two regulatory inflections are central to near‑term planning. First, extractables and leachables expectations have been elevated to mandatory compliance in parts of the regulatory landscape — requiring documented risk assessments and characterization for product‑contact materials. Second, agency guidance is increasingly favoring closed, single‑use designs that reduce cleaning requirements and support aseptic manufacturing. These shifts increase the cost and time of qualification for bag and connector suppliers, but also raise the barrier to entry — which benefits established players with robust E&L data packages and regulatory track records.
Single-use Bioreactors Market
Operationally, SUBs offer dramatic reductions in validation cycles and cleaning labor. Buyers should model the full lifecycle economics: while consumable costs (for example, higher‑volume single‑use bags) introduce recurring spend, the elimination of lengthy stainless‑steel validation studies, and the reduction of labor and facility downtime, often offset recurring consumable expenses by accelerating throughput and reducing time‑to‑revenue.
Competitive landscape — capabilities and strategic moves
The market structure favors diversified life‑science conglomerates, engineering specialist OEMs, and focused new‑entrants targeting advanced therapies. The competitive map is being redrawn by recent product launches and platform expansions that extend scale, automation, and monitoring capabilities.
- Thermo Fisher Scientific continues to leverage breadth, extending its DynaDrive series to capture both academic and regulated small‑scale GMP use cases; recent launches emphasize compact, GMP‑ready systems that lower the barrier for clinical manufacturing sites.
- Sartorius has doubled down on automation and digital monitoring within its stirred‑tank and parallel‑processing offerings, positioning itself as a turnkey supplier for customers seeking integrated hardware‑software stacks for process intensification.
- Danaher (via its Pall and Cytiva businesses) is scaling single‑use architectures into higher volumes, supporting monoclonal antibody and vaccine programs that require mid‑to‑large batch capacities — a strategic recognition that SUBs are moving into applications that were previously the exclusive domain of stainless steel.
- Smaller specialized firms — Eppendorf, PBS Biotech, ABEC, Distek, and focused rocking‑bioreactor suppliers — are capitalizing on niche strengths: non‑invasive sensing, cell‑therapy‑specific automation, and bench‑to‑clinic scalability. Notably, ABEC’s recent ATB™ platform exemplifies the new wave of fully single‑use, automated solutions tailored for advanced cell therapies.
For incumbents and challengers alike, the actionable strategic question is not simply “who wins?” but “how will each player monetize scale, integration, and regulatory proof?” The firms that combine platform breadth, documented E&L packages, and channel partnerships to supply clinical‑to‑commercial customers will enjoy structural advantages.
Supply chain and cost levers — what to model in 2026
Three supply‑side realities must be explicit in financial and operational models:
- Consumable pricing variability: high‑volume single‑use bags represent a meaningful recurring cost; organizations should model sensitivity to bag pricing, batch frequency, and reuse‑equivalent scenarios where regulatory frameworks permit.
- Raw‑material and supplier concentration risk: polymer availability, specialized connectors, and sensor suppliers can become single points of failure in scaled production. Mitigation includes qualifying multiple suppliers, inventory hedging, and strategic sourcing partnerships.
- Validation and E&L investment: meeting elevated regulatory expectations requires upfront investment in characterization data and process validation. Firms with in‑house E&L capabilities or established industry partners reduce time‑to‑market and mitigate submission risk.
Strategic playbook for 2026 — recommended actions
PW Consulting translates the market data and competitive dynamics into five tactical moves for executive teams planning 2026 priorities:
- Segment investments by commercialization stage: prioritize modular, single‑use platforms for late‑stage clinical and commercial programs where speed and lower CAPEX drive ROI, and retain flexible benchtop systems for exploratory R&D where throughput and experimental agility matter most.
- Prioritize suppliers with robust E&L packages and closed‑system pedigree. Use regulatory dossier readiness as a procurement filter equal to price and lead time.
- Build dual‑sourcing strategies for critical consumables to manage pricing and supply shock, and contractually embed service-level agreements for emergency supply and regulatory support.
- Invest in digital monitoring and PAT (process analytical technology) integration to extract value from SUBs — better in‑process control reduces batch failures and supports higher net yields, which can materially offset consumable costs.
- Consider strategic M&A and partnerships to close capability gaps quickly — particularly if pursuing advanced therapy scale‑up or rapid geographic footprint expansion.
What PW Consulting’s full report delivers (practical content)
The full study is structured to move teams from insight to implementation. Highlights include:
- Actionable scenario models that quantify total cost of ownership across R&D and production scales under multiple bag‑price and batch‑frequency assumptions;
- Due diligence playbooks for qualifying single‑use suppliers, including checklists for E&L documentation, aseptic connector validation, and digital integration readiness;
- Commercial go‑to‑market strategies tailored to OEMs and system integrators — including channel maps, partner archetypes, and prioritized M&A targets (operationally anonymized in this preview);
- Capex vs. Opex decision calculators for CFOs and process leads, translating our 2026–2032 macro forecasts into site‑level investment triggers.
Using the report in 2026 — practical next steps
- Procurement teams: adopt the supplier‑qualification playbook and re‑price multi‑year consumable contracts using our scenario models.
- R&D and process development: map platform selection to product lifecycle stage; leverage our bench‑to‑plant decision trees to reduce scale‑up risk.
- Corporate strategy and BD: use the competitor capability matrix to identify partner targets or acquisition candidates that accelerate access to E&L datasets, digital monitoring, or scale‑up capacity.
- Regulatory affairs: align dossier preparation timelines with the new extractables/leachables expectations and closed‑system guidance embedded in the study.
Final perspective — opportunity framed, not foreshadowed
The single‑use bioreactor market in 2026 is both a growth and governance story. Aggregate market dynamics — steep historical growth, a high‑teens cumulative CAGR through the forecast window, and increasing concentration among skilled incumbents — create a classic environment for consolidation, vertical integration, and performance differentiation through regulatory and supply‑chain excellence. PW Consulting’s full report provides the proprietary breakdowns, supplier rankings, and scenario tables that operational planners and strategy teams need to convert these macro trends into executable plans. This preview surfaces the strategic contours; the full study is designed as the tactical map for organizations that want to move confidently from intention to implementation in 2026.
Learn more
For the complete dataset, segmentation tables, supplier scorecards, and the turnkey decision tools referenced here, consult the full PW Consulting Single‑use Bioreactors Market report available on our research portal.
For detailed analysis of this topic, please visit the official page: Single-use Bioreactors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


