



Powertrain Testing Market Eyes USD 387.44M by 2032, 6.0% CAGR — PW Consulting

Powertrain Testing Market 2026: Strategic Preview for Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused introduction to our latest Powertrain Testing Market study. This briefing synthesizes the essential market dynamics, competitive contours, and practical frameworks that senior executives, R&D leaders, and capital allocators must apply in 2026. The narrative demonstrates the analytical depth behind our forecasting and scenario work while intentionally holding back detailed segment-level tables and granular numerical splits — access to the full report is required to operationalize the proprietary sub-segment intelligence.
Powertrain Testing Market
Market Trajectory — headline numbers you need to anchor 2026 plans
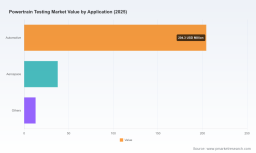
The market for powertrain testing equipment and services has moved from an early‑stage recovery and modernization phase in the early 2020s into a sustained growth trajectory driven by electrification, regulatory tightening, and digital test automation. Our model — built on a 2025 base year with a historical window covering 2020–2025 and a forecast horizon through 2032 — projects a steady compound annual growth rate (CAGR) of approximately 6.0% across the forecast period. After rebounding through the mid‑2020s, aggregate market value expands further into the late 2020s and early 2030s as OEMs and component suppliers scale validations for high-voltage systems, software‑intensive controls, and multi‑domain integrations.
Powertrain Testing Market
These topline dynamics are important for 2026 capital planning cycles: the pace of market growth supports staged capital investments in modular test infrastructure and pay‑as‑you‑use test services, while the steady CAGR reduces the risk of large‑scale overbuild if iterative modular expansion is adopted.
Powertrain Testing Market
Why this study matters for 2026 decisions
- Capital allocation and timing: Our scenario matrices link market growth phases to suggested investment profiles (conservative, hybrid, aggressive). In 2026, organizations face a choice between retrofitting legacy ICE test assets or accelerating greenfield HV/EV labs — the report quantifies tradeoffs in utilization, payback, and obsolescence exposure.
- Technology roadmap alignment: The testing needs for electrified and hybrid powertrains differ materially from ICE‑only programs. We map the technology priorities (high‑voltage safety, regenerative capability, HiL/SiL integration, climatic conditioning) to procurement specifications and vendor archetypes to shorten vendor selection cycles.
- Operational productivity: Labor shortages and the shift toward automated test benches change total cost of ownership (TCO) calculations. We provide pragmatic templates for staffing models, automation ROI, and standard operating procedures that enable faster throughput with measured headcount.
- Regulatory & risk management: With evolving regulatory regimes — including electric powertrain safety standards — the report translates compliance requirements into testing protocols and certification pathways to reduce program delays and aftermarket liabilities.
What the full report delivers (practical elements)
Our study is structured to be immediately actionable. Key deliverables include:
- Market sizing and validated demand curves with scenario‑based sensitivity analyses tied to EV adoption and regulatory timelines.
- Use‑case driven procurement playbooks for test labs — including modular vs. dedicated rig decision trees, recommended spec sheets, and vendor evaluation scorecards.
- CapEx and OpEx models for lab modernization: lifecycle cost templates, depreciation scenarios, and utilization thresholds that trigger next‑stage investments.
- Test program blueprints for common powertrain validations (HV battery pack integration, e‑axle endurance, driveline NVH with electrified torque profiles), with recommended instrumentation stacks and data architecture patterns.
- Vendor benchmarking and vendor‑selection negotiation templates — covering performance guarantees, spare‑parts strategy, and service‑level commitments.
- Regulatory compliance mapping that converts standards into test protocols and measurable acceptance criteria.
- Acquisition and partnership playbooks for scaling testing capacity via outsourcing, consortium labs, or M&A.
These components are designed to move executives from strategic intent to procurement-ready specifications within a single planning cycle.
Competitive landscape: where incumbents and new entrants are placing their bets
The powertrain testing market remains moderately concentrated, with the top three vendors commanding a dominant share of specialized test system deliveries and the top five consolidating a larger portion still. That concentration creates clear vendor archetypes: global system integrators focusing on turnkey lab solutions; specialized equipment manufacturers targeting high‑performance dynamometers and e‑axle benches; and service providers offering contract testing and validation facilities.
- AVL List GmbH (Graz, Austria): AVL’s 2024 hybrid powertrain test rig is positioned as an integrative solution for assessing electrified components. Their approach emphasizes system‑level evaluation, which appeals to OEMs consolidating EV and ICE validation flows.
- Horiba Ltd (Kyoto, Japan): Horiba’s modular EV powertrain benches and integrated emission/combustion analyzers make them a go‑to for customers seeking combined ICE and electrified capability — especially where regulatory emission validation remains relevant.
- SAKOR Technologies, Inc. (Michigan, USA): SAKOR’s AC dynamometers and DynoLAB PT cells are targeted at powertrain-level validation across hybrid and electric domains, with strong positioning for North American engineering centers.
- Schenck RoTec GmbH (Darmstadt, Germany): Historically strong in driveline and transmission dynamometers, their D1100 series and e‑axle testing capabilities aim to capture component manufacturers upgrading to e‑drive validations.
- A&D Technology, Inc. (California, USA): With a focus on HiL simulation, DAQ, and automated calibration, A&D is part of the software‑enabled testing cohort that addresses the integration of control software and hardware validation.
- Intertek (London, UK) and Magna International (Auburn Hills, MI): These players combine services and facility access, enabling OEMs to scale program capacity quickly via external test cells and turnkey validation projects.
- Specialist labs (EPowerLabs, Ernst Gruppe, Enorise, ACS): These regional specialists fill niches—high‑power motor/inverter testing, climatic conditioning, and turnkey bench delivery—often collaborating with larger integrators on complex programs.
Recent corporate moves underscore competitive dynamics: AVL’s 2024 hybrid test rig launch and Horiba’s facility expansion in 2025 demonstrate supplier responses to demand for electrified validation. Industry showcases such as the 2026 Advanced Chassis & Powertrain Showcase (Vehicle Tech Week North America) are also accelerating cross‑pollination between equipment OEMs and service providers.
Market dynamics shaping vendor and buyer strategies
The testing market’s near‑term behavior is influenced by four interacting forces:
- Raw material volatility: Price and supply risk for lithium, nickel, and rare earths affect component costs and push suppliers to validate alternative chemistries and motor designs — increasing test program variety and complexity.
- Regulatory pressure: Safety and performance standards for electric vehicles (including evolving electric powertrain safety mandates) force earlier and deeper testing to demonstrate compliance, lengthening validation horizons for new architectures.
- Electrification-driven technical requirements: Regenerative braking simulation, high‑voltage safety protocols, and thermal management testing demand specialized rigs and climatic conditioning, placing a premium on modularity and adaptability in new lab builds.
- Workforce constraints and automation: Labor shortages accelerate adoption of automated benches, HiL simulation, and remote test orchestration — reducing per‑test labor but increasing upfront software and instrumentation investment.
Strategic implications for 2026 — three recommended pathways
For executives finalizing 2026 roadmaps, our study crystallizes three practical pathways defined by risk appetite and strategic priorities:
- Modernize Incrementally (Low Risk): Prioritize modular upgrades to existing rigs, add HiL/DAQ capability, and outsource episodic high‑power testing to contract labs. This conserves capital while improving test coverage for hybrid programs.
- Build for Scale (Balanced): Invest in a dual‑capability lab that supports ICE and electrified powertrain validation with capacity for climatic conditioning and high‑voltage safety testing. Couple CapEx with long‑term service contracts to manage utilization risk.
- Lead with Electrification (Aggressive): Rapidly retool to high‑voltage, regenerative test platforms and expand software test automation. This path is appropriate for suppliers and OEMs committing to BEV‑first portfolios and captive validation strategies.
Each pathway has attendant supplier strategies: long‑term vendor partnerships and performance‑based contracts for the Build for Scale option; pay‑per‑use alliances and white‑label lab access for Incremental Modernize; and strategic acquisitions or exclusive equipment development for the Lead path.
Methodology and confidence framing
Our forecasts synthesize bottom‑up equipment shipments, service utilization rates, and validated demand indicators from OEM calendars. We incorporate regulatory timelines and scenario stress tests for raw material shocks and accelerated electrification. Market concentration metrics (top‑3 and top‑5 vendor shares) were derived from a combination of public disclosures, trade data, and proprietary supplier intelligence, offering a robust view of competitive positioning without exposing commercially sensitive segment tables in this preview.
Next steps — how to use this preview
This introduction is a strategic vantage point. To translate it into procurement packages, lab design blueprints, and M&A screens — all containing the granular sub‑segment metrics withheld here — request the full PW Consulting Powertrain Testing Market report. The full document provides the operative tables and worksheets that procurement teams and CFOs will use to finalize 2026 budgets and multi‑year investment plans.
Contact our research desk to schedule a briefing where we will walk your team through tailored scenarios, vendor shortlists, and a hands‑on procurement toolkit calibrated to your 2026 objectives.
For detailed analysis of this topic, please visit the official page: Powertrain Testing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


