



PW Consulting: Rebar Coupler Market to Reach USD 2,999.9M by 2032 at 7.4% CAGR

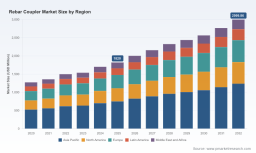
Rebar Coupler Market — Strategic Outlook for 2026 Decision-Making
PW Consulting’s latest Rebar Coupler Market briefing synthesizes five years of historical performance (2020–2025) and delivers a forward-looking, actionable perspective for the 2026 planning cycle. The global market — measured at a multi-hundred-million USD scale in 2025 (base year) — is projected to expand at a compound annual growth rate (CAGR) of approximately 7.4% over the 2026–2032 forecast period, reaching roughly USD 3.0 billion by 2032. This introduction explains why that trajectory matters to corporate strategists, procurement leaders, product teams and infrastructure investors, and outlines the pragmatic tools included in the full PW Consulting study that enable confident 2026 choices.
Rebar Coupler Market
Why this research matters in 2026
-
Timing: Infrastructure stimulus, urbanization and seismic retrofitting programs translate into near-term procurement opportunities and specification changes that will crystallize in 2026–2027. Vendors and buyers who align product, capacity and regulatory strategies now capture disproportionate share as projects move from specification to tendering.
Rebar Coupler Market -
Margin pressure vs. premiumization: Raw-material volatility (notably machined steel bar and hot-rolled coil) compressed manufacturer margins between 2021–2023; at the same time, higher labor costs and stricter regulations are accelerating adoption of higher-value mechanical couplers and one-touch systems. The result: a bifurcated market where commodity threaded couplers compete with premium engineered splice systems — and both require different go-to-market playbooks.
Rebar Coupler Market -
Regulatory inflection points: National and state-level approvals and mandates (examples include updated DOT approved lists and national standards that mandate couplers for larger-diameter bars) are reshaping specification lists used by engineering firms and owners. Understanding the approval landscape is a procurement imperative in 2026.
High-level market trajectory (what the numbers tell us)
-
Momentum: The market recorded steady expansion through 2020–2025, reflecting a recovery and upgrade cycle in global construction and growing acceptance of mechanical splicing over lap splicing for efficiency and performance. The 7.4% CAGR projected for 2026–2032 is supportive of continued investment across manufacturing, testing and distribution footprints.
-
Concentration: Industry concentration is moderate — the top three suppliers control nearly half of the market, while the top five capture roughly six in ten dollars. That structure creates space for regional champions and specialized product innovators, while also leaving room for M&A consolidation that can move results quickly.
-
Opportunities vs. risks: Demand-side tailwinds (infrastructure projects and labor-driven adoption of faster splice systems) are balanced by supply-side risks, notably steel price swings and localized certification requirements that delay new product uptake unless proactively addressed.
Competitive landscape — strategic positions and practical implications
The report contains a deep competitor benchmark of the market’s active manufacturers, with actionable insights on capability, approvals and channel positioning. Key profiles and implications include:
-
Dextra Group (Thailand): Leader-level portfolio with Bartec, Griptec and Rolltec systems and vertically integrated manufacturing for both parallel and tapered-thread couplers. Strength: global infrastructure projects and approvals momentum (e.g., recent regional product approvals). Strategic implication: high-value projects and DOT tenders will favour vendors that can combine certification breadth with local logistics.
-
Peikko Group (Finland): Focus on visual-inspection-friendly splicing systems and precast/on-site safety features. Strength: integration with precast workflows and quality control. Strategic implication: OEM partnerships with precasters and offsite integrators accelerate adoption, especially where labor availability is constrained.
-
nVent LENTON (United States): LENTON Standard and Taper Lock systems, with DOT/code approvals oriented to North American infrastructure. Strength: compliance-rich product families and distribution reach. Strategic implication: entrants targeting state-level DOT projects must align to local approvals and testing regimes to earn inclusion on approved lists.
-
CRH plc — Leviat / Ancon (Ireland): Structural connection systems and continuity solutions for Europe and global markets. Strength: brand recognition among European structural engineers. Strategic implication: specification-led adoption requires early engagement with engineering houses and participation in standards development.
-
Japan-based specialists (Tokyo Tekko, Splice Sleeve Japan, Fuji Bolt): Strong pedigree in parallel-thread technology and grout sleeves optimized for seismic and high-performance applications. Strategic implication: in seismically active regions, product certification and demonstrated cyclic performance are differentiators.
-
North American fabricators (BarSplice, Dayton Superior): Grout-filled and mechanical splice offerings aligned to local codes and precast markets. Recent DOT approvals and listing updates reinforce the importance of staying current with state procurement lists. Strategic implication: domestic suppliers can defend share through rapid approvals and contractor relationships.
-
China regional competitors (Sida Jianmao, Hebei Yida): Cost-competitive threaded couplers and MBT solutions serving domestic and regional projects. Strength: price-driven scale and proximity to large projects. Strategic implication: multinationals competing on price must optimize cost-to-serve or differentiate via value-added services and approvals.
Dynamics and regulatory environment — what to watch in 2026
-
Raw material volatility: Historical hot-rolled coil price swings led to margin erosion in manufacturing. Our cost-model scenarios show that supply contracts and localized machining capacity materially reduce exposure for mid-size producers.
-
Labor and productivity: Rising labor costs in key markets have converted buyers to “one-touch” mechanical couplers that reduce onsite man-hours by up to 60% versus lap splicing. This productivity delta is a compelling procurement lever for owners seeking schedule certainty.
-
Regulatory approvals and standards: Active approvals and updates — for example, state DOT approved-list revisions and national technical approvals in Europe — are gating factors for project inclusion. Manufacturers without approved products face lengthy qualification cycles that can cost market access.
-
Digital integration: Modeling and detailing tools are beginning to embed coupler libraries; the addition of a rebar coupler module to mainstream software platforms in early 2026 underscores the need for manufacturers to provide BIM-ready product data to remain visible to designers and precasters.
What the PW Consulting report delivers (practical, procurement-ready outputs)
We designed the full report to be directly usable in 2026 decision processes. Deliverables include:
-
Granular market sizing and forecasts (global and segmented across type, application and region) with scenario sensitivity to steel price, labor inflation and regulatory adoption timing.
-
Competitive benchmarking: capabilities, approvals, channel strength, commercial terms and product roadmaps for the leading 12–15 manufacturers, plus a vetted list of regional suppliers for sourcing plays.
-
Regulatory and approvals matrix across major markets (including national standards and key DOT lists), with a path-to-approval checklist and estimated timelines — essential for procurement and product managers planning 2026 tenders.
-
Cost-to-manufacture models and plant-level operating curves showing break-even volumes for threaded vs. grout sleeve vs. one-touch mechanical couplers, enabling capital allocation and make-vs-buy choices.
-
Supply-chain resilience playbook addressing raw-material procurement strategies, hedging approaches, and nearshoring scenarios to blunt coil-price volatility.
-
M&A and JV screening framework with prioritized targets by technology, geography and approval status to accelerate market entry or capability acquisition.
Strategic recommendations for executives in 2026
-
For manufacturers: Prioritize certification campaigns in large, procurement-driven markets and invest selectively in BIM/product data integration to influence specs upstream of tendering. Protect margins by locking steel supply and automating machining operations where feasible.
-
For OEMs and precasters: Standardize on coupler families that reduce installation time and simplify QA. Use the report’s approval matrix to align purchasing specifications with certified supplier lists and avoid last-minute substitutions that risk non-compliance.
-
For investors and M&A teams: Target businesses that combine certified product portfolios with regional manufacturing footprint; mid-sized players with approvals in major DOTs or national technical approvals can be high-leverage acquisitions given current concentration metrics.
-
For owners and contractors: Leverage productivity gains from one-touch systems in bid assumptions and include coupler performance clauses in contracts to transfer risk back to suppliers where possible.
Why PW Consulting — and what we intentionally withhold here
This article intentionally surfaces the strategic themes, competitor dynamics and practical levers that matter for 2026 without publishing the confidential granular segment tables and supplier-level revenue series that the full study contains. Our “trailer” approach demonstrates analytical depth while protecting the precise segmentation and supplier-by-application datasets that procurement teams and corporate strategists require to execute. The full report includes exhaustive data tables, regional and application splits, supplier revenue modeling, and step-by-step implementation playbooks.
If your 2026 plan requires clear procurement thresholds, certification pathways, or an M&A scouting list tailored to your risk appetite, the full PW Consulting Rebar Coupler Market study provides the calibrated datasets and executable checklists needed to move from strategy to execution.
For access to the complete dataset, segment-level forecasts and the supplier playbook, visit our report page or contact PW Consulting’s industry practice lead to schedule a strategy briefing and workshop tailored to your organization’s 2026 priorities.
For detailed analysis of this topic, please visit the official page: Rebar Coupler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


