



PW Consulting: TDAE Market Hits USD 985M in 2025, Eyes 5.2% CAGR to 2032

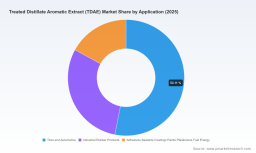
Treated Distillate Aromatic Extract (TDAE) Market — Strategic Outlook for 2026 Decision‑Making
As PW Consulting’s lead strategy advisor and chief industry analyst, I present a concise strategic primer on the Treated Distillate Aromatic Extract (TDAE) market to orient executive decision-making in 2026. This piece is written as a high-value “trailer”: it surfaces the critical macro dynamics, competitive signals and actionable implications that we see driving the market over the next investment cycle, while deliberately withholding the granular segment tables and proprietary scenario outputs that underpin deal-level work. If your 2026 plan depends on sourcing, producing, or investing in TDAE or downstream rubber compounds, the full report contains the detailed telemetry you will need to convert the instincts below into executable programs.
Treated Distillate Aromatic Extract (TDAE) Market
Macro view: a steady, mid-single‑digit growth story with structural tailwinds
At the aggregate level the TDAE market entered 2026 from a stable base. After recovering from pandemic‑era volatility, global TDAE revenue rose from the mid‑700 million USD range in 2020 to just under one billion USD in the 2025 base year (USD 985 million). Our forecast — built on demand scenarios spanning 2026–2032 — uses a central case CAGR of 5.2% and projects continued expansion through 2032 as tire and industrial rubber applications gradually shift toward higher‑performance, lower‑PAH process oils and as emerging applications (including specialty compounds for electric‑vehicle tyres and sustainable elastomers) lift unit value.
Treated Distillate Aromatic Extract (TDAE) Market
Two structural features matter for strategy: first, demand growth is predictable but not explosive — creating a market where margin capture, operational flexibility and regulatory compliance drive competitive advantage more than volume alone. Second, the supplier landscape is moderate in concentration: a mix of global majors and regional producers compete on product specification, reliability and certification rather than pure scale. These characteristics shape the playbook for supply contracts, capex choices and M&A activity.
Treated Distillate Aromatic Extract (TDAE) Market
Key dynamics reshaping the landscape through 2026
- Regulatory differentiation is a market maker. Regulatory regimes — notably European rules that require non‑carcinogenic rubber process oils meeting low DMSO‑extract/IP346 thresholds for tyre exports — are driving demand for validated low‑PAH TDAE grades. Producers who can reliably demonstrate compliance unlock higher‑margin OEM and Tier‑1 channels.
- Raw material and feedstock sensitivity. TDAE production economics remain tightly coupled to crude oil and refinery product pricing. We observed a notable cost shock tied to crude price movements in early 2026, underscoring the need for active feedstock hedging and formula‑based pricing mechanisms in customer contracts.
- Product innovation and substitution vectors. High‑compatibility grades tailored to bio‑based synthetic rubbers and green tyre recipes are emerging. New grade launches from major refiners reflect a strategic shift: TDAE is becoming part of OEM sustainability roadmaps, not just a commodity input.
- Capacity and supply repositioning. Recent capacity investments and strategic supply partnerships indicate manufacturers are rebalancing footprints to align with tyre OEM clusters and to meet low‑PAH specifications at scale. Expect incremental global capacity targeted at compliant grades rather than a broad expansion of low‑spec oils.
What the PW Consulting report contains — practical, transaction‑ready content
Our full TDAE study is structured to support commercial, operational and M&A decisions in 2026. Highlights include:
- Top‑down and bottom‑up market sizing and forecasting across multiple demand scenarios (base, upside, downside) for 2026–2032, with sensitivity to oil price and tyre production mixes.
- Price and input‑cost modelling that links crude, refinery margins and finished TDAE pricing to gross‑margin outcomes for producers and pass‑through risk for buyers.
- Supplier scorecards and a validated capability matrix covering product specs (PAH content, DMSO extract levels), quality certifications, global distribution, and commercial contracting terms.
- Regulatory compliance maps and market access checklists for major export corridors, including specific pathways for securing EU tyre market access under IP346 requirements.
- Go‑to‑market playbooks for producers and buyers: commercial negotiation templates, offtake contract structures, inventory and hedging strategies, and win/loss case studies.
- M&A and JV screening tools: target ranking by strategic fit, capacity quality, compliance profile and regional alignment, plus a transaction checklist to accelerate diligence.
- Operational readiness assessments for converting existing aromatic extender oil capacity to low‑PAH TDAE production, including capex estimates, timeframes and go/no‑go triggers.
We intentionally do not disclose segment‑level tables, regional splits and application breakdowns in this preview. Those outputs are central to actionable decisions and are provided in the subscription report alongside our model files and supplier dossiers.
Competitive landscape — who to watch and what they signal
The competitive field is a mix of global refiners and specialized regional players. Strategic distinctions matter more than count: global majors emphasize product breadth, regulatory certification and integrated distribution; regional producers compete on proximity, flexible commercial terms and niche technical grades.
- Leading global players: Firms with integrated refining and specialty‑oil platforms are leveraging certification and branded grades to secure OEM business — a trend reinforced by public commitments to supply low‑PAH, non‑carcinogenic process oils for evolving regulatory regimes.
- Regional champions: Producers in Asia and the Middle East are expanding capacity and establishing closer commercial ties to local tyre clusters, offering competitive logistics and tailored grades for compounders.
- Distributors and specialists: Firms that combine technical service, inventory proximity and flexible logistics are critical to tyre manufacturers that seek just‑in‑time supply without holding large inventories.
Recent strategic moves validate the broader thematic shifts: a major European producer announced a capacity expansion in China focused on low‑PAH grades aimed at the EV‑tyre segment; a specialist supplier entered a strategic partnership with a large Indian tyre maker to co‑develop customised formulations for green tyres; and a leading global energy company launched TDAE grades engineered for compatibility with bio‑based synthetic rubbers. These developments confirm that the market’s next phase is being shaped by product specification and regulatory alignment, not simply by volume.
Market concentration remains moderate: the top three and top five supplier clusters account for a non‑dominant but meaningful share of market activity, leaving ample room for regional competition, quality differentiation and targeted M&A.
Strategic actions for 2026 — recommended playbook by stakeholder
- Producers (refiners & specialty oil makers): Prioritise conversion or certification programs to produce low‑PAH grades; institute a two‑track commercial approach (long‑term offtake for OEMs + spot/short cycle for compounders); and establish feedstock hedges tied to crude and key refinery intermediates.
- Tire OEMs & compounders: Revisit supplier qualification criteria to emphasise regulatory proof points and supply‑security clauses; lock in blended pricing formulas that protect margins in volatile crude markets; and co‑invest in prototype grade development with select suppliers to secure preferential access to compliant oils.
- Investors & acquirers: Target assets with validated low‑PAH production capability, proximity to major tyre clusters, and contractual offtake relationships; be cautious on assets that require extensive capex to meet IP346‑type thresholds unless pricing power is demonstrable.
- Distributors & service providers: Build technical service packages and inventory networks for rapid compliance sampling and grade substitution support — a differentiator as OEM compliance requirements tighten.
How PW Consulting’s TDAE study accelerates execution in 2026
Our deliverables are built for action: integrated financial models you can plug into your investment committee, an M&A target shortlist mapped against your strategic criteria, supplier scorecards you can use immediately in RFPs, and a regulatory impact dashboard that converts IP346‑style thresholds into revenue risk by route‑to‑market. For procurement teams we offer negotiation playbooks that combine index‑linked pricing clauses with contingency supply metrics (lead times, MOQ, quality acceptance windows). For producers we provide a conversion feasibility toolkit that benchmarks required capex and time‑to‑market for low‑PAH grades under multiple scenarios.
Because segment‑level demand sensitivities, price‑elasticity matrices and supplier financials are core to transactional decisions, we withhold those datasets from this public primer. The full report includes the granular tables, source tracing and model files that underpin the strategic recommendations above.
Conclusion — a decisive year for positioning
2026 is a year in which the TDAE market’s direction will be set less by volume growth and more by specification, supply security and regulatory alignment. Companies that act now — by hardening compliance credentials, realigning supply chains, and selectively investing in compliant capacity or partnerships — will be best positioned to translate steady market growth into durable margin expansion. PW Consulting’s full TDAE study provides the data, scenario models and transaction‑ready tools required to make those decisions with confidence.
Contact PW Consulting to access the full dataset, supplier dossiers and the model workbook that support the above outlook. Our team can fast‑track a tailored briefing for procurement, technical or M&A decision‑makers within ten business days.
For detailed analysis of this topic, please visit the official page: Treated Distillate Aromatic Extract (TDAE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


