



PW Consulting: Climate Test Chamber Market Poised for 9.15% CAGR Through 2032

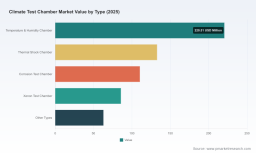
Climate Test Chamber Market — Strategic Briefing for 2026 Decision-Makers
As chief industry analyst at PW Consulting, I present an executive-grade orientation to our new Climate Test Chamber Market study. This briefing is designed as an investment- and procurement-facing “trailer”: it conveys the analytic depth and decision-usefulness of the full research while intentionally reserving the detailed segment tables and granular regional/application allocations for the full report. If you are preparing capital plans, qualifying suppliers, or defining R&D roadmaps for 2026, the directional intelligence below will help you reframe choices around energy, regulation, speed of validation, and supplier selection.
Climate Test Chamber Market
Market snapshot — size, trajectory and concentration
The climate test chamber market has moved from a narrow, specialist equipment category into a cross-industry infrastructure node. Using 2025 as the base year, our compiled historical series shows steady expansion from the early 2020s through 2025 and a continued growth trajectory into the early 2030s. The market is projected to expand at a compound annual growth rate of approximately 9.15% across the 2026–2032 forecast horizon. This pace reflects a blend of regulated energy-efficiency upgrades, broader environmental testing needs in electrified mobility and energy storage, and ongoing demand from high-throughput electronics and aerospace validation programs.
Climate Test Chamber Market
Market concentration is meaningful but not prohibitive: the three largest vendors account for a majority share of the industry’s commercial value, and the top five further consolidate over half of the market. That structure creates clear pathways for strategic partnerships, selective supplier lock-ins, and differentiated plays by smaller, specialized manufacturers.
Climate Test Chamber Market
Why this matters for 2026 decisions
-
Capital allocation: With a multi-year CAGR in the high single digits, procurement windows matter. Organizations planning chamber purchases should align CapEx phasing with both product roadmap releases (e.g., low-GWP or transcritical CO2 systems) and regulatory compliance deadlines that affect operating cost assumptions.
-
Energy & regulatory risk: The recent acceleration of energy performance regulation has converted energy consumption from an operating concern to a first-order compliance and cost issue. Equipment that achieves step-change improvements in power draw materially changes total cost of ownership (TCO) over its lifetime.
-
Product validation tempo: As development cycles shorten—especially in batteries, power electronics and autonomous systems—laboratories require more rapid thermal cycling and higher throughput. Procurement decisions that prioritize ramp-rate capabilities or modular scaling will deliver competitive advantage for product release cadence.
-
Supplier selection strategy: Market concentration shapes negotiation leverage. Buyers who combine rigorous technical requirement definitions with staged contracting (pilot → scale) can capture favorable terms from both global incumbents and nimble manufacturers.
Competitive landscape — positioning and strategic moves to watch
The market features a mix of long-established global incumbents and technically focused regional players. Key strategic profiles emerging from our analysis:
-
ESPEC Corporation — A technology-led incumbent that is aggressively positioning around energy efficiency and rapid-rate thermal control. ESPEC’s recent ECO Type models (low-GWP refrigerant platforms) and high ramp-rate chambers signal a push to combine sustainability with performance. Their R&D investments imply continued leadership where energy mandates intersect with high-speed thermal testing needs.
-
Thermotron Industries — Differentiates on proprietary controlled-environment systems and an emphasis on energy-efficient architectures. Thermotron’s strengths are in high-reliability control loops and systems integration for electronics and automotive validation programs.
-
Weiss Technik — Strong in walk-in and large-format chambers, especially for sectors that require integrated transcritical CO2 refrigeration. Their orientation toward automotive and aerospace customers gives them distinct advantage where large-scale simulation and compliance testing intersect.
-
BINDER and Memmert — European firms emphasizing energy-efficiency and compact constant-climate solutions; appealing to labs focused on sustainability and repeatability in small- to mid-scale testing applications.
-
Angelantoni, Cincinnati Sub-Zero, Associated Environmental Systems — These companies emphasize application-specific solutions (e.g., AR/ battery testing, accelerated stress), often competing on customization, service, and integrated validation workflows.
-
Regional leaders and scale specialists (KOMEG, DGBELL, Envisys) — Aggressive in walk-in chambers, ultra-low temperature capabilities, and vertically integrated manufacturing that supports competitive pricing for large facilities and energy storage testing.
Recent company-level developments illustrate the direction of competitive differentiation: (1) product launches that materially lower energy use or significantly increase ramp rates; (2) trade-show visibility in aerospace and naval R&D events signaling defense and high-reliability focus; (3) ultra-low temperature offerings for energy storage and new material validation. These moves confirm that product-level innovation—rather than purely price competition—is the dominant axis of competition in 2025–2026.
Regulation, materials and supply-side context
-
Energy Performance rules have become an operational driver: the revised Energy Performance of Buildings Directive (national transposition deadline May 29, 2026) directly influences facility-level equipment choices by elevating energy consumption into regulatory compliance assessments. Labs and test centers operating in affected jurisdictions should treat incremental energy reductions as compliance levers, not just cost-savings.
-
Material standards matter: stainless steel interiors (commonly 304/316L) remain the industry norm for walk-in and hermetic systems. Choices around interior materials influence lifecycle maintenance, chemical resistance for corrosion testing, and certification paths for medical/pharma spaces.
-
Refrigeration technology is the differentiation frontier: low-GWP refrigerants, transcritical CO2 systems and thermoelectric options are shaping procurement specs. Vendors that demonstrate credible power-reduction metrics and long-term refrigerant lifecycle strategies will be preferred suppliers in regulated markets.
What the full report delivers — practical, transaction-ready assets
Our PW Consulting report was constructed for operators who must execute in 2026. Included are:
-
Robust market sizing and forecast models (2020–2032) with sensitivity scenarios to stress-test CapEx decisions under alternative regulatory and adoption assumptions.
-
Vendor scorecards and procurement templates: technical requirement matrices, pilot-to-scale contracting frameworks, and negotiation playbooks tailored to buyer size and application category.
-
TCO calculators that fold-in energy, maintenance, downtime, and regulatory risk to compare legacy equipment retention versus replacement with next-generation low-GWP/transcritical or thermoelectric systems.
-
Use-case playbooks for high-growth validation areas (battery and energy storage, automotive electrification, avionics), with recommended test-configurations and supplier shortlists mapped to lab throughput and space constraints.
-
Scenario-based strategic options for manufacturers and suppliers: receptivity to partnership, OEM channel strategies, and service-led revenue models that monetize calibration and energy-monitoring services.
-
Primary interview insights and benchmarking data points that validate vendor claims on energy reduction and ramp-rate performance—presented in an anonymized, reproducible manner to protect commercial sources while enabling informed buying decisions.
Actionable recommendations for 2026 (prioritized)
-
Immediate (0–6 months): Audit current chamber fleet for energy baseline and compliance exposure; prioritize retrofit vs replacement decisions using a short TCO horizon tied to local energy-performance regulation deadlines.
-
Near-term (6–18 months): Run pilot validations with vendors demonstrating quantifiable energy reductions and required thermal performance (e.g., rapid ramp to meet accelerated stress-testing needs). Include service SLAs and modularity clauses in pilots to manage scaling risk.
-
Medium-term (18–36 months): For R&D-intensive organizations, invest in one or two “future-proofed” systems (low-GWP and high ramp-rate) as lab anchors to accelerate product development cycles—offset the CapEx via extended service agreements and energy performance-based financing where available.
-
Strategic (36+ months): Reassess supplier ecosystem for strategic partnerships—consider co-development agreements for niche chamber capabilities (ultra-low temperature or combined mechanical-environment test rigs) and explore bundling of validation-as-a-service for outsourced product qualification.
Concluding perspective
By 2026, climate test chambers will be purchased and configured less as one-off pieces of equipment and more as embedded components of product qualification pipelines, sustainability strategies, and regulatory compliance programs. The market’s high-single-digit CAGR and the established concentration among leading vendors create a predictable environment for disciplined buyers: act deliberately on energy and ramp-rate, insist on transparent TCO metrics, and structure pilots that convert into scalable deployments.
PW Consulting’s full Climate Test Chamber Market report provides the segment-level breakouts, regional allocation matrices, and proprietary vendor benchmarking required to execute these recommendations. This briefing intentionally omits the granular splits and confidential unit-level tables to preserve the actionable intelligence contained exclusively in the source report. For the complete dataset, vendor shortlists and downloadable TCO tools, consult the PW Consulting report package.
For detailed analysis of this topic, please visit the official page: Climate Test Chamber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


