



PW Consulting: HPS Market to Reach USD 683M by 2032 at 4.1% CAGR

HPS Market Outlook 2026: Strategic Imperatives for Executive Decision‑Making
As PW Consulting’s lead industry analyst, I present a focused briefing on the Horizontal Surface Pumps (HPS) market that frames the strategic choices facing corporate leadership as they enter 2026. This is a “trailer” — it surfaces the material trends, competitive levers, and decision frameworks that matter for near‑term capital allocation and commercial positioning, while reserving the granular segment tables and regional split models for our full proprietary release.
HPS (Horizontal Surface Pumps) Market
Executive snapshot: scale, trajectory, and concentration
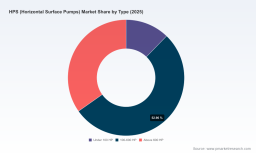
Using 2025 as the base year, our market model shows the global HPS sector advancing at a compound annual growth rate (CAGR) of approximately 4.1% through the medium term. The market—measured on a USD million revenue basis—has grown steadily from the early 2020s and our baseline forecast brings it materially higher by the end of the 2032 horizon. This steady, mid‑single‑digit expansion is driven by a blend of legacy oil & gas activity, midstream infrastructure buildout (notably water and saltwater management), and incremental adoption in adjacent energy applications.
HPS (Horizontal Surface Pumps) Market
Market concentration is significant: the top three vendors account for roughly two‑thirds of the market, and the top five capture about four‑fifths. That concentration creates both defensive and offensive strategic choices for incumbents and challengers alike.
HPS (Horizontal Surface Pumps) Market
Why this research matters for 2026 decisions
- Capex prioritization: When deploying capital in HPS assets or automation, precision on total lifecycle cost versus short‑term acquisition cost is decisive. Our modeling translates market growth and energy efficiency trends into NPV sensitivity for different pump classes and operating regimes.
- M&A and partnership screening: High concentration implies both potential targets and defensive consolidation threats. We provide a prioritization framework (technology fit, operational footprint, aftermarket revenue share) that helps executives screen deals under multiple macro scenarios.
- Product and service roadmaps: Vendors can quantify the business case for advanced automation, retrofit offerings, and performance warranties based on projected fleet growth and field retrofit economics.
- Procurement and sourcing strategy: Raw material exposure, supplier lead times, and certification requirements materially affect quote-to-delivery timelines. Our procurement playbook aligns sourcing choices with certification and alloy availability risks.
- Regulatory and compliance planning: Voluntary and mandatory standards are reshaping buy specifications. The research operationalizes API and ISO guidance into procurement checklists and test‑protocol templates.
Report deliverables — what’s in the full study
- Market sizing and demand‑driver models (historical 2020–2025 and base‑case forecast 2026–2032) with scenario toggles for energy prices, CAPEX cycles, and infrastructure spend.
- Vendor benchmarking: product portfolios, service economics, and aftermarket capture. Comparative assessment includes automation & telemetry capabilities, retrofit friendliness, and total cost of ownership profiles.
- Cost‑build analysis: component and material cost breakdowns, labor intensity maps, and sensitivity testing on alloy and polymer pricing.
- Regulatory compliance toolkit that maps API RP 11S and ISO 13709 implications to test requirements, lead times, and third‑party certification costs.
- Go‑to‑market playbooks for three archetypal players — incumbent global OEM, regional systems integrator, and niche retrofit specialist — with sales motions, channel models, and margin targets.
- Risk register and mitigation measures covering supply chain disruption, permitting, and operational safety incidents, with insurance and performance bond considerations.
Competitive landscape: synthesis and implications
The HPS competitive map reflects a mix of global energy systems leaders, specialized pump manufacturers, and regional integrators. Key industry players we profiled include major energy‑services and equipment firms located in established oilfield hubs as well as smaller niche manufacturers that emphasize modularity or retrofit economics.
- Large OEMs and energy‑services firms — incumbents have leveraged scale, broad after‑sales networks, and integrated automation offerings to lock in multi‑year service agreements. Recent product introductions and strategic acquisitions highlight a push to blend hardware with data services and extended warranties, elevating the importance of lifecycle service economics in procurement decisions.
- Specialized pump manufacturers — these firms compete on product fit, field reliability, and retrofit compatibility. Their value propositions often center on lower maintenance, straightforward parts availability, and agility to serve non‑standard injection demands.
- Regional integrators and component suppliers — capable of delivering rapid retrofits and local service coverage, these players can be attractive partners for large operators seeking cost control and speed to market in specific basins or industrial clusters.
Notable recent moves illustrate strategic direction: new product launches integrating automation and analytics, targeted acquisitions to consolidate product lines, announcements of retrofit services that extend the life of installed fleets, and an expansion of HPS solutions into adjacent sectors (for example geothermal reinjection) by some vendors. These developments signal that technology differentiation is becoming as important as cost leadership.
Operational dynamics shaping supplier economics
- Material and component exposure: High‑strength steel alloys and specialized polymers remain a dominant share of input cost for horizontal pump systems. Procurement teams need transparent component indices and alternative sourcing strategies to immunize margins from raw‑material volatility.
- Standards and certification: API RP 11S and ISO 13709 require specific materials and testing protocols for multistage centrifugal pumps in surface use. These standards are driving both development costs and lead times for new models.
- Energy and automation: Energy efficiency mandates and the integration of automation/telemetry have already reduced average energy consumption per unit in recent deployments. Energy‑savings features are now credible sources of operational differentiation and payback propositions for buyers.
- Labor and lifecycle service: While automation reduces some on‑site tasks, skilled service technicians remain in high demand to maintain increasingly complex HPS installations. Service network density is a persistent competitive advantage.
- Infrastructure drivers: Near‑term deployment is supported by continued expansion in midstream infrastructure — notably saltwater disposal and fluid‑transfer pipelines — which increases the addressable market for surface pumping systems.
Strategic scenarios for 2026–2032 and recommended actions
We frame three plausible scenarios that crystallize strategic options for 2026 planning cycles. Each scenario drives a different mix of commercial and operational priorities.
- Baseline (Policy and demand steady): Market follows the modeled CAGR with steady institutional investment in midstream. Priorities: optimize TCO, invest selectively in automation, expand retrofit services to capture installed base revenue.
- Efficiency and electrification acceleration: Faster adoption of energy‑efficient drives and electrified pumping systems compresses fuel‑linked operating costs. Priorities: accelerate R&D on low‑energy designs, retrofit solutions, and analytics packages that quantify energy savings for buyers.
- Consolidation and premiumization: Continued consolidation among top suppliers and vertical integration of services leads to a two‑tier market. Priorities: consider bolt‑on acquisitions to secure aftermarket revenue, or double down on premium service contracts and certification to defend pricing.
Across all scenarios, three actions are consistently high ROI: (1) build or secure a high‑quality aftermarket and retrofit value proposition; (2) formalize certification and quality management processes to shorten procurement cycles; (3) create flexible sourcing strategies for critical alloys and polymers to protect margins.
How executive teams should use the full PW Consulting study
- Use the model to run tailored forecasts with your company’s operating assumptions (energy costs, fleet utilization, CAPEX cycles).
- Apply the vendor‑scorecard to prioritize OEM partners and to design RFP language that enforces lifecycle performance metrics.
- Deploy the procurement playbook to renegotiate supply contracts and to build contingency plans for material shortages.
- Leverage the M&A filter when screening targets, and use the deal valuation templates to stress‑test synergies in service revenue and spare‑parts optimization.
Conclusion — the strategic value of a data‑informed stance in 2026
The 2026 planning horizon will reward organizations that combine discipline in capital allocation with operational agility: the HPS market continues to grow at a mid‑single‑digit pace, but winners will be those who convert product and service innovations into predictable aftermarket revenue and demonstrable energy savings. Our full study equips leaders to quantify those choices across scenarios and to move from high‑level strategy to executable plans.
For the complete dataset — including regional and application splits, detailed subsegment tables, supplier financial benchmarks, and full scenario model access — visit the PW Consulting report page. The appendices contain the granular inputs and downloadable model that operational teams need to execute on the strategic options outlined here.
For detailed analysis of this topic, please visit the official page: HPS (Horizontal Surface Pumps) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


