



PW Consulting: Rectifier Diode Market to Hit USD 298.2M by 2032 at 5.7% CAGR

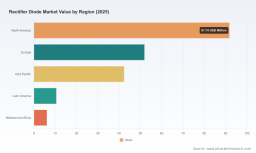
Rectifier Diode Market: Strategic Preview for 2026 Decision-Makers
Executive summary
The rectifier diode market is on a steady, investment-grade growth path. From a market base in 2025 of USD 202.5 Million (base year), historical expansion since 2020 and a projected compound annual growth rate (CAGR) of 5.7% underpin a forecast that pushes the industry toward roughly USD 298 Million by 2032. That trajectory masks a complex set of technological inflections, supply-chain constraints and geopolitical pressures that will determine winners and losers over the next three years.
Rectifier Diode Market
This preview is intended as a strategic teaser: it demonstrates the depth of analysis in our full Rectifier Diode Market study published by PW Consulting, and highlights the kinds of decisions that corporate leadership must be prepared to take in 2026. Key segment-level details and full data tables are intentionally withheld here to encourage direct engagement with the source report, which contains the granular intelligence required for transaction-level moves, procurement negotiations, and product portfolio redesigns.
Rectifier Diode Market
Why this report matters for 2026
-
Budgeting and capital allocation — The combination of a mid-single-digit CAGR and measurable market concentration (CR3 ≈ 28.5%; CR5 ≈ 42.3%) signals a market where scale and selective specialization both matter. CFOs and strategists must reconcile growth-driven demand with concentrated supplier power when planning capex for capacity, tooling, and inventory buffers in 2026.
Rectifier Diode Market -
Technology transition timing — Manufacturers face tradeoffs between incumbent silicon devices and higher-performance materials (SiC/GaN). The market’s steady growth provides room to pilot next-generation rectifiers, but supply realities and qualification cycles will determine the optimal investment horizon.
-
M&A and partnership calculus — The market concentration metrics indicate relevant opportunities for bolt-on acquisitions, distribution partnerships, or strategic alliances to access niche capabilities or expand addressable markets without the time and capital commitment of greenfield capacity.
Market trajectory — what the numbers imply
Between 2020 and 2025 the market expanded from its early-decade base to USD 202.5 Million, and our forecast to 2032 translates that trend into a near-term planning horizon that is characterized by steady, manageable growth rather than hypergrowth. That pattern favors disciplined, risk-aware strategies in 2026: prioritize initiatives with clear payback windows, protect gross margin through supply risk mitigation, and sequence investments that preserve optionality on material and process choices.
Structural dynamics and risk drivers
-
Geopolitics and raw-material concentration — A single-country dominance in critical raw materials can create acute, short-cycle price and availability shocks. Executives must build procurement contingencies and assess alternative sourcing or substitution strategies that are technically feasible and commercially viable.
-
Supply-chain friction for advanced substrates — Lead times for advanced substrates (e.g., silicon-carbide wafers) remain materially longer than for legacy silicon. Extended lead times (on the order of many weeks) require changes to inventory policy, demand forecasting cadence, and supplier contractual terms.
-
Regulatory cost inflation — Tightening environmental regulation is increasing per-unit production costs globally. Product design and process engineers should be briefed to identify quick wins in material selection and process cleanliness that reduce future regulatory exposure and cost escalation.
-
Fragmented trading relationships — Trade restrictions and evolving export controls create uncertainty for multi-region supply chains. Companies need scenario-based sourcing plans that incorporate regional risk premiums and time-to-replace metrics for critical components.
Competitive landscape — what to watch (select players)
Our research digs beyond press releases to evaluate capability maps, product roadmaps, and go-to-market motions of the leading suppliers. Below we highlight core profiles and strategic postures of principal incumbents without disclosing proprietary market shares available in the full report.
-
Diodes Incorporated (Plano, TX) — Strong in general-purpose, fast-recovery and Schottky lines; their product breadth supports diversified industrial and power-supply customers. Expect them to lean into integrated solutions and broadened channel reach for mid-market OEMs.
-
Infineon Technologies (Munich) — Notable for high-voltage disc rectifiers and increasingly for SiC/GaN offerings. Infineon is positioned to capture large conversion-system contracts in industrial and renewable energy segments where higher voltage and efficiency pay back.
-
Vishay Intertechnology (Malvern, PA) — World-class in standard and ultrafast recovery rectifiers, with a focus on automotive and computing markets. Their strengths lie in scale manufacturing and reliability engineering for demanding applications.
-
ON Semiconductor (Phoenix, AZ) — A strong bridge-rectifier and discrete-solution supplier with legacy and modern portfolios. Their go-to-market tends to prioritize systems-level power management customers and tiered product families for mixed BOM footprints.
-
STMicroelectronics (Geneva) — Delivers Schottky, ultrafast and SiC rectifiers with automotive-grade qualifications. ST’s automotive relationships and qualification expertise provide a defensible route to higher-margin segments.
-
Renesas Electronics (Tokyo) — Focused on high-efficiency rectifiers for power supplies and embedded systems. Renesas’ strength is platform integration, supporting customers that prefer supplier consolidation.
-
Toshiba Electronic Devices & Storage Corporation (Tokyo) — Offers a breadth of rectifiers and bridge solutions for both low- and high-frequency applications; their position is most visible in consumer and industrial electronics supply chains.
-
Panasonic Corporation (Osaka) — Supplies discrete rectifiers and bridge rectifiers across automotive and consumer ecosystems. Panasonic’s distribution network and systems-integration experience make them a stable partner for large OEMs.
What the PW Consulting report delivers (high-level)
Our full study is structured to support executable decisions in 2026. It includes:
-
Proprietary market-sizing and forecast models (2020–2032) with scenario variants calibrated to commodity price shocks and trade policy shifts.
-
Supplier performance scorecards and a risk heatmap combining lead-time, concentration, and qualification difficulty for key device families.
-
Go-to-market playbooks for device manufacturers and distributors: SKU rationalization, channel strategy, and pricing levers optimized by customer segment.
-
M&A and partnership screening tools, including an acquisition fit matrix and a short-list of targets by strategic archetype (technology, capacity, or channel).
-
Procurement checklists and contract language templates tailored to mitigate long lead times and single-source exposure for advanced substrates.
-
Operational implementation roadmaps that sequence quick wins (supply stabilization, safety stock policies) and medium-term bets (SiC/GaN qualification, capacity co-investments).
Strategic recommendations for 2026
-
Move from reactive to planned exposure: Establish at least two validated sourcing pathways for critical substrates and semiconductor-grade materials. Given extended lead times, sourcing agility becomes a competitive advantage.
-
Operate a staged SiC/GaN roadmap: Pilot high-value use cases where efficiency yields rapid ROI (e.g., high-voltage power conversion) before scaling broadly.
-
Reassess inventory policy using a multi-factor trigger: combine lead-time, revenue-at-risk, and substitute-availability metrics rather than fixed days-of-inventory targets.
-
Price to value where qualification barriers protect performance differentials: For segments demanding automotive or industrial AEC-grade reliability, pursue premium pricing and longer-term contracts.
-
Design for regulatory resilience: Prioritize material and process choices that minimize future compliance retrofits to avoid cost churn caused by environmental regulation tightening.
Implementation roadmap and decision triggers
Adopt a quarter-by-quarter implementation plan for 2026 with three primary decision triggers: (1) a supplier availability review at the start of Q1 to lock multi-source agreements; (2) a mid-year technology gate to approve SiC/GaN scale investments only if pilot performance and supplier commitments meet lead-time and cost thresholds; (3) an annual pricing review tied to raw-material indexation and regulatory cost pass-through clauses.
Methodology and rigor
PW Consulting’s analysis combines bottom-up capacity audits, vendor interviews, and a proprietary demand model built on historical shipment and revenue trends (2020–2025) and forward-looking adoption curves. Sensitivity testing was run across commodity-price shocks, lead-time stress scenarios, and demand-shift vectors to produce a credible set of strategic options for 2026 planning committees.
How to use this preview
Consider this document as a strategic compass rather than an operations manual. It identifies the highest-impact questions that leadership teams must resolve in 2026 and previews the actionable tools available in our full study. For procurement directors, it highlights necessary contract and sourcing changes. For CTOs and product leaders, it frames the timing for material and architecture decisions. For corporate development teams, it outlines where M&A and alliance value is most likely to reside.
Next steps
For executives ready to act: the full PW Consulting Rectifier Diode Market report contains the segment-level data, supplier rankings, and downloadable financial models required to make binding decisions. Contact our team to obtain the complete dataset, vendor scorecards, and a tailored briefing that maps our findings to your company’s product lines and supply chain footprint.
PW Consulting’s credentialed analysis equips leadership with the macro context, the supply-side realities and the competitive intelligence necessary to convert market growth into sustainable advantage in 2026—and beyond.
For detailed analysis of this topic, please visit the official page: Rectifier Diode Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


