



PW Consulting: Calcium Nitrate Market Poised for 4.8% CAGR Through 2032

Calcium Nitrate Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused preview of our full Calcium Nitrate Market study — a practical, decision-ready intelligence package that senior executives, portfolio managers and procurement leaders must read before finalising 2026 strategies. This article surfaces the macro trajectory, the strategic inflection points and the playbook-level responses you should be preparing now. It intentionally highlights analytical depth while reserving the granular splits and proprietary segment matrices for subscribers of the full report.
Calcium Nitrate Market
Executive snapshot: Market scale and pace
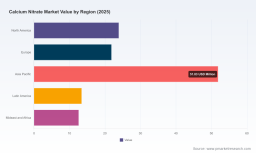
The calcium nitrate market has expanded steadily through the 2020–2025 review window and continues to show moderate, resilient growth into the coming decade. Using 2025 as the base year, our top-line sizing in USD (revenue unit: Million) indicates the market increased from approximately USD 101.3 Million in 2020 to about USD 123.5 Million in 2025. Under our central forecasting assumptions for the 2026–2032 period, the market grows at a compound annual growth rate (CAGR) of 4.8%, reaching roughly USD 170.3 Million by 2032. Early-2026 dynamics — from freight pressure to tariff shifts — already translated into near-term pricing firmness and a subtle reallocation of flows that buyers and producers must internalise when planning contracts and capex.
Calcium Nitrate Market
Why this study matters for 2026 corporate decision-making
- Actionable market sizing with a 2026–2032 forecast horizon: The report converts macro momentum into decision triggers — when to hedge, when to lock long-term offtake, and when to accelerate product differentiation investments.
- Regulation-to-revenue mapping: New drinking-water nitrate limits and environmental scrutiny are already altering product demand patterns and procurement specifications. Our study synthesises regulatory changes into quantifiable demand scenarios.
- Competitive posture and concentration: With the market showing a concentrated supplier base (top-three firms account for a material majority and top-five firms capture a clear super-majority), the study provides tactics for suppliers and buyers to navigate negotiating leverage and risk.
- Operational and pricing stress-tests: We provide scenario-driven models that translate freight, tariff and import disruptions into margin and cash-flow impacts — enabling CFOs to stress test budgets and adjust working capital plans for 2026.
Reading the trajectory — what the numbers tell us
The market’s historical progression and forecasted path reveal three practical implications for 2026 decisions. First, the base is established: the market size rose materially from the low 100s (USD Million) in 2020 to the low 120s by 2025. Second, growth remains steady but non-explosive; the mid-single-digit CAGR through the forecast horizon implies predictable expansion, not runaway adoption. Third, short-term volatility can meaningfully change landed-cost economics: commodity price indices and shipping constraints drove a notable price uptick through mid-2025 and early-2026, which has immediate consequences for margin management and contract design.
Calcium Nitrate Market
Put simply: companies should treat 2026 as a year to optimise positioning — consolidate supply relationships where advantageous, de-risk exposure to freight/tariff swings, and selectively invest in low-carbon or differentiated product lines that earn premium pricing — rather than a year for speculative capacity builds without secured offtake.
Demand and regulatory inflection points
- Regulatory pressure: The December 2025 update to U.S. drinking-water nitrate guidance (Maximum Contaminant Level now at 10 mg/L as N) has immediate ripple effects in both agricultural practice and wastewater treatment protocols. Expect tighter monitoring requirements and, in some jurisdictions, increased demand for specifications and documentation that demonstrate nitrate handling and mitigation expertise.
- Fertilizer-seasonality and pricing: Price indices showed a material rise through Q2–2025, reflecting seasonal buying and supply-side tightness. Freight and tariff moves in early 2026 further firmed prices, shifting negotiating advantage to incumbent producers for short-term contracts.
- Supply-chain friction: Tariff adjustments and import-flow tightening in 2026 increased landed costs for many buyers. This dynamic elevates the strategic value of regional sourcing, inventory buffering and logistics contracts tied to index-escalators rather than fixed-price short-term purchases.
Competitive landscape — concentration, capability and movement
The calcium nitrate market is oligopolistic by nature: the three largest suppliers capture a significant share of global revenues while the top five firms collectively command a dominant position. This concentration drives distinct strategic outcomes — price leadership, differentiated channel access (e.g., greenhouse and fertigation channels), and the capacity to move quickly on low-carbon product endorsements and offtake agreements.
Key industry players to watch and the strategic signals they’re sending:
- Yara International ASA — A vertically integrated approach and plant-nutrition branding remain central. Yara’s portfolio spans liquid, crystalline and greenhouse-targeted grades; its recent long-term offtake agreement for low-carbon calcium ammonium nitrate underscores a move to secure feedstock and to market lower-embedded-carbon fertilizers.
- Haifa Group — Focused on water-soluble variants and speciality grades for both open-field and controlled-environment agriculture; product quality and grower penetration are the firm’s competitive levers.
- OCI Global (OCI Nitrogen) — Leveraging CAN formulations and a low-carbon product narrative positions the firm well as buyers increasingly demand lower-emissions inputs.
- EuroChem, Uralchem, SQM, and regional producers (including firms based in India, China and the U.S.) — These players combine volume capabilities with regional channel strengths and product extensions into industrial applications.
- Specialists and local suppliers (e.g., chemical distributors and niche manufacturers) — Often the most responsive to rapid technical specifications changes and short-haul logistics requirements, making them prime partners for regional buyers and greenhouse operators.
Recent corporate developments illustrate strategic direction: a 2024 capacity expansion by a major producer enlarged granulated capacity, while 2025 saw new low-ammonium product introductions and multi-year offtake agreements to anchor low-carbon outputs. These moves indicate supply-side consolidation around differentiated product tiers (low-ammonium, low-carbon, greenhouse-grade) rather than commodity-only competition.
Where the practical value sits — what our full report delivers
Readers of the complete PW Consulting study will find the following operational and strategic tools designed for 2026 decision cycles:
- Validated market sizing and baseline (2020–2025 historicals; 2026–2032 forecasts) in USD Million, with sensitivity runs and scenario tables that translate macro volatility into revenue and margin outcomes.
- Regulatory impact matrix that maps major jurisdictional changes (including recent U.S. drinking-water guidance) into demand-side shifts and compliance cost estimates.
- Supply-chain playbook: supplier scorecards, logistics-risk heatmaps, and contract-clause templates for inflation/ tariff/ freight pass-through mechanisms.
- Competitive benchmarking: capability matrices and strategic options for incumbents, challengers and pure-play specialists — including recommended responses to recent offtake agreements and product launches.
- M&A and partnership advise: a shortlist of target attributes for bolt-on acquisitions (technology, regional footprint, channel access) and a reverse due-diligence checklist for buyers of calcium-nitrate-exposed assets.
- Commercial execution tools: go-to-market frameworks for launching differentiated low-ammonium or low-carbon grades, pricing ladders and customer-segmentation playbooks for fertilizer versus industrial buyers.
Priority actions for 2026 — what companies should do this quarter
- Audit exposure to tariff and freight variability: implement index-linked procurement clauses and consider partial hedging on long-lead logistics costs.
- Secure offtake or anchor buyers for any planned incremental capacity — the market’s mid-single-digit CAGR supports measured expansion only where sales commitments exist.
- Invest in product differentiation now: low-ammonium formulations, greenhouse-grade solutions and low-carbon certifications increasingly command premiums and reduce vulnerability to commodity-price cycles.
- Revisit customer contracts and documentation standards in light of updated drinking-water nitrate guidance — particularly for suppliers serving irrigation and wastewater-treatment segments.
- Strengthen regional sourcing options and build logistic redundancy to mitigate near-term landed-cost spikes driven by trade policy shifts.
Concluding view and next steps
The calcium nitrate market presents a predictable growth story with episodic shocks driven by freight, tariffs and regulatory shifts. For 2026, the strategic imperative is clear: de-risk supply and price exposure, prioritise differentiated product investments, and align capacity moves with secured commercial pathways. Our full report converts these strategic imperatives into executable plans — with proprietary segmentation matrices, supplier-level benchmarking and financial sensitivity models that are intentionally withheld from this preview to preserve the actionability of the paid deliverable.
For executives preparing budgets, negotiating contracts, or evaluating investments in fertilizer or industrial supply chains for 2026 and beyond, the granular intelligence and modelling tools in the complete PW Consulting study will materially shorten the path from insight to profitable action. Visit our publication page to access the full dataset, segmented revenue breakdowns and downloadable scenario models that underpin the executive recommendations in this preview.
For detailed analysis of this topic, please visit the official page: Calcium Nitrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


