



PW Consulting: Turbo Expander Market — USD 390M in 2025, USD 530M by 2032 (5.5% CAGR)

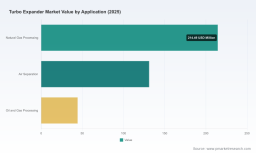
Turbo Expander Market 2026: Strategic Imperatives from PW Consulting’s New Market Brief
As companies reset investment agendas in 2026 amid energy transition pressures, turboexpanders have moved from niche cryogenic components to strategic enablers of efficiency, low‑carbon fuels and distributed energy recovery. PW Consulting’s latest Turbo Expander Market research — grounded on a 2025 base year and projecting through 2032 — delivers the kind of commercially actionable intelligence that senior executives, asset planners and M&A teams need to reframe growth and risk across gas processing, LNG, air separation and industrial energy‑recovery portfolios.
Turbo Expander Market
Market snapshot: steady, measurable growth with durable tailwinds
The global turbo expander market expanded from roughly USD 302 million in 2020 to about USD 390 million in 2025, reflecting steady commercial adoption across liquefaction, natural gas treatment and industrial gases. Our forecast through 2032 models a continuation of that trend — a compounded annual growth rate of approximately 5.5% — with the market approaching the mid‑hundreds of millions of dollars by the end of the horizon. That trajectory is neither hyper‑cyclical nor stagnant: it signals a technology in sustained maturation, driven by both regulatory anchors and incremental process economics.
Turbo Expander Market
Why 2026 is a strategic inflection year
- CapEx reallocation opportunities: Many energy and industrial firms will complete strategy refresh cycles in 2026. Turboexpanders are increasingly evaluated not simply as equipment line items but as value‑creation engines — lowering operational expenditures through energy recovery and unlocking revenue streams via power generation at border‑line gas assets.
- Regulatory and policy momentum: Energy efficiency mandates and decarbonization pathways — from EU carbon targets to national schemes like India’s PAT — materially raise the investment case for expansion turbines in gas infrastructure and air separation units. These policy drivers make efficiency projects more bankable and, importantly, more attractive for public‑private financing structures prevalent in 2026.
- Technology convergence: Advances in materials, aerodynamics and digital controls — alongside modular manufacturing and supplier consolidation — are improving lifecycle economics and shortening lead times. For buyers and OEMs, 2026 is the year to lock in platforms that provide upgrade paths for hydrogen blends, low‑GWP refrigerants and hybrid electrified drives.
Practical report deliverables for decision makers
Our brief is built as an operational playbook for 2026 decisions. Without divulging proprietary segment matrices here, the report contains:
Turbo Expander Market
- Historical demand and baseline market sizing (2020–2025) and a transparent forecasting model (2026–2032) that you can stress‑test against your own project pipelines and carbon‑price sensitivities.
- Technology roadmaps showing which turboexpander architectures are best suited to specific service envelopes (cryogenic LNG, air separation, distributed energy recovery), with comparative lifecycle cost frameworks and retrofit vs. new‑build decision trees.
- Supply chain diagnostics that trace exposure to specialty alloys, critical machining capacity and single‑source subassemblies, along with mitigation templates (dual sourcing, long‑term offtakes, strategic inventory buffers).
- Commercial due diligence templates and vendor scorecards designed to speed procurement, covering technical performance, aftermarket service footprints, warranty economics and uptime guarantees.
- Scenario playbooks for regulatory and market shocks (carbon pricing, LNG demand shocks, raw material volatility) with breakpoints for deferral, acceleration or rebaseline of CAPEX.
- A compact M&A playbook identifying where bolt‑on buys, JV models, or licensing arrangements make strategic sense — including integration checklists and expected value levers post‑close.
Competitive landscape: positioning and competitive moves to watch
The sector shows moderate concentration and a mix of global OEMs, regional specialists and scale‑up challengers. Leading industrial groups and gas‑specialists compete not only on turbine performance but increasingly on system integration, aftermarket services and financing options. Key dynamics in the competitive arena that 2026 buyers should factor into vendor selection include:
- Platform breadth vs. specialization: Large diversified equipment manufacturers bring scale, global service footprints and multi‑technology bundling; specialized turboexpander vendors and newer entrants often offer faster customization cycles, targeted power densities and competitive pricing for retrofit projects.
- M&A and capability consolidation: Recent acquisition activity underscores the push by established players to expand gas‑handling and energy‑efficiency portfolios. Buyers should evaluate how such consolidations affect spare parts availability, warranty terms and long‑term service pricing.
- Capital and partnership models: Strategic investors and energy incumbents are increasingly financing pilot deployments of novel turboexpander systems — a trend that accelerates commercialization of mid‑scale power recovery and distributed energy offerings.
Our vendor profiles provide concise assessments of more than a dozen significant players — from long‑standing names with broad centrifugal portfolios to nimble innovators focused on radial in‑line machines and modular systems. The profiles analyze product fit for LNG, natural gas processing, air separation and emerging low‑carbon niches such as hydrogen‑ready expanders, and they benchmark aftermarket readiness and global service footprints. For commercial confidentiality and to preserve competitive advantage, the deep numerical segmentations and vendor‑specific revenue splits are reserved for the full report.
Recent industry signals that alter supplier and buyer calculus
- Regional scale milestones — including notable installations and commissioning of large turboexpander units — validate demand pull in major liquefaction and gas‑treatment markets and the operational maturity of several suppliers.
- Private capital entering the space via growth financing rounds for specialized turboexpander providers signals acceleration of commercial deployments and potential for new integrated solutions combining power recovery and digital optimization.
- Strategic contracts between midstream operators and turboexpander system providers demonstrate an appetite for integrated operating models, where suppliers also assume partial operating risk or deliver performance‑based contracts.
- Consolidation by diversified industrial groups shows the salience of turboexpanders as enablers of broader energy‑efficiency and gas‑handling portfolios — a dynamic that will shape vendor negotiation power and aftermarket economics in 2026.
Market dynamics and systemic risks
Two systemic forces will shape outcomes through 2032: policy‑driven demand for energy efficiency and industrial decarbonization on one hand, and supply chain exposure to specialty alloys and precision manufacturing on the other. Regulators and international bodies estimate that industrial energy efficiency can account for a substantial portion of emission reductions needed by mid‑century, which elevates the policy support case for turboexpanders. Conversely, reliance on high‑performance steels and tight machining tolerances creates vulnerability to commodity swings and capacity bottlenecks.
For 2026 planning, firms must explicitly stress‑test projects for lead‑time inflation, alloy availability and potential trade‑policy disruptions. Some operators are already pursuing local content strategies and multi‑sourcing frameworks to reduce exposure; others are locking performance‑based service agreements to guarantee output and mitigate operational risk.
Actionable recommendations for 2026
- Integrate turboexpander economics into asset planning: Treat turboexpanders as system‑level economics drivers rather than commodity purchases. Recalculate LCOE and project IRR with energy recovery, reduced compression duty and potential power sales included.
- Prioritize modular and upgradeable platforms: Specify architectures that enable future fuel flexibility (hydrogen blends, LNG boil‑off mitigation) and offer digital retrofits for predictive maintenance to extend service life and lower total cost of ownership.
- Harden supply chains: Secure long‑lead items for critical projects via forward contracts, dual sourcing and inventory pooling with strategic partners; consider local fabrication partners in markets with high localization requirements.
- Consider performance‑based commercial structures: For asset owners with limited CAPEX appetite, explore vendor models that share operational upside through power‑for‑performance or availability‑linked contracts.
- Scan M&A selectively: Target acquisitions that fill clear capability gaps — aftermarket reach, digital control expertise, or niche product lines — and prioritize deals with immediate synergies in service networks and spare‑parts logistics.
Conclusion: what senior leaders must decide in 2026
The turboexpander market in 2026 presents a classic strategic moment: steady, data‑backed growth underwritten by regulatory and energy‑system transitions, coupled with concentrated supplier capability and supply‑chain frictions. The full PW Consulting market brief turns these trends into executable options — from procurement scorecards and retrofit fast‑tracks to M&A targets and scenario‑tested rollout plans. It is designed to shorten decision cycles and reduce execution risk for firms that must move beyond pilots to scale operational gains and carbon reductions.
To access the detailed segmentation, vendor financial benchmarks and downloadable decision templates that will directly inform procurement, CAPEX allocation and M&A screening in 2026, consult the full Turbo Expander Market report on our website.
For detailed analysis of this topic, please visit the official page: Turbo Expander Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


