



PW Consulting: Eye Wash Station Market to hit USD 596M by 2032 at 4.65% CAGR

Eye Wash Station Market — Strategic Preview for 2026 Decision Makers
Executive snapshot
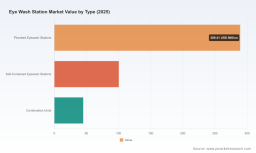
As workplace safety continues to converge with operational resilience, the global eye wash station market has matured from a compliance-driven niche into a strategic component of industrial risk management. Our latest PW Consulting market study (base year 2025) synthesizes five years of historical performance and a seven-year forward view to 2032. The market has expanded meaningfully since 2020 — rising from roughly USD 300 million to an estimated USD 435 million in 2025 — and the forecast period is characterized by steady, mid-single-digit growth (a 2026–2032 CAGR of approximately 4.65%). This trajectory reflects both sustained regulatory enforcement and increasing buyer willingness to invest in integrated emergency-response ecosystems rather than one-off fixtures.
Eye Wash Station Market
Why this research matters for 2026 strategic choices
-
Timing and capital allocation — 2026 will be a turning point for portfolio-level decisions: firms that use the next 12–18 months to align R&D, aftermarket services, and channel investments will capture disproportionate wallet share as buyers shift from price-only choices to lifecycle-value procurement.
Eye Wash Station Market -
Regulatory-driven demand is a stable growth lever — OSHA and ANSI guidance remain central procurement triggers. Practical, standards-aligned product features — instant-activation plumbing, tepid-water delivery, validated flow rates, and clear serviceability — are table stakes. Our study quantifies how regulatory adherence translates into procurement cycles, inspection frequency, and service-contract conversion rates across buyer types.
Eye Wash Station Market -
Risk management and Total Cost of Ownership (TCO) calculus — leading purchasers increasingly evaluate emergency fixtures as part of broader safety ecosystems (training, sensors, testing records). The report models TCO scenarios showing how modest upticks in upfront spend on validated systems reduce downstream incident costs and compliance fines.
-
Channel economics and aftermarket opportunity — replacement parts, maintenance contracts, retrofitting services, and digital monitoring present recurring revenue paths that can outstrip hardware margins. Our analysis provides decision rules for setting service pricing, bundling, and dealer incentives.
Market dynamics and demand drivers
The market dynamics are a blend of regulation, industrial activity, and evolving buyer expectations. OSHA continues to mandate suitable facilities for quick drenching or flushing when workers are exposed to corrosive materials, and the ANSI/ISEA Z358.1 standard remains the authoritative reference for installation, performance, testing, and maintenance. Practical enforcement—inspection cadence, facility audits, and incident-driven retrofits—creates recurring procurement inflections rather than purely one-time sales spikes.
Technology trends are subtle but impactful: improvements in flushing performance, cartridge chemistry, freeze protection, and sensor-driven testing have made higher-specification units more attractive to safety officers who must demonstrate auditable compliance. Simultaneously, product innovation that simplifies maintenance (tool-less access, modular components) supports lower lifecycle costs—an increasingly persuasive procurement argument in capital-constrained environments.
What the report contains — practical, actionable modules
-
Market sizing and trend deck: historical (2020–2025) and forecast (2026–2032) flows, with scenario-based baselines and sensitivity to regulatory tightening, macroeconomic shocks, and industrial capex cycles.
-
Demand-driver matrices and buyer archetypes: segmentation by end-user needs, procurement triggers, inspection schedules, and premium feature uptake rates (note: we withhold granular split tables in this preview to preserve subscriber value).
-
Channel and pricing playbook: margin maps for OEMs, distributors, and aftermarket service providers; recommended pricing levers and contract structures to accelerate recurring revenue.
-
Compliance and operational playbooks: implementation checklists aligned to ANSI/ISEA Z358.1 and OSHA guidance, field-test protocols, training curricula, and audit-ready documentation templates.
-
Opportunity heatmaps and investment cases: prioritized growth pockets and 12–36 month ROI models for product innovation, geographic expansion, and M&A, plus risk registers and mitigation plans.
-
Data annex and methodology: primary interviews, installer surveys, end-user procurement datasets, and the modeling assumptions that support the published forecasts.
Competitive landscape — what incumbents and challengers are doing
The market exhibits low-to-moderate concentration (our CR3 and CR5 measures indicate that the top three and top five firms together occupy a modest share of total revenues), creating an environment where product differentiation, channel strength, and service capability matter more than scale alone. This fragmentation sustains opportunities for both regional champions and global platform players.
-
Haws Corporation (Sparks, NV) — recognized for performance-focused flushing technology (AXION® MSR). Haws’s advantage lies in product engineering and reputation among industrial buyers. Strategic moves to watch: expansion of service offers, certification-backed performance claims, and integration with building management systems.
-
Guardian Equipment Company (Chicago, IL) — strong compliance-oriented portfolio with a focus on ANSI/ISEA Z358.1-aligned solutions. Guardian benefits from distributor relationships and specification-influence in contractor networks. Opportunity: translate specification compliance into packaged service contracts.
-
Bradley Corporation (Menomonee Falls, WI) — positions on customizable solutions for high-risk chemical environments. Bradley’s playbook emphasizes design flexibility and OEM-to-end-user customization, useful in high-complexity accounts.
-
Speakman Company (New Castle, DE) and Haws Safety Products (Honeywell, New York) — both bring extensive channel reach and recognizable safety brands. Their strength lies in after-sales parts availability and cross-selling into adjacent safety product portfolios.
-
Regional specialists and online distributors — Hughes Safety (Canada), LOC Scientific, Unicare (India), EyewashDirect.com, and Sysbel (China) — are notable for local engineering, cost-competitive manufacturing, or digital distribution models. These players create pricing pressure in mid-market segments but are also prime partners for larger OEMs seeking local fulfilment or catalogue reach.
Strategic implications for vendors, distributors, and safety managers
-
For OEMs: prioritize modularity and serviceability in next-generation SKUs. Differentiate through auditable performance (flow verification logs, smart-test sensors) rather than price alone.
-
For distributors and installers: build bundled propositions that pair hardware with scheduled testing, replacement cartridges, and digital maintenance records. These bundles increase switching costs and yield recurring margin.
-
For corporate safety teams: adopt a lifecycle budget model that aligns capital replacement cycles with training and testing spend. Preparing for stricter enforcement and documented compliance will reduce incident-related business disruption.
-
For private equity and M&A investors: the market’s modest concentration and fragmented regional supply create consolidation opportunities. Target acquisition profiles include firms with strong local servicing capabilities, proprietary flushing tech, or digitally-enabled maintenance offerings.
Regulatory and standards context — practical takeaways
OSHA continues to require readily accessible drenching or flushing facilities where corrosive materials may be present, and references to ANSI/ISEA Z358.1 remain central to design and testing requirements. Operationally critical clauses include continuous tepid-water delivery for a minimum duration and adherence to manufacturer installation instructions. For decision-makers, the implication is straightforward: compliance is not just about product purchase but about documented installation, testing cadence, and training. The report provides audit-ready templates and testing protocols aligned to current OSHA and ANSI guidance to materially reduce inspection friction.
2026 playbook — five prioritized actions
-
Convert product specs into verified claims: invest in third-party testing and digital logging to make compliance demonstrable in procurement processes.
-
Monetize aftermarket: design service tiers (basic inspections to premium sensor-backed monitoring) and pilot subscription pricing in select channels.
-
Strengthen installer and contractor relationships: provide co-branded compliance toolkits and training credits to lock specification pipelines.
-
Targeted M&A: pursue tuck-ins that add field-service density or complementary technologies (e.g., sensor makers, cartridge chemists).
-
Build scenario-ready procurement models: equip sales teams with TCO calculators that show payback under different inspection and incident-rate assumptions.
Conclusion and how to use this preview
This preview highlights the strategic contours of the eye wash station market entering 2026: a compliance-rooted market evolving toward lifecycle-based procurement and service-led monetization, with steady growth underpinned by regulatory enforcement and incremental product innovation. PW Consulting’s full report provides the granular segmentation, regional and application splits, supplier benchmarking, and downloadable financial models needed to convert these insights into executable plans. We intentionally withheld core split tables and detailed segment figures from this preview to focus on strategic interpretation — request the full dossier to access the complete datasets, playbooks, and model files that operationalize these recommendations.
Next steps
-
Download the full Eye Wash Station Market report to obtain detailed segmentation, company-level benchmarking, and downloadable financial models.
-
Contact PW Consulting to request a tailored 90-minute briefing for executive teams and a customized 6–12 month implementation roadmap aligned to your portfolio.
For detailed analysis of this topic, please visit the official page: Eye Wash Station Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


