



PW Consulting: Ceramic Ink Market Poised to Hit USD 5.32M by 2032 with 5.79% CAGR

Ceramic Ink Market: Strategic Briefing for 2026 Decisions
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise yet forward-looking industry briefing that translates our Ceramic Ink Market research into the strategic signals executives need to act in 2026. This note communicates the high‑level, decision‑relevant takeaways from the full study — enough to inform near‑term choices and to highlight why a deeper dive is essential. In line with our “trailer” principle, we expose the analytical frameworks and directional findings while deliberately withholding granular sub‑segment tables and proprietary cell‑level data to drive access to the full report.
Ceramic Ink Market
Market Snapshot: Where the market stands and where it is headed
After a steady recovery and structural upgrade over the 2020–2025 period, the global ceramic ink market is entering a growth phase that is both demand‑ and regulation‑driven. Using 2025 as the base year, our topline shows that the market expanded meaningfully from the early‑pandemic trough and is projected to continue on an upward trajectory through the 2026–2032 forecast window. The market’s compound annual growth rate for the forecast period is 5.79%, reflecting a combination of ongoing digitalization of tile decoration, selective product premiumization, and regulatory pressure that favours low‑emission formulations.
Ceramic Ink Market
For strategic planning, the important takeaways are simple: growth is healthy and predictable enough to justify incremental capacity investments, but the nature of that growth is uneven — concentrated where digital tile output, high‑temperature firing processes, and sustainability regulations align.
Ceramic Ink Market
Why 2026 is a decisive year
- Regulation crystallizes product requirements. Recent low‑VOC introductions and publicized reductions in VOC emissions have moved environmental performance from “nice-to-have” to procurement filter for many large buyers in Europe and parts of Asia. Compliance features increasingly drive supplier selection and product roadmap prioritization.
- Digital tile production reaches scale in core markets. High-volume digital decoration, especially where tile manufacturing reaches billions of square meters annually, is a structural accelerant for advanced ink systems — meaning 2026 is the year to commit to digital supply partnerships if you want share in the next wave.
- Regional supply strategies shift to cluster economics. The emergence of manufacturing hubs and new facilities in Southeast Asia is shortening lead times and changing cost dynamics; this matters for both ink makers and tile manufacturers contemplating localized sourcing or CAPEX.
Segment dynamics that should influence capital and R&D choices
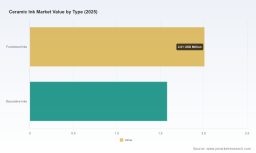
Our segmentation analysis examines the market by product type, application, and region — and produces distinct strategic implications for each axis. Without disclosing confidential split tables, the following directional conclusions emerged:
- Type differentiation matters: Functional (performance‑oriented) and decorative (appearance‑oriented) ink streams follow different value chains and buying cycles. Functional formulations — designed for adhesion, post‑firing performance and compatibility with high‑temperature processes — demand closer integration with tile firing technology and supply of specialized raw materials.
- Application is a proxy for margin and technical complexity: Ceramic tile printing remains the most important application by volume and engineering attention. Glass and food‑contact printing represent adjacent opportunities that require specific compositional and regulatory proof points.
- Regional clusters drive local product mixes: Where clusters optimize for digital tile output or for lower‑cost conventional production, ink requirements diverge. On‑the‑ground intelligence and rapid local collaboration yield advantage.
Competitive landscape: what to watch in supplier strategy
The industry is best characterized as moderately consolidated. Market share sits with a mix of specialized ink formulators and diversified chemical and printing equipment players. A small number of incumbents hold meaningful positions but do not monopolize innovation or distribution; opportunity exists for well‑targeted entrants and for incumbents that pivot to lower‑emission, higher‑value formulations.
Selected strategic profiles from the ecosystem:
- Sicer S.p.A. — European R&D and formulation strength with a public push toward low‑emission digital inks. Their recent announcements on significantly reduced VOC profiles put them at the forefront of the regulatory‑compliant product narrative.
- A.T. Inks (AT Pigments) — A global leader in inorganic pigment‑based solutions engineered for high‑temperature firing processes. Their specialization in dispersions and pigment milling capabilities is a technical moat for tile producers running firing profiles up to 1250°C.
- NUtec Digital Ink — A premium brand with multi‑technology ink portfolios (UV, solvent, water‑based) that serve not only ceramic tiles but also homeware and glass applications; their product breadth supports cross‑sell into adjacent segments.
- EFI — Positioned at the intersection of hardware and ink; advantage accrues from integrated printing systems and proprietary formulations optimized for digital tile workflows.
- KEDA Industrial Group — A machinery and materials player with strong ties to exhibition platforms and regional OEM channels; their presence in trade shows and cluster events signals a go‑to market orientation for local supply expansion.
Recent industry moves reinforce these positioning vectors: late‑2025 and early‑2026 product launches and capacity expansions (including low‑VOC lines and Southeast Asia manufacturing capacity) demonstrate how competition is increasingly played on the sustainability‑performance axis and via localized supply.
Raw materials and process constraints: the supply chain impact
From a procurement vantage point, two technical facts dominate supplier negotiations and investment cases:
- Inorganic pigment formulations require specialized milling and dispersion processes to ensure compatibility with high‑temperature tile firing. Suppliers lacking these capabilities face technical barriers to serve high‑end tile producers.
- VOC and emissions constraints are reshaping formulation chemistry. Low‑emission alternatives are now commercially viable and opening procurement dialogs that include life‑cycle and compliance clauses (e.g., REACH in Europe).
These two realities imply that midstream suppliers should prioritize both process equipment (milling, dispersion) and formulation platforms (low‑VOC chemistries) when allocating capital in 2026.
Practical, prioritized recommendations for 2026 decisions
Below are the core actions we advise for different players, prioritized for impact in 2026.
- Ink manufacturers: Fast‑track low‑VOC and low‑odor product lines and secure certifications required by key buyer markets. Invest in milling/dispersion capacity to support inorganic pigment portfolios and partner with high‑volume digital printer OEMs to co‑develop ink‑printer stacks.
- Tile producers: Reassess procurement specs to include environmental KPIs and digital compatibility. Where feasible, localize ink sourcing or form strategic supply agreements within regional manufacturing clusters to reduce logistics risk and improve color‑consistency support.
- Equipment OEMs and integrators: Bundle ink validation and color management as part of service contracts. Use product warranties and service SLAs to monetize reliability and to lock in ecosystem partners.
- Investors and M&A teams: Target specialized ink formulators with inorganic pigment and low‑VOC expertise, and target players with regional manufacturing footholds in Southeast Asia to capture cluster gains without bearing full greenfield risk.
- Raw material suppliers: Prioritize R&D and scale investments on dispersions and additives that support both high‑temp firing and low‑VOC chemistries; this positions you as a preferred supplier to formula‑hungry ink makers.
Analytics and evidence that support these recommendations
Our conclusions draw on a structured evidence set: historic volume and value growth (2020–2025), scenario forecasts (2026–2032), micro‑interviews with OEMs and formulators, product launches and facility investments, and regulatory scans. Two contextual datapoints animate much of the strategy above:
- Digital ink uptake in the ceramic tile sector — where certain markets now produce in the order of billions of square meters annually — creates sustained demand for advanced formulations and color systems.
- Recent commercial responses to regulatory pressure (e.g., public launches of low‑VOC ink lines and facility expansions in Southeast Asia) show both a near‑term market willingness to pay for compliant, higher‑performance inks and a supply‑side shift to regionalize production.
What is inside the full PW Consulting report
The complete Ceramic Ink Market study contains: a transparent methodology, historical time‑series analytics, demand drivers decomposed by technology and application, price and cost‑stack analysis, a scenario‑based forecast to 2032, supplier assessments and benchmarking, heatmaps for regional investment attractiveness, and a prioritized action matrix for buyers, suppliers and investors. The report also includes practical annexes — vendor scorecards, technology readiness assessments, and a regulatory compliance checklist — designed to be operationalized in procurement and R&D roadmaps.
To preserve the commercial value of our proprietary segmentation and cell‑level forecasts, the report intentionally does not disclose the granular split tables in this briefing. Those datasets and the underlying assumptions are available in the full report where users can run custom slices and obtain tailored dashboards for executive decision‑making.
Final strategic call for 2026
For executives, the strategic mandate for 2026 is clear: align product roadmaps, capital allocation and sourcing strategies with the twin forces of digitalization and decarbonizing regulation. Companies that integrate low‑emission chemistry, secure pigment and dispersion capabilities, and localize or partner into growing manufacturing clusters will capture disproportionate value as the market grows at the projected mid‑single digit CAGR over the forecast horizon.
PW Consulting’s full study provides the numerical rigor and scenario tools needed to convert this strategic intent into a prioritized, resourced plan. Contact our team to access the complete dataset, the interactive forecast, and tailored advisory support to implement the 2026 actions outlined above.
For detailed analysis of this topic, please visit the official page: Ceramic Ink Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


