



PW Consulting: DSL Chipsets Market to Reach USD 322M by 2032 at 5.94% CAGR

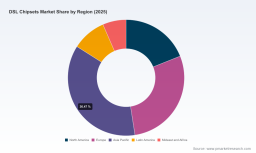
DSL Chipsets Market 2026: Strategic Intelligence Briefing
As the senior industry analyst at PW Consulting, I present an executive preview of our newest market study on DSL chipsets — a decision-grade intelligence package designed to shape corporate strategy through 2026 and beyond. This briefing synthesizes the report’s strategic value, top-line market movement, competitive dynamics, and actionable implications for OEMs, semiconductor vendors, network operators, and investors. The study uses 2025 as the base year, covers 2020–2025 historical performance, and forecasts 2026–2032. Market revenue is reported in Million USD and the model projects a compound annual growth rate (CAGR) of 5.94% over the forecast horizon.
DSL Chipsets Market
Why this research matters for 2026 decisions
-
Market momentum and timing: After a steady recovery from the early 2020s, the DSL chipsets market has continued to grow — moving from the low hundreds of Million USD in 2020 to an estimated 215.0 Million USD in 2025, with forward projections reaching the low three‑hundreds by 2032. That trajectory, paired with the 5.94% CAGR in our central scenario, creates windows for product refreshes, supply‑chain investments, and selective M&A in the next 12–24 months.
DSL Chipsets Market -
Fragmented supplier economics: Concentration metrics in our analysis indicate a market that is not tightly dominated by a single incumbent — the top three and top five suppliers represent a modest share of total revenue. The commercial implications are profound: pricing pressure persists, partnership ecosystems matter more than pure scale, and differentiation via software, power efficiency, and integration wins share.
DSL Chipsets Market -
Strategic risk and resilience: Our work quantifies production and geopolitical risks that should influence sourcing and capital allocation. Leading-edge CMOS processing for high‑performance VDSL2 and G.fast chipsets is concentrated at a few foundries; that concentration creates single‑point vulnerabilities in scenarios of geopolitical friction or capacity reallocation.
What the full report delivers (practical content)
-
Decision‑ready market sizing and scenarios: Base‑year and historical reconciliation, three forecast scenarios (base, upside, downside), and sensitivity analysis calibrated to policy, demand, and supply disruptions.
-
Proprietary demand model: Bottom‑up build across product classes, distribution channels, and end‑use archetypes that can be re‑run with client inputs to test “what‑if” strategies (product timing, price, and channel mix).
-
Commercial playbooks: Go‑to‑market tactics for chip vendors and OEMs, including pricing ladders, bundling options (hardware + DSP software), and recommended partner ecosystems for rapid market entry or defense.
-
Supply‑chain heatmap and supplier scorecards: Foundry exposure, critical BOM items, lead‑time stress points, and mitigation levers (dual sourcing, long‑lead contracts, buffer inventories).
-
Competitive benchmark library: Profiles, capability matrices, and strategic moves for the key vendors operating across central office, CPE, and high‑density DSL segments. The dossier includes product roadmaps, go‑to‑market strengths, and a short list of near‑term M&A or partnership candidates.
-
Regulatory and trade impact analysis: Assessment of incentives, export controls, and regional procurement dynamics affecting product choice and supplier eligibility.
-
Investor section: Valuation implications, growth levers, and triggers for exits or add‑on acquisitions based on technology clusters and regionally driven demand.
Core market dynamics shaping 2026
-
Technology transition and product stratification: DSL chipset demand is being reshaped by legacy ADSL upgrades, VDSL2 extensions, and density‑focused G.fast deployments. Vendors that couple silicon with differentiated DSP algorithms or modular power management extract higher value than those competing solely on unit cost.
-
Price pressure in volume segments: Cost‑sensitive residential CPE remains a volume engine but is subject to aggressive pricing from lower‑cost vendors in certain markets. This dynamic compresses ASPs where scale matters and elevates the strategic importance of cost‑efficient manufacturing and software monetization.
-
Foundry concentration risk: High‑performance DSL chipsets increasingly require advanced process geometries available at a small set of global foundries. This concentration elevates execution risk and favors vendors with secured capacity commitments or backward integration strategies.
-
Geopolitics and market access: Trade restrictions and national security reviews continue to influence procurement decisions in several Western markets, affecting the commercial prospects of some vendors despite their technical competitiveness in other regions.
-
Public policy and industrial incentives: Subsidy programs and incentivized fabrication capacity (for example, recent incentives that underpin new domestic semiconductor plants) are reshaping cost baselines and are expected to create thousands of jobs in host countries over the medium term.
Competitive landscape — who matters and why
-
Platform leaders: Suppliers who combine modem SoCs with vectoring and high‑density central office solutions retain advantages in service provider deals. Their engineering depth supports multi‑DSL standards and central office consolidation strategies.
-
Modular innovators: Vendors offering modular power management and subsystem building blocks are winning design wins where integrators seek time‑to‑market and predictable power envelopes. Recent product launches in 2026 underscore the competitive importance of power and system efficiency in gateway platforms.
-
Analog and component specialists: Suppliers with best‑in‑class analog front‑end and ADC components remain crucial partners for any chipset supplier targeting long‑reach or noise‑constrained deployments.
-
Low‑cost volume players: Certain established vendors in Asia continue to serve mass residential CPE with highly cost‑optimized designs. These suppliers influence global ASP trends and are often the first to scale in large, price‑sensitive markets.
Representative vendors we track closely include global platform and IP leaders, power and analog specialists, cost‑focused regional manufacturers, and pure‑play G.fast specialists. Collective market shares remain distributed — a structural characteristic that drives partnership‑based competition rather than outright monopolization.
Notable recent development
-
In March 2026, a leading broadband semiconductor vendor announced an intelligent modular power management suite targeted at next‑generation gateway SoCs and hybrid access platforms. This product family reinforces the trend toward modular subsystems that reduce OEM integration risk and accelerate time to market for complex multi‑access devices.
Strategic implications and recommended actions for 2026
-
For chipset vendors: Prioritize software/dsp differentiation and power efficiency. Secure foundry capacity through long‑term agreements or design portability to mitigate single‑source risks. Consider modular product lines that enable licensing or co‑design with OEMs.
-
For OEMs and system integrators: Adopt a portfolio approach—protect margins in high‑ASP segments through value‑added services and capture volume via cost‑competitive platforms. Use supplier scorecards and scenario stress tests from the report to inform multi‑year procurement decisions.
-
For network operators: Reassess lifecycle economics of copper‑based upgrades versus alternative access technologies. Leverage vendor roadmaps in negotiation windows and align capital deployment with policy incentives in target regions.
-
For investors and corporate development teams: Use the report’s M&A heatmap to identify targets that add missing capabilities (DSP, power management, foundry relationships) rather than incremental scale alone. Monitor policy shifts and supply‑side capacity builds as deal catalysts.
Methodology and confidence
-
The study combines primary interviews with suppliers and service providers, shipment and bill‑of‑materials analysis, public financials, foundry capacity data, and our proprietary demand model. Historical reconciliation runs from 2020–2025 with 2025 as the base year; forecasts span 2026–2032. We publish results in Million USD and apply scenario stress testing across supply disruptions, ASP compression, and accelerated technology migration.
-
Where we present market shares and segment economics in the full report, numbers are corroborated by multiple independent data sources to ensure reproducibility and to support transaction due diligence.
Trailer — what we intentionally withhold here
This briefing demonstrates the depth and directional conclusions that matter for 2026 planning. To preserve our "trailer" approach and encourage full engagement, we have intentionally withheld detailed regional and application split tables, line‑item revenue forecasts, and granular vendor market share matrices from this public preview. Those datasets — including downloadable model files and supplier scorecards — are available in the full report and client portal.
Next steps
-
For immediate strategic support, PW Consulting offers tailored briefings that re‑run our demand model with client assumptions, supplier risk workshops, and M&A target screening aligned to your portfolio. Contact our research desk to schedule a confidential briefing and obtain the full dataset that underpins these conclusions.
For detailed analysis of this topic, please visit the official page: DSL Chipsets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


