



PW Consulting: WTE market hits USD 311M in 2025 — poised for 3.62% CAGR to 2032

Waste‑to‑Energy Market 2026 — Strategic Preview for Corporate Decision‑Makers
As governments, investors and industrial players recalibrate their energy and waste strategies in 2026, the Waste‑to‑Energy (WTE) sector sits at a pivotal intersection of climate policy, municipal finance and energy systems integration. This preview summarizes the strategic value of PW Consulting’s full market study for executives who must make near‑term capital allocation, M&A and policy engagement decisions. It highlights the macro trajectory, competitive dynamics, regulatory inflections and the practical, transaction‑focused outputs that our full deliverable provides — while preserving the proprietary segment‑level detail that you will find in the complete report.
Waste to Energy (WTE) (Waste-to-Energy) Market
Snapshot: market trajectory and what it means for 2026 decisions
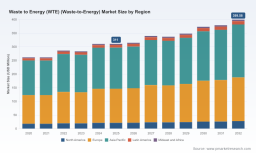
Using a 2025 base year and a historical window covering 2020–2025, our baseline model projects the WTE market across a 2026–2032 forecast period at a compound annual growth rate (CAGR) of 3.62% (values in USD Million). The industry has shown a measured upward trend since 2020, with a recovery from pandemic‑era dislocations and renewed commercial momentum through 2024–2025. Under our central scenario, the market reaches the high hundreds of millions (USD Million) by the end of the forecast window — a trajectory that implies steady, investible opportunities but also a market that will remain sensitive to policy design, feedstock availability and capital cost dynamics.
Waste to Energy (WTE) (Waste-to-Energy) Market
For management teams, the takeaway is straightforward: WTE is not an overnight growth story; it is a strategic, long‑horizon play that rewards disciplined project selection, regulatory alignment and operational excellence. 2026 is a year for positioning — negotiating favorable offtake terms, locking in engineering and technology partnerships, and securing pipeline projects that survive rigorous financial scrutiny.
Waste to Energy (WTE) (Waste-to-Energy) Market
Why this study matters now
- Policy shifts are immediate and material. Recent guidance and regulations (including U.S. federal tax‑credit clarifications, changes to carbon and emissions trading scopes, and national grid code adjustments across multiple markets) materially affect project economics and eligibility for incentives. The study explains how lifecycle assessments, MRV requirements and subsidy frameworks change project valuation and bankability.
- Market consolidation and supplier specialization. A small set of global and regional players dominate engineering, EPC and operations — producing both opportunities for scale and risks from vendor concentration. Our analysis surfaces how to navigate supplier portfolios and construct alternative sourcing strategies.
- Project finance remains issuer‑sensitive. Typical WTE projects require careful alignment of feedstock contracts, PPA/POS structures, and construction risk allocation. The report provides modelled debt‑service coverage scenarios and sensitivity ranges that reflect current pricing and policy regimes.
What the PW Consulting report delivers (practical, transaction‑ready content)
- Proprietary market model (2020–2032) with scenario toggles for policy, fuel price and capital cost shocks, presented in USD Million and calibrated to 2025 base conditions.
- Regulatory and incentives matrix across priority jurisdictions, including practical guidance on documentation and lifecycle analysis pathways for tax‑credit eligibility.
- Technology assessment and vendor benchmarking: technical readiness, typical CAPEX/OPEX tradeoffs, and operational KPIs for alternative WTE routes.
- Investment diligence toolkit: standardized checklists for feedstock quality, residue management, emissions compliance, grid interconnection and PPA negotiation templates.
- M&A and partnership playbook: valuation ranges (transaction multiples and value drivers), integration risks, and recommendations for carve‑out structures and earn‑outs in infrastructure deals.
- Commercial contracting annex: sample contract clauses, performance guarantees, and escalation mechanisms tailored to long‑term WTE plant operation.
- Case studies and applied models: detailed project-level exemplars illustrating bankable structures and failure modes observed in recent plant deployments.
Market dynamics: a synthesis of drivers and structural risks
Three forces will shape WTE investment decisions in 2026:
- Policy and fiscal incentives: Clarifications issued in 2026 around clean electricity tax credits in the United States, and other national measures elsewhere, can convert marginal project economics into bankable returns — provided lifecycle and MRV requirements are met.
- Grid and market integration: National grid code updates and capacity planning changes — from expanded ETS coverage to bespoke feed‑in rules and fixed tariffs for WTE projects in some jurisdictions — materially change revenue certainty. Developers that secure long‑tenor, index‑linked offtakes will outcompete peers in capital markets.
- Feedstock and operational complexity: Availability, composition and pre‑processing costs of municipal and industrial waste remain the single largest operational variable. Successful projects combine robust feedstock sourcing contracts with technology choices aligned to local residue treatment and air‑quality regulation.
Annual market figures (2020–2025) show a sector recovering and stabilizing into 2025, while our 2026–2032 forecast reflects a steady expansion at a mid‑single‑digit CAGR. That profile suggests prioritized, rather than ubiquitous, deployment — attractive for organizations focused on high‑quality, lower‑risk project development rather than speculative roll‑outs.
Competitive landscape — who matters and why
The WTE ecosystem comprises technology suppliers, integrated operators and specialised conversion technology developers. Key players include large global utilities and engineering houses with end‑to‑end capabilities as well as regional specialists focused on construction and O&M. Notable incumbents profiled in the study are multinational service providers and OEMs, and advanced conversion technology developers that offer alternative fuel outputs beyond electricity.
- Integrated service operators provide turnkey offerings and long‑term plant management solutions — attractive for municipalities seeking single‑vendor accountability.
- Engineering and equipment incumbents dominate baseline thermal technologies, while a newer set of firms focus on advanced gasification/pyrolysis and fuels conversion routes.
- Smaller, regional operators can offer faster project mobilisation and local regulatory insight but may lack balance‑sheet capacity for large BOT projects.
The market shows moderate concentration at the top — a structural reality that affects negotiation leverage, technology pricing and procurement timelines. The full report contains a proprietary vendor scorecard and supplier sourcing matrix that supports procurement and strategic sourcing decisions.
Recent developments that recalibrate 2026 strategy
- New large‑scale project starts and equipment supply contracts in Asia and Europe demonstrate continued public‑private appetite for WTE projects under BOT and EPC frameworks, reinforcing a pipeline of investable assets.
- Regulatory moves — from expanded ETS scopes to national grid and tariff rules — are shifting the calculus of revenue certainty and emissions accounting; these shifts are not uniform across markets and require bespoke legal and lifecycle analysis to secure incentives.
- Policy signals providing fixed tariffs or explicit long‑term compensation for interconnection materially shorten payback in several emerging markets where project execution risk is being underwritten by public authorities.
How to use the study in 2026: a short decision playbook
- Prioritise jurisdictions with clear lifecycle accounting frameworks and stable offtake regimes; build an evidence file early to prove tax‑credit and subsidy eligibility.
- Stress‑test project models against policy reversals and grid access delays; include conservative timelines for permitting and interconnection to protect returns.
- Lean on hybrid procurement strategies — pairing global OEMs for core equipment with regional contractors for civil and feedstock logistics to balance performance and cost.
- Design financing packages that separate construction and operational risk where possible (e.g., availability‑based EPC guarantees, long‑term O&M mandates) to attract infrastructure debt at scale.
- Use pre‑emptive ESG and emissions monitoring frameworks to demonstrate compliance with ETS/credit MRV standards and to preserve market access where carbon accounting matters to offtakers.
What we intentionally withhold here — and why
This preview exposes strategic conclusions and actionable guidance while intentionally withholding granular proprietary splits and data that are core to commercial decision‑making — including our full regional and application segmentation tables, vendor scoring outputs, project‑level financial models and detailed transaction multiples. These items are central to transaction execution and are available exclusively with the full PW Consulting Waste‑to‑Energy market report and data package.
Next steps — how PW Consulting supports your 2026 execution
- Customized briefings: rapid, executive‑focused workshops that apply the study’s models to your pipeline projects and capital plans.
- Deal support: targeted diligence, bid‑process participation, and negotiation support for EPC, O&M and offtake contracts.
- Policy engagement: assistance preparing lifecycle analyses and MRV documentation required to access tax‑credits and ETS regimes.
For leaders sizing opportunities, structuring transactions or preparing to bid for municipal and national projects in 2026, PW Consulting’s full report is the operational reference: it converts macro trends into deal‑ready intelligence. Visit our report page to access the complete dataset, models and vendor scorecards that underpin the conclusions summarized here.
For detailed analysis of this topic, please visit the official page: Waste to Energy (WTE) (Waste-to-Energy) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


