



PW Consulting: Laser Capture Microdissection Market to hit USD 383.38M by 2032 (8.55% CAGR)

Laser Capture Microdissection Market — Strategic Preview for 2026 Decision‑Makers
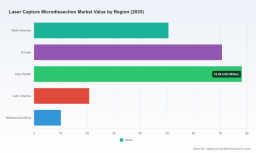
As laboratory workflows push toward single‑cell resolution and precision diagnostics, laser capture microdissection (LCM) is moving from niche core‑facility service to a discrete line item in capital planning and diagnostics roadmaps. PW Consulting’s new market study — anchored on a 2025 base year and a 2026–2032 forecast horizon — delivers an actionable view of that transition. The headline: the global LCM market is on a steady growth trajectory with a compound annual growth rate (CAGR) of 8.55%, expanding materially from the 2025 base and approaching a substantially larger market by 2032. For executive teams planning 2026 spend, partnerships, product launches, or M&A, the study turns macro momentum into practical choices.
Laser Capture Microdissection Market
Why this study matters for decisions made in 2026
- Prioritize capital allocation: With instruments and consumables following different demand rhythms — and capital intensity concentrated on a subset of buyers — buyers and vendors alike need a clear roadmap to deploy limited CapEx and sales resources where ROI is fastest.
- Translate reimbursement shifts into commercial strategy: Early recognition of semiquantitative oncology CPT coding is beginning to reshape hospital procurement and pathology lab value propositions. The study maps how reimbursement choices will affect adoption curves across clinical and research settings.
- De‑risk product development: R&D and product teams can use the model to size near‑term addressable markets, prioritize features (automation, contamination control, downstream integration), and define aftermarket strategies for consumables and reagents.
- Inform M&A and partnership plays: With moderate concentration among leading incumbents, the report identifies adjacencies where bolt‑on assets accelerate access to consumables, software, or pathology services.
What the full report delivers — practical, transaction‑ready outputs
- Market model (historical 2020–2025 and forecast 2026–2032) with scenario runs (base, conservative, and accelerated) to stress‑test investment cases.
- Segmentation layers by product class, application verticals, and geography with methodology notes and assumptions so users can re‑slice the model against proprietary data.
- Vendor scorecards and competitive mapping for leading instrument and consumable suppliers, including technology differentiation, installed‑base logic, and go‑to‑market channels.
- Commercial playbook: pricing elasticity, consumable attach rates, salesforce deployment guidelines, and core‑facility service models that unlock recurring revenue.
- Regulatory and reimbursement compendium focused on near‑term changes that materially affect adoption in diagnostics and translational research.
- M&A heatmap and candidate shortlists, prioritized by strategic fit, revenue synergies, and integration complexity.
Market dynamics and inflection points shaping 2026 strategy
Our analysis identifies three structural forces that will dominate tactical choices in 2026:
Laser Capture Microdissection Market
- Technological evolution and product segmentation: LCM platforms are diversifying along axes of automation, precision, and downstream compatibility (molecular assays, spatial omics). Vendors who can demonstrate clean sample retrieval with low cross‑contamination and plug‑and‑play compatibility with next‑generation assays will capture higher‑value clinical workflows.
- Commercial model tension — capex vs. consumables: Instruments require meaningful capital commitment from buyers while consumables and reagents drive recurring margin. The market exhibits a classic razor/razor‑blade dynamic; commercial strategies that incentivize instrument placements (subscription, reagent‑prepay, shared‑facility models) materially alter lifetime customer value.
- Operational constraints in adopter organizations: Staffing shortages and core facility labor constraints are slowing routine adoption even where clinical or research ROI is clear. Buyers are therefore prioritizing automation, remote management, and systems that reduce hands‑on time per sample.
Regulatory and payer developments are an accelerant. Private payer recognition of oncology semiquantitative coding for workflows that include microdissection is already nudging pathology groups to pilot LCM‑enabled assays. That said, reimbursement adoption is uneven and will be a multi‑year rollout — making it a key sensitivity in our scenarios.
Laser Capture Microdissection Market
Competitive landscape — who matters and why
The vendor field blends multinational microscopy and life‑science platform players with specialist instrument manufacturers. Market concentration is meaningful but not prohibitive: the top three vendors account for roughly half of market revenues, and the top five for closer to two‑thirds. That structure produces both defensive incumbency and tactical openings for niche entrants.
- Thermo Fisher Scientific Inc. (Arcturus heritage)
Strengths: broad commercial reach, legacy Arcturus LCM technology, and an installed base funnel that can be monetized via kits and reagents. Strategic consideration: recent commercialization shifts mean channel and product stewardship choices will affect perceived continuity and OEM relationships. For competitors, Thermo’s scale makes it a logical partner or formidable competitor in bundled solutions. - Molecular Machines & Industries GmbH
Strengths: precision single‑cell systems and automation options that appeal to high‑throughput research facilities. Strategic consideration: execution on software‑driven automation and validated workflows positions the firm well for translational pipelines where throughput and contamination control are priorities. - Carl Zeiss AG
Strengths: integration of microdissection functionality with established microscopy platforms provides a seamless offering to life sciences labs. Strategic consideration: Zeiss’s systems are attractive when imaging and microdissection are bundled, but converting microscope customers to recurrent consumable purchases requires tailored aftermarket strategies. - Leica Microsystems
Strengths: strong performance in precision cutting and a presence in academic core facilities. Recent on‑site demonstrations of next‑generation systems at leading imaging cores underscore Leica’s focus on field validation and end‑user experience. Strategic consideration: field evidence and university endorsements can accelerate adoption — particularly when clinical validation programs are co‑developed with academic partners. - Laxco, Inc.
Strengths: focused LCM systems and the commercialization of specific Arcturus‑era assets position Laxco as a specialized operator with potential for fast, tactical innovation. Strategic consideration: as a nimble player, Laxco may be an attractive partner for larger OEMs seeking to expand instrument portfolios or for investors aiming at platform consolidation.
Strategic implications and recommended actions for 2026
- Instrument OEMs: Prioritize modular automation and software integrations that reduce operator time. Introduce bundled commercial models (subscription, reagent commitment) to lower procurement friction for customers with constrained capital budgets.
- Consumable and reagent companies: Capture aftermarket economics by validating consumables across leading downstream assays and establishing loyalty programs tied to performance metrics. Invest in co‑development with assay vendors to embed consumables in clinical workflows.
- Core facility operators and hospital labs: Use blended acquisition models (capital + service) to access advanced LCM capabilities without over‑exposing balance sheets. Embed LCM into translational research pipelines to attract grant funding and industry collaborations.
- Investors and M&A teams: Target assets that extend consumable portfolios, software analytics, or pathology service capabilities. Consider tuck‑ins that accelerate aftermarket penetration rather than large instrument bets alone.
- Payers and policy advisors: Monitor clinical validation studies that quantify how LCM changes diagnostic yield and downstream treatment decisions; early reimbursement pathways can materially change uptake curves.
How PW Consulting’s dataset converts insight into action
The full report contains the underlying market model and datasets that allow teams to re‑run scenarios with proprietary inputs (e.g., installed base counts, lab throughput, contract terms). Our methodology is transparent: we reconcile bottom‑up installed base analysis with demand‑side adoption curves and overlay macroeconomic and reimbursement sensitivities. That structure enables rapid answerability to questions like “where will a new automation module pay back within 24 months?” or “which customer segment will deliver the highest consumable attach rate in year one?”
Conclusion — a pragmatic roadmap, not a prediction
LCM is at an inflection where technical capability, clinical interest, and commercial creativity intersect. PW Consulting’s study does not offer a single‑line prophecy; it supplies the scenario tools, vendor maps, and practical recommendations that let leaders make defensible, revenue‑focused choices in 2026. Whether your objective is to grow consumable margin, accelerate instrument placements in translational centers, or identify an acquisition that buys you path to clinical adoption, the study frames the decision space and quantifies the tradeoffs.
For readers seeking the full segmentation, country‑level forecasts, vendor scorecards, and downloadable data tables that underpin these conclusions, the complete report and dataset are available on our website. The preview above highlights the strategic shape of the opportunity — the full study provides the numbers and models you will need to act with conviction in 2026.
For detailed analysis of this topic, please visit the official page: Laser Capture Microdissection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


