



PW Consulting: Sucker Rod Market to Reach USD 3.07 Billion by 2032 at 5.5% CAGR

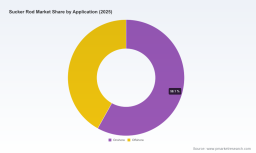
PW Consulting Strategic Brief: Sucker Rod Market (Base Year 2025) — A 2026 Decision-Maker’s Preview
As capital allocation committees, procurement leads, and corporate strategy teams prepare 2026 plans, the sucker rod market presents a mix of steady expansion, technological inflection points, and regulatory pressure that will materially affect supplier selection, product development, and M&A options. This brief previews the full PW Consulting market research on the Sucker Rod Market (base year 2025; historical period 2020–2025; forecast period 2026–2032) and highlights the strategic choices we expect organizations to face in the coming 12–18 months. Currency: USD; revenue unit: Billion.
Sucker Rod Market
Executive summary
Between 2020 and 2025 the global sucker rod market scaled from roughly USD 1.55 Billion to USD 2.10 Billion. Our forecast through 2032 projects continued expansion to approximately USD 3.07 Billion under a compound annual growth rate (CAGR) of about 5.5% over the 2026–2032 period. This trajectory reflects a combination of stable demand from traditional onshore pumping systems, rising adoption of engineered composite solutions in selective offshore and challenging-well environments, and incremental aftermarket and remanufacturing activity.
Sucker Rod Market
Importantly, market concentration is moderate: the top three and top five suppliers account for a meaningful but not overwhelming share of revenue, leaving room for regional specialists, remanufacturers, and specialty alloy providers to capture niche value. The market should be viewed as a balanced arena where scale matters, but targeted capabilities — corrosion resistance, fatigue performance, monitoring integration, and remanufacturing economics — can unlock outsized returns.
Sucker Rod Market
Why this research matters for 2026 planning
- Allocation of capital. Forecasted mid-single-digit growth combined with rising complexity in product specifications requires disciplined capital allocation: incremental production capacity should be balanced against technology investments (FRP, hollow rods, coatings) and digital integration.
- Supplier strategy. Price volatility in steel and a regulatory landscape that varies by jurisdiction make supplier diversification and near-shore sourcing strategies essential to manage risk and lead times in 2026.
- Product roadmap prioritization. The fastest value accrual for many producers will come from higher-margin differentiated components (advanced couplings, specialty alloys, integrated monitoring) rather than increasing commodity rod volumes.
- M&A and partnerships. Moderate market concentration combined with specialized capabilities among small-to-medium vendors creates attractive bolt-on targets for companies seeking to expand technical breadth or regional presence.
Market trajectory & key metrics
Our topline market model (2020–2032) indicates a clear path of recovery and steady growth: from USD 1.55 Billion in 2020 to USD 2.10 Billion in 2025, driven by restored upstream activity and efficiency upgrades, and reaching roughly USD 3.07 Billion by 2032 under a 5.5% CAGR across the forecast window. These numbers are derived from a bottom-up synthesis of rig counts, pumping unit fleets, rod life-cycle replacement rates, and aftermarket service intensity, adjusted for material price pass-through and regional compliance constraints.
While this growth profile is robust enough to justify selective capacity expansions, it does not support indiscriminate greenfield investment in commodity rod production — especially where steel price volatility and potential tariff or licensing restrictions create margin risk.
Dynamics: regulation, raw materials, and operational drivers
- Standards and compliance. API 11B remains the core specification governing rod manufacturing, and vendors continue to reference updated product data sheets and best-practice guidelines. Industry workshops through 2025 reinforced adoption of standardized testing and installation practices.
- Import and trade controls. Import regulation and licensing regimes in some markets (notably certain North American jurisdictions) continue to influence sourcing decisions and create competitive advantages for local or regionally licensed manufacturers.
- Environmental and permitting timelines. Extensions and adjustments to performance deadlines by environmental authorities in mid‑2025 alter the compliance horizon for upstream operators, with knock-on implications for artificial lift retrofit cycles.
- Raw material pressure. Steel price volatility is a persistent factor — Q2 2025 average US steel pricing and the prospect of higher galvanized processing costs tied to iron ore and zinc movements materially affect producers’ cost of goods sold and pricing decisions. Hedging and supply contracts are no longer tactical but strategic necessities.
Competitive landscape — who matters and why
The market is populated by a spectrum of players: established global OEMs, specialized domestic manufacturers, remanufacturers, materials specialists, and cost-competitive regional producers. The following high-level strategic profiles capture the relevant positioning of notable firms covered in our research.
- US Rod Manufacturing (Nappanee, IN). The only US-based privately owned full-service domestic manufacturer — a strategic partner for operators prioritizing domestic supply chains, short lead-times, and API-grade steel product continuity.
- Weatherford International (Houston). Focused on engineered high-strength steel and fiberglass rods with surface treatments and induction case-hardening; recent product showcases and fiber rod announcements underline an offshore and challenging-well playbook emphasizing fatigue and corrosion performance.
- Tenaris (Luxembourg). Global scale and API 11B compliance; strong for operators seeking integrated supply commitments across multiple geographies and premium-grade rod specifications.
- Chinese OEM cluster. A number of manufacturers with cost-focused models and breadth of product lines serve global commodity demand — attractive to price-sensitive operators but subject to licensing, compliance, and trade friction in certain jurisdictions.
- TRC Services (Midland, TX). Represents the remanufacturing and value-recovery model: reprocessing used rods to extend field life, offering an economically compelling alternative in mature basins.
- Materion Corporation & ChampionX. Material science and corrosion-resistant coupling providers that enable operators to extend run-life and reduce intervention frequency — an increasingly important source of differentiation and price-inelastic revenue.
- Regional specialists and integrators (e.g., Q2, Liberty Lift). Provide bundled artificial lift solutions, integration with pumps, and regional aftermarket support — ideal partners for operators seeking consolidated service contracts.
Recent industry moves — product showcases of high-hardness models, collaborations to integrate monitoring systems into rods, and announcements of fiberglass rod lines for offshore services — indicate vendor strategies are converging on three value paths: higher-performing materials, diagnostic-enabled products, and cost-reduction through remanufacturing and regional sourcing.
What PW Consulting’s full report delivers (practical contents)
The full report is built for executable decisions and includes:
- Top-down and bottom-up market sizing (historical 2020–2025; forecast 2026–2032) with sensitivity cases that isolate demand drivers and price scenarios.
- Segment intelligence across region, type (steel, FRP, hollow), and application (onshore/offshore) with anonymized trend matrices to support commercial prioritization (note: granular segment tables are reserved for the full report).
- Supply chain mapping and a raw-materials stress test that quantifies margin exposure to steel, galvanization, and alloy inputs.
- Competitive benchmarking and capability heatmaps for the major suppliers, plus a short-list of due-diligence questions for M&A or strategic partnerships.
- Go-to-market playbooks for three archetypes: global OEM, regional low-cost manufacturer, and engineered-component specialist — each with product, sales, and channel KPIs for 12–36 month horizons.
- Regulatory and trade impact assessment (API standards, licensing, import controls) with recommended compliance pathways.
- Financial model templates, unit-economics calculators, and an investment decision checklist tailored for 2026 capital planning cycles.
Strategic implications and prioritized actions for 2026
For executive teams planning budgets and initiatives for 2026, we recommend the following prioritized actions.
- Lock in strategic supply agreements with price collars. Given steel volatility, negotiate multi-year contracts with indexed pricing and galvanized-processing cost-sharing clauses to preserve margins and predictability.
- Invest selectively in differentiated components. Prioritize R&D and commercial roll-out for high-margin elements (advanced couplings, specialty alloys, coated rods) where vendors can command premium pricing and reduce intervention frequency for customers.
- Accelerate remanufacturing and circular strategies. In mature basins, remanufacturing can reduce total cost-of-ownership; consider partnerships or minority stakes in remanufacturers to secure feedstock and service capacity.
- Pilot integrated monitoring on high-value wells. Partner with control-system vendors or collaborators (see recent monitoring collaborations) to pilot condition-based rod monitoring that can reduce downtime and create data-driven upsell pathways.
- Prioritize regulatory coverage and licensing diligence. For market expansion, ensure products meet API 11B requirements and pre-clear imports where applicable; regulatory friction can nullify low-cost advantages.
- Refine M&A scorecards. Target bolt-ons that fill capability gaps (composite rod expertise, specialty couplings, regional service networks) rather than commodity capacity increases alone.
KPIs to monitor through 2026
- Rod run-life (average months between interventions)
- Average selling price per rod length, adjusted for material surcharge
- Share of sales from engineered/aftermarket components
- Percentage of capacity under long-term contract
- Inventory days and lead-time-to-customer
- Compliance incidents and licensing exposure by market
Final note — why PW Consulting’s research is the operational advantage
This preview is designed to show the connective tissue between market dynamics and the decisions 2026 leaders must make. The full PW Consulting Sucker Rod Market report contains the granular datasets, scenario models, supplier scorecards, and contractual templates that translate the market’s 5.5% CAGR and forecasted USD 3.07 Billion runway into actionable, finance-backed choices. We have deliberately withheld granular split tables in this public briefing to preserve the report’s utility as a decisive planning tool; clients who require the detailed segment breakouts, region-by-region demand curves, and supplier-level revenue estimates will find them in the complete dataset and model package.
To convert the market trajectory into competitive advantage in 2026 — reduce exposure to raw-material shocks, prioritize high-margin engineered offerings, and secure supply through targeted partnerships — organizations need not only good information but executable options. PW Consulting’s full report is structured to deliver both.
For detailed analysis of this topic, please visit the official page: Sucker Rod Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


