



PW Consulting: Liquid Biopsy Market to Reach USD 8,610M by 2032 at 14.85% CAGR

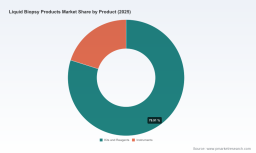
Liquid Biopsy Products Market — Strategic Outlook for 2026 Decision-Makers
The liquid biopsy market is entering a decisive phase. As companies, investors, and health systems plan their 2026 moves, they must interpret a rapidly expanding total market while navigating technological plurality, regulatory inflection points, and shifting commercial models. This briefing—an executive introduction to PW Consulting’s full Liquid Biopsy Products Market study—summarizes the strategic insights that matter most to C-suite leaders and corporate strategy teams preparing for near-term action. It intentionally signals depth and practical utility while reserving granular subsegment figures for the full report.
Liquid Biopsy Products Market
Why 2026 Is a Pivotal Year
Liquid biopsy has moved from high-potential science into scalable clinical deployment. Our base-year framing (2025) and the forecast window (2026–2032) show a clear trajectory: from a market measured in the low thousands of USD million in 2025 to a multi-billion market by the early 2030s, underpinned by a compound annual growth rate of 14.85%. That pace reflects accelerating adoption across clinical applications, expanding use of NGS and digital PCR platforms, and the rise of multi-cancer early detection programs.
Liquid Biopsy Products Market
For strategy teams, the consequence is straightforward: near-term investments and partnerships made in 2026 will disproportionately determine market position across the next funding cycle. The market’s growth profile creates a runway for rapid scale—but competitive advantages are becoming harder to establish and easier to erode without clear playbooks addressing regulation, reimbursement, and integration into clinical pathways.
Liquid Biopsy Products Market
Macro Drivers and Strategic Implications
-
Clinical validation moving to commercial scale: Increasingly robust evidence linking liquid biopsy readouts to clinical decision-making is driving adoption beyond research centers. Organizations that can shorten the evidence-to-adoption timeline—through pragmatic trials, payer pilots, or co-developed protocols—will capture disproportionate share early.
-
Technology differentiation vs. platform convergence: Next-generation sequencing, digital PCR, and algorithmic analytics each offer tradeoffs in sensitivity, cost, and throughput. Expect continued specialization (e.g., highly sensitive ctDNA panels for minimal residual disease) alongside bundling strategies that combine instrumentation, kits, and analysis software. Strategy: choose whether to compete on platform excellence or on integrated solutions that lock customers into ecosystems.
-
Regulatory and reimbursement inflection points: 2025–2026 activity indicates accelerating regulatory submissions and public-private deployments. Commercial strategies must now include regulatory pathway mapping and payer engagement roadmaps early in product development. Companies that neglect reimbursement evidence at pilot stages risk stalled uptake despite strong technical performance.
-
Consolidation vs. fragmentation: The market shows measurable concentration among leading vendors, but technological fragmentation persists. This hybrid state favors strategic alliances, targeted M&A, and channel partnerships that provide complementary capabilities rather than broad vertical integration alone.
What PW Consulting’s Full Report Delivers (Practical, Actionable)
-
Robust market-sizing and scenario models covering 2020–2032, including a transparent methodology, sensitivity testing, and revenue forecasts tied to clinical adoption curves and regulatory timelines.
-
Strategy playbooks for five enterprise archetypes (instrument OEMs, reagent/Kits specialists, clinical service providers, payers/health systems, and platform/software players) with prioritized growth initiatives for 2026.
-
Commercial diligence templates: unit economics, pricing levers, channel cost models, and deployment scenarios for decentralized vs. centralized testing.
-
Technology readiness and differentiation matrix that evaluates sensitivity/specificity tradeoffs, workflow integration, and scaling constraints across common liquid biopsy modalities.
-
Regulatory and reimbursement playbooks, including milestone maps for approvals, recommended evidence generation strategies tailored by market, and payer engagement timelines.
-
Competitive intelligence dossiers for the leading vendors, a deal-activity heatmap, and an M&A stress-test framework to support valuations and integration planning.
Competitive Landscape — Who’s Moving the Market
The market is shaped by a mix of specialist diagnostics companies, instrument manufacturers, and reagent suppliers. Each of the core players is pursuing a distinct route to scale:
-
Guardant Health is focused on comprehensive clinical services and expanding public-private partnerships to deploy on-site testing in major health systems. Its moves show the strategic value of aligning clinical evidence generation with revenue-bearing services.
-
Illumina remains a key platform enabler for NGS-based liquid biopsy applications. Their leverage derives from broad sequencing infrastructure and partnerships across clinical labs and assay developers.
-
Established diagnostics incumbents (e.g., Roche) continue to translate assay-level credibility into clinician-facing solutions, emphasizing regulatory-compliant diagnostics for oncology.
-
Suppliers such as QIAGEN and Bio-Rad focus on the essential sample-prep and reagent layer—components that determine both assay sensitivity and supplier stickiness.
-
Platform players like Thermo Fisher and SOPHiA GENETICS are combining instrument capability with analytics to offer end-to-end propositions that appeal to networked laboratory groups.
-
Multi-cancer early detection/testing players (e.g., Myriad, Exact Sciences) are commercializing population-level screening concepts, forcing incumbents and new entrants to clarify clinical utility and scale economics.
Recent developments through early 2026 underscore market momentum and shifting focal points. New product launches that extend platform capabilities, expanded in‑hospital services, and regulatory progress for multi-cancer tests all shift competitive dynamics and accelerate commercialization opportunities. Each event matters because it changes the evidence, cost, or access equation that payers and providers use to decide.
Strategic Priorities and 90‑ to 180‑Day Actions for 2026
-
Prioritize payer pilots and evidence collectives: Launch targeted payer pilots now, using a limited set of high-impact clinical pathways (e.g., adjuvant monitoring, therapy selection). Structure agreements to accelerate coverage decisions and collect health-economic data.
-
Optimize go-to-market segmentation: Decide whether to emphasize centralized lab services, decentralized point-of-care models, or hybrid partnerships; align commercial resources accordingly and validate via two rapid pilots.
-
Lock in strategic partnerships for critical supply chain components: Secure reagent supply and instrument service agreements to avoid capacity bottlenecks as demand scales in 2026–2027.
-
Invest selectively in clinical evidence generation that maps to reimbursement endpoints: Design trials that demonstrate real-world utility, not only analytic performance.
-
Run an M&A readiness assessment: Identify target capabilities (analytics, assay IP, channel access) and prepare integration plans and valuation guardrails in anticipation of consolidation windows.
Indicators to Watch — Decision Triggers for Course Correction
-
Regulatory milestones for early-detection tests and large payer coverage announcements—signals to accelerate commercialization investments.
-
Price erosion across commoditized reagent segments—prompt to shift to value-based contracts or to refocus on proprietary assays.
-
Rapid adoption by major health systems or national screening initiatives—trigger to scale manufacturing and logistics capabilities.
-
Key competitor moves such as vertical integration or exclusive distribution partnerships—signal to strengthen partner networks or pursue counter‑M&A.
Conclusion — How to Use This Briefing in 2026 Planning
PW Consulting’s full Liquid Biopsy Products Market study is designed to be an operational asset for 2026 planning cycles: it translates market momentum (base‑year 2025 benchmarks and a forecast horizon through 2032) and a 14.85% CAGR into concrete commercial and R&D choices. The difference between a good and a great 2026 is not access to headline growth numbers but the ability to map those numbers into prioritized bets—partnerships, evidence generation, regulatory sequencing, and channel design—that deliver defensible economics as the market scales.
If your team is building 2026 budgets, preparing investor materials, evaluating targets, or designing payer evidence, the full report contains the detailed subsegment-level forecasts, competitive market shares, and scenario models required to make high-confidence decisions. Use this briefing to set the strategic frame; consult the full study to execute with precision.
To access the complete dataset, proprietary segmentation, and the executable playbooks referenced here, please follow the link to PW Consulting’s Liquid Biopsy Products Market report.
For detailed analysis of this topic, please visit the official page: Liquid Biopsy Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


