



PW Consulting: VCI Anti-Rust Paper Market to Reach USD 136.7M by 2032 at 4.8% CAGR

VCI Anti‑Rust Paper Market: Strategic Briefing for 2026 Decisions
Executive snapshot
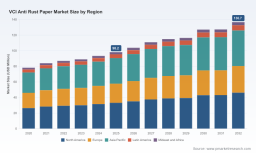
The global VCI (volatile corrosion inhibitor) anti‑rust paper market reached an influential inflection point in 2025 (base year). Our research shows steady expansion through the 2020–2025 historical window and a continued upward trajectory across the 2026–2032 forecast period, underpinned by a compound annual growth rate (CAGR) of 4.8%. Measured in USD (Revenue unit: Million), the market scale in the base year and its projected endpoint by 2032 demonstrate a market that is mature yet still receptive to product innovation, regulatory adaptation, and supply‑chain re‑engineering. Market concentration is meaningful: the top three suppliers account for a dominant share, with the top five nearing four‑fifths of industry revenues — a structure that shapes competitive dynamics, margin discipline, and consolidation potential.
VCI Anti Rust Paper Market
Why this report matters to executives in 2026
- Board and investment committees need a concise, evidence‑based view on whether to invest in VCI capability expansion, enter via M&A, or accept a procurement partnership strategy.
- Procurement and operations teams must translate tightening environmental regulation and rising raw‑material cost into contract clauses, hedging strategies, and alternative‑chemistry roadmaps.
- Product and R&D leaders require clarity on the commercial viability of nitrite‑free, low‑VOC, and biodegradable VCI chemistries versus incumbent formulations.
- Sales and distribution heads are preparing channel plays for 2026 — prioritizing aftermarket services, extended storage protection, and value‑added packaging systems that extend beyond commodity paper rolls.
What the market signals tell us (dynamics)
Three convergent forces are shaping strategic choices in 2026: regulation, chemistry substitution, and operational economics. Regulatory regimes in major markets are increasingly restrictive toward legacy amine‑based chemistries and certain plasticizers, while air‑emission standards place new compliance burdens on manufacturers and converters. These trends accelerate the transition to nitrite‑free and biodegradable inhibitor systems and raise the commercial premium for compliant formulations.
VCI Anti Rust Paper Market
On the cost side, inflation across specialty chemical inputs and logistics has compressed margin structures for commodity VCI papers, forcing suppliers to pursue formulation efficiencies, scale advantages, or product differentiation through multi‑functional substrates (VCI + cushioning, VCI + barrier coatings). Finally, customer demand is bifurcating: OEMs and tier‑1 suppliers buying for critical long‑term storage are willing to pay for demonstrable vapor‑phase protection and recyclability, while high‑volume commodity users remain highly price sensitive.
VCI Anti Rust Paper Market
Competitive landscape: strategic profiles and implications
The market’s incumbent set displays a mix of technical depth, channel access, and product differentiation. Below are directional strategic takeaways from the principal competitors tracked in our study.
- Cortec Corporation (St. Paul, Minnesota) — Cortec’s CorShield® VpCI® coated kraft papers emphasize renewable, recyclable, and fully repulpable chemistries aimed at ferrous and non‑ferrous protection for storage and shipping. Strategically, Cortec positions itself on sustainability credentials and solvent‑free chemistries, attracting customers where end‑of‑life recyclability and indoor air quality matter.
- Daubert Cromwell (Alsip, Illinois) — Known for nitrite‑free formulations and military‑grade offerings, Daubert Cromwell leverages specification‑driven demand (including legacy MIL standards) and multi‑metal protection. For buyers, this supplier is a logical fit when compliance, long shelf life and specification conformance dominate procurement criteria.
- ZERUST Solutions / NTIC (Beachwood, Ohio) — With its ICT® series and reinforced/poly‑coated variants, ZERUST exploits vapor‑phase protection expertise and reinforced substrates for heavier duty applications. Their approach is oriented to higher value use‑cases (longer storage horizons, higher value assets), and they demonstrate how product layering (coatings + VCI) commands a premium.
- Intertape Polymer Group (IPG, Charlotte, North Carolina) — IPG’s VCI2000 series speaks to a manufacturing playbook focused on scalable, nitrite‑free saturated kraft papers with clear multi‑metal claims and extended protection periods. IPG’s scale and conversion capabilities make them a pivotal partner for high‑volume industrial users.
- Armor Protective Packaging (Howell, Michigan) — Armor’s recent innovations blend cushioning with VCI nanotechnology on renewable kraft substrates. Their product roadmap highlights defensive moves into engineered packaging systems that reduce secondary packaging needs and address handling damage along with corrosion protection.
- Rust‑X (USA) — Rust‑X focuses on mechanically robust, laminated VCI papers with superior tear and puncture resistance for parts handling. For operations susceptible to mechanical damage in transit, such materials reduce scrap and warranty exposure.
Notably, product launches in 2026 — exemplified by a high‑profile cushioning + VCI paper introduced in May 2026 — illustrate the industry pivot toward integrated protection systems. Suppliers are increasingly competing on formulation compliance, substrate engineering and demonstrable end‑use performance rather than price alone.
What the full PW Consulting report contains (practical/livable guidance)
- Market sizing and forecast models (base year 2025; historical 2020–2025; forecast 2026–2032) with scenario outputs under alternative regulatory and raw‑material trajectories.
- Regulatory and standards heatmap (REACH, RoHS, CARB and regional emission regimes) tied to actionable reformulation checklists and compliance timelines.
- Supplier scorecards and insourcing/outsourcing decision trees that translate technical attributes (repulpability, nitrite status, VOC footprint, multi‑metal claims, mechanical robustness) into procurement KPIs.
- Commercial playbooks for OEMs, distributors and converters: negotiation levers, contract templates, performance‑based acceptance criteria and inventory hedging strategies.
- Cost‑to‑serve and margin sensitivity models that quantify the impact of key input inflation and logistical disruption scenarios on product profitability.
- M&A and partnership screening framework (fit‑for‑scale, IP defensibility, channel reach) calibrated to a market where the top five players represent the majority of revenues.
- Practical pilots, trial designs and measurement protocols for validating promised protection life (lab + in‑field), including sample size guidance and acceptance thresholds.
- Ready‑to‑use Excel models and executive slides for board briefings, investor teasers and procurement RFPs that preserve commercial confidentiality while enabling immediate decision making.
2026 decision‑maker playbook — prioritized actions
- Run an immediate compliance audit of your VCI supply chain: map formulations against REACH/RoHS/CARB triggers and identify near‑term reformulation risk.
- Segment your usage by criticality (strategic long‑term storage vs. transactional transit protection) and align supplier tiers and contract terms accordingly.
- Initiate supplier performance audits focused on repulpability, VOC emissions, and documented protection durations – make sustainability verifications contractual.
- Negotiate price adjustment clauses tied to defined chemical index baskets or logistics indices to manage raw‑material volatility.
- Pilot integrated packaging systems (e.g., cushioning + VCI) where handling damage and corrosion coexist; measure total cost of ownership rather than unit price.
- Screen potential M&A targets using concentration metrics and capability gaps — prioritize targets that accelerate compliant chemistries, conversion capacity or channel access.
Risks, opportunities and the strategic horizon
The primary near‑term risk is regulatory acceleration that outpaces supplier reformulation cadence, producing specification bottlenecks or temporary supply squeezes. Secondary risks include raw‑material inflation and logistics shocks that compress margins and drive supplier consolidation. Counterbalancing these risks are measurable opportunities: premium pricing for compliant, recyclable, and demonstrably effective VCI papers; productization of packaging systems (VCI + handling protection); and aftermarket services such as certified reconditioning and life‑cycle documentation.
For 2026, winning strategies will be those that integrate compliance and product development with commercial contracting and supply‑chain engineering — not just marketing claims. Firms that move first to lock in compliant supply, validate performance via rigorous pilots, and re‑price to reflect true total cost will defend margins and capture growth as the market expands.
How to use this intelligence
This briefing is designed as a strategic linchpin for 2026 planning cycles. The full PW Consulting VCI Anti‑Rust Paper Market report provides the underlying models, supplier due diligence templates, and scenario workbooks you need to convert the insights above into executable programs. If your 2026 agenda includes procurement rationalization, product reformulation, M&A screening or channel redefinition, the detailed datasets and supplier matrices in the full study are essential.
To access the complete analysis, modelling files and supplier scorecards that support board‑level or investment decisions, request the full VCI Anti‑Rust Paper Market report from PW Consulting — the only resource combining market economics, regulatory roadmaps and hands‑on commercial playbooks tailored for the 2026 operating year.
For detailed analysis of this topic, please visit the official page: VCI Anti Rust Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


