



PW Consulting: Medical Cyclotron Market to hit USD 398M by 2032 at 6.9% CAGR

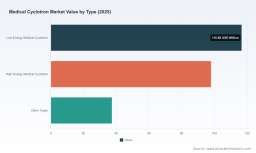
Medical Cyclotron Market 2026: Strategic Primer for Executive Decision-Making
As the medical cyclotron market moves from niche infrastructure into mainstream precision-medicine supply chains, 2026 is shaping up as a pivotal year for strategic choices. This preview, prepared by PW Consulting’s industry practice, synthesizes the macro trajectory, competitive dynamics, regulatory inflections, and the pragmatic levers that should guide board- and C-suite-level decisions. The analysis draws on our proprietary market model (base year 2025), historical trends (2020–2025) and an explicit forecast window through 2032 to highlight where measurable opportunities and systemic risks converge.
Medical Cyclotron Market
Why this market matters in 2026
Medical cyclotrons are no longer solely production assets for local tracer supply; they are capacity nodes in expanding theranostics ecosystems, enablers of on-site manufacturing for next‑generation alpha and beta therapies, and strategic anchors for integrated radiopharmaceutical businesses. Our market model shows an expanding global market, propelled by consistent mid-single-digit expansion—the model uses a 6.9% CAGR across the forecast horizon—indicating both scale and investability for institutions that align clinical, manufacturing, and reimbursement strategies.
Medical Cyclotron Market
From a numbers perspective, the industry has recorded steady growth from the start of the decade and reached a clear inflection by 2025; our forecast to 2032 reflects accelerating adoption as regulatory approvals and reimbursement policies unlock broader clinical use. These aggregate dynamics make 2026 a critical window to capture first-mover advantages in capacity, partnerships, and regulatory positioning.
Medical Cyclotron Market
What the PW Consulting report delivers (practical contents)
- Integrated market-sizing model (USD, Million) with historical series (2020–2025) and scenario-based forecasts (2026–2032).
- Decision-ready commercial playbooks for hospitals, independent radiopharmacies, and device manufacturers (site selection, capex phasing, throughput sizing).
- Regulatory pathway maps and timelines for cyclotron‑produced isotopes and theranostic combinations relevant to 2026–2028 approvals.
- Reimbursement intelligence: billing code mapping, payer positioning tactics, and margin-sensitivity analyses for Ga-68, Lu-177 and emerging alpha emitters.
- Competitor benchmarking and capability matrices juxtaposing technology, service models, installed base, and aftermarket support.
- Supply chain resilience assessment, including critical components, single‑source risks, and mitigation strategies (spare parts, service contracts, and second‑tier suppliers).
- M&A and partnership scouting toolkits with prioritized target archetypes and valuation drivers for 2026 deal activity.
- Operational readiness checklists for running a compliant on‑site radiopharmacy tied to cyclotron deployment.
Each module is built to be executable: executive dashboards, investor-ready slides, and an operational transition plan are included to accelerate board approvals and execution.
Market trajectory: what the numbers say (macro view)
Key macro takeaways from our forecast: the market shows resilient, above-sector growth aligned with broader adoption of PET/SPECT diagnostics, expansion into alpha-therapy production, and national initiatives to localize isotope supply. The base year (2025) is calibrated to recent installations and announced capacity expansions; our scenarios factor in regulatory approvals that are expected to broaden clinical indications and payer access through 2026–2028.
For strategic planning, two implications stand out. First, aggregate growth supports multi-year capacity investments for organizations that can de-risk early through partnerships or service agreements. Second, while the market is growing, it remains concentrated among a limited number of technology providers—creating both competitive pressures and predictable vendor selection processes for deployers.
Competitive landscape — who matters and why
The supplier ecosystem is characterized by a mix of global incumbents, specialized high-output manufacturers, and emergent compact‑cyclotron innovators. The market concentration metrics indicate that the three largest vendors control a dominant share of installed capacity, and the top five together represent substantially more—an important consideration for procurement, service-level agreements, and long-term spare‑parts planning.
- IBA (Louvain‑la‑Neuve, Belgium) — A market leader in particle accelerator technology, IBA combines a broad product portfolio with deep experience in PET/SPECT isotope production and early leadership in targeted alpha therapy enabling technologies. Recent product launches targeting industrial-scale production of Astatine‑211 underscore their push into alpha-emitter supply chains.
- GE HealthCare (Chicago, IL, United States) — A major OEM with strong installed base through its PETtrace series; GE is focused on enabling on-site radiopharmaceutical production that integrates with hospital workflows and theranostic development programs.
- Advanced Cyclotron Systems Inc. (ACSI) (Richmond, Canada) — Known for high-output cyclotrons designed for robust radioisotope throughput; recent investments in dedicated manufacturing facilities point toward scaling for global supply contracts.
- Ionetix (Lansing, MI, United States) — Compact superconducting cyclotron specialist offering smaller-footprint solutions and integrated radiopharmaceutical services—well positioned for decentralized manufacturing models and clinical sites with limited floor space.
- Sumitomo Heavy Industries, Ltd. (Tokyo, Japan) — Supplier of compact, reliable units with strong service and delivery capabilities in mature Asian markets; attractive to buyers prioritizing reliability and local support.
Recent industry moves—product launches, installations, and new facility construction—are consistent with vendors moving to secure demand for isotopes used in both diagnostics and therapy. These tactical plays by suppliers will shape competitive dynamics through 2028 and should inform counter‑strategies by buyers and investors.
Regulatory and reimbursement inflection points
Several regulatory and payer events are contiguous to 2026 and materially affect demand for cyclotrons:
- Regulatory approvals and clearances for cyclotron-produced Ga‑68 tracers and new theranostic pathways are lowering the barrier to hospital adoption and third-party production contracts.
- Recent FDA decisions and scheduled action dates for diagnostic kits tied to cyclotron-produced isotopes create discrete decision points for payers and hospital system investment committees.
- Reimbursement coding for cyclotron-produced isotopes is maturing, enabling clearer revenue models for on‑site production versus outsourced supply—a critical input to capex return models.
- Approvals of radioligand therapies requiring specific isotopes (e.g., Lu‑177) have already created guaranteed clinical demand that feeds cyclotron deployment and long-term supply contracts.
For 2026 strategy, these dynamics mean that procurement and clinical teams must co‑ordinate with regulatory and finance stakeholders earlier in the acquisition process than in past cycles.
Practical strategic implications for 2026 decision-makers
Below are actionable recommendations that senior leaders should consider when integrating cyclotron investments into corporate strategy this year:
- Align capital allocation with regulatory timelines: time major capex decisions to coincide with expected approvals and coding recognition to avoid stranded capacity.
- Prioritize partner models to share technical and regulatory risk: contract manufacturing organizations and technology providers can accelerate time-to-clinic while spreading operational obligations.
- Design redundancy into supply chains: a hybrid model—on‑site micro‑production for just-in-time tracers plus regional high-output hubs for therapeutics—optimizes resilience and margin capture.
- Negotiate service and spare‑parts agreements that reflect concentration risks: given the vendor landscape, long-term service contracts and localized maintenance capabilities materially affect total cost of ownership.
- Use scenario-based valuations for M&A: target assets that either add capacity at scale or provide unique therapeutic-enabling capabilities (alpha-emitter readiness, integrated radiopharmacy). Our report contains scoring matrices for both archetypes.
- Embed payer engagement early: secure coding and coverage pathways in parallel with clinical adoption to avoid revenue timing mismatches post-installation.
Key decision triggers and KPIs
- Regulatory milestones (clearances, approval dates) tied to specific isotopes or production processes.
- Commercial contracts or supply agreements with major radiopharmaceutical developers.
- Utilization thresholds and throughput targets for installed cyclotron capacity.
- Service-level metrics and mean-time-to-repair targets that impact clinical uptime.
- Reimbursement realization rates and payer coverage decisions.
Monitoring these triggers with the appropriate cadence (monthly regulatory watch, quarterly commercialization reviews, and continuous operational KPIs) will materially improve execution certainty.
Closing — why read the full PW Consulting report
This primer outlines the strategic stakes and near-term decision architecture for 2026. The full PW Consulting Medical Cyclotron Market report provides the proprietary models, granular regional and application splits, supplier-by-supplier installed-base analyses, and downloadable decision‑support templates that senior teams need to convert insight into action. If your 2026 roadmap includes cyclotron deployment, theranostics partnerships, or supply‑chain redesigns, the full study is designed to shorten your path from decision to deployment while protecting margin and clinical uptime.
Accessing the full report will reveal the detailed segmentation matrices, price and margin scenarios, and vendor comparison tools we deliberately omit here to preserve the commercial value of our primary research and to ensure readers obtain the executable intelligence they need.
For detailed analysis of this topic, please visit the official page: Medical Cyclotron Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


